

The Delhi High Court stated that the mere fact of the same taxpayer, the same financial year, and the same amount of input tax credit is insufficient to prove that the GST proceedings initiated by the State and the Centre relate to the “same subject matter” under Section 6(2)(b) of the CGST Act.
Shri Krishna Industries has claimed GST ITC on invoices issued by M.R. Enterprises. Previously, the State GST authorities had initiated proceedings u/s 73 for FY 2017-18 and passed a fresh adjudication order. Subsequently, the Central authorities had issued two notices u/s 74 based on a DGGI investigation alleging bogus ITC through invoices without actual supply of goods.
As a result of the two central proceedings, a demand of ₹6,12,000 inclusive of interest and penalties was raised in each case.
Counsel for the applicant has claimed that the central proceedings were barred under Section 6(2)(b) because the state authority had already examined the issue of ITC concerning M.R. Enterprises for the same financial year. He contended that merely changing the legal provision from Section 73 to Section 74 could not justify a duplication of proceedings.
Counsel for the respondents argued that these proceedings related to distinct violations. The State proceedings were initiated u/s 73, whereas the central proceedings arose from an investigation into alleged fictitious transactions. The respondents further pointed out that both cases within the central proceedings pertained to M.R. Enterprises, which held separate GSTINs.
The Division Bench, Justice Anil Kshetrapal and Justice Shail Jain, said that, “The Petitioner has placed considerable emphasis on the fact that the proceedings relate to the same Financial Year and involve ITC of Rs.6,12,000/-. These circumstances, however, cannot by themselves establish identity of subject matter. For the statutory bar under Section 6(2)(b) to operate, it is necessary to establish identity of the liability or contravention which forms the subject matter of the two proceedings.”
The Court found that the petitioner failed to demonstrate that state officials had already adjudicated the specific allegation of fraudulently claiming Input Tax Credit (ITC) without an actual supply. It dismissed the writ petition and allowed the applicant to pursue an appeal u/s 107 and raise its other objections before the appellate authority.
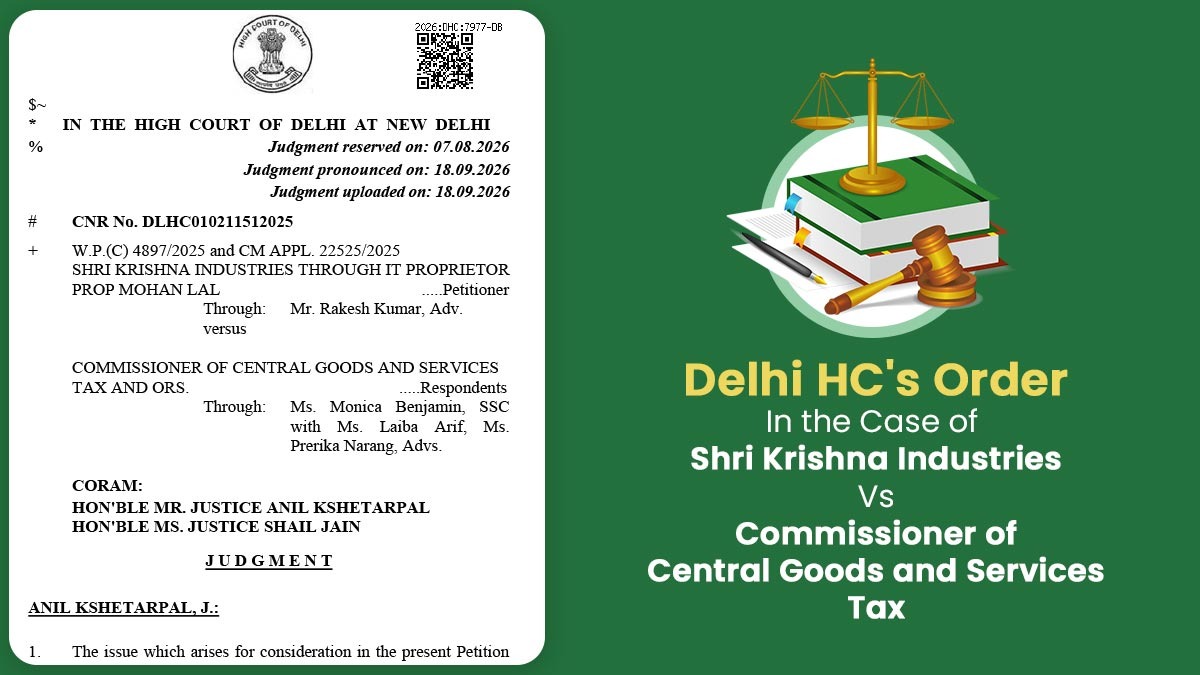
| Case Title | Shri Krishna Industries Vs Commissioner of Central Goods and Services Tax |
| Case No. | W.P.(C) 4897/2025 |
| For Petitioner | Mr Rakesh Kumar |
| For Respondent | Ms Monica Benjamin, Ms Laiba Arif, Ms Prerika Narang |
| Delhi High Court | Read Order |