

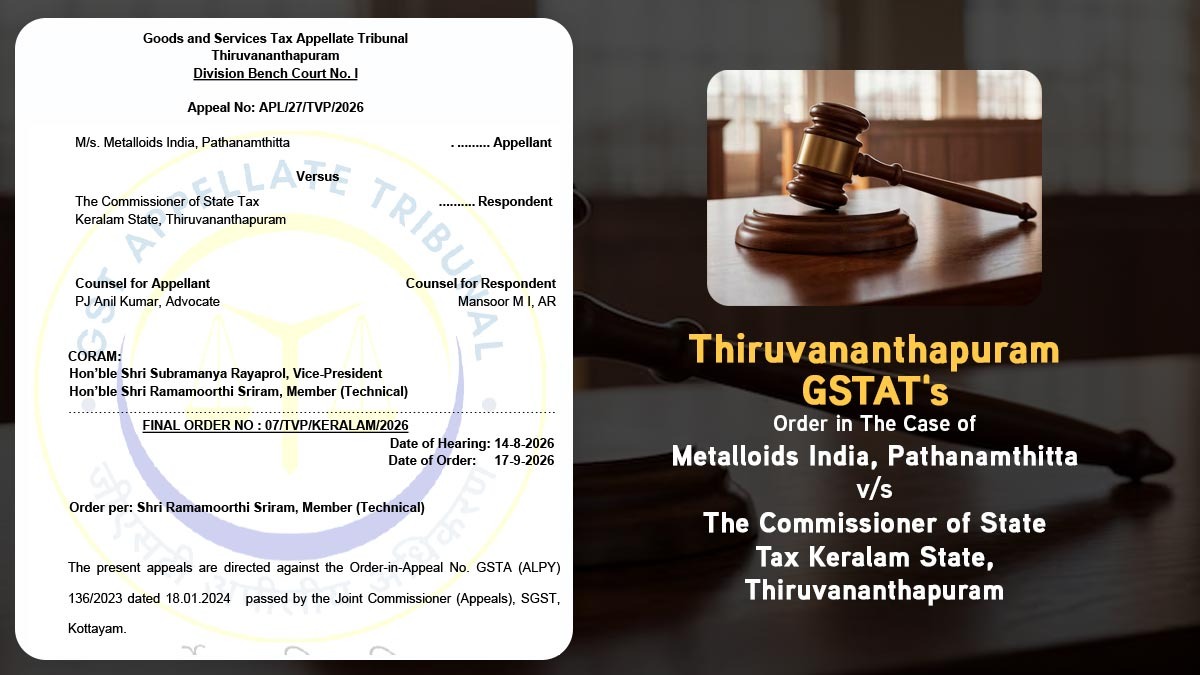
The Thiruvananthapuram Bench of the GST Appellate Tribunal has ruled that when a job worker returns goods to the principal after completing the job work, the transaction value is limited to the job work charges and applicable duties.
The value of the original goods as per the job work cannot be included in the consignment value reported in the e-way bill.
The Division Bench of Vice-President Subramanya Rayaprol and Technical Member Ramamoorthi Sriram said that where the transaction value of the job-work service is less than Rs 50,000, an e-way bill is not obligatory for the return movement.
The matter has arisen from the interception of a vehicle on May 4, 2023, that was carrying aluminium colour-coated coils and GI sheets from a job worker, Roofstyle Industries, Thripunithura, to the appellant at Pathanamthitta.
The authorities purported that the goods were not accompanied by the correct documents and that no e-way bill was present. Therefore, a penalty of Rs 2,50,884 was levied u/s 129 of the CGST/SGST Acts. The taxpayer has paid the amount to secure release of the goods and thereafter contested the penalty.
The appellant said that the goods were returned post finishing of the job work and that the movement was regulated u/s 143 of the CGST Act and the provisions concerning the job work. It said that the goods were carried by the job work invoice, e-way bill, delivery challan, and other relevant documents.
It was observed by the Tribunal that the records of the department exhibited that the job work invoice and the delivery challan were present during interception. It was also observed that an e-way bill was generated for the movement of goods from the job worker to the principal.
Read Also: A Complete Guide on Job Work Under GST India
Concerning the question of the value to be reported in the e-way bill, the Tribunal analysed Section 15 of the CGST Act and Explanation 2 to Rule 138 of the CGST Rules.
It mentioned that, when goods are returned by a job worker after finishing the job work, the supply is of job work services and the transaction value is confined to the job work charges and applicable taxes.
“..when a job worker returns the goods to the principal after completion of job work, the supply is of job work services only and as per section 15 of the KGST / CGST Act, the transaction value shall be restricted to the job work charges plus applicable duties. The value of the original goods which have been subjected to job work is not includable in the consignment value of the goods which is to be reported in e-way bill”, the Tribunal stated.
In this case, the job work invoice exhibited a value of Rs 1841, inclusive of CGST and SGST. The Tribunal said that the generation of an e-way bill was not mandatory because the amount was less than the Rs 50,000 threshold under Rule 138.
The revenue’s claim that the original value of the goods of Rs 6,96,900 should be included in the e-way bill has been rejected by the Tribunal.
The Tribunal ruled that for Rule 138, the value of the principal’s goods upon which job work was performed cannot be included in the consignment value.
“When the goods belonging to a principal are returned by the job worker on completion of job work, the value of the goods on which job work has been undertaken is not includable in the consignment value to be declared in the e-way bill”, the Tribunal stated.
Similar: What is GST E Way Bill & How To Generate Via Online or SMS in Your State?
The Tribunal held that the taxpayer had complied with the applicable GST norms and then concluded that no penalty was to be imposed u/s 129.
Therefore, the appeal was permitted, and the order-in-appeal was quashed with the consequential relief.
| Case Title | M/S JVG Technology Private Limited vs Commissioner CGST |
| Case No. | W.P.(C) 5757/2025 & CM APPL. 26284/2025 |
| For Petitioner | Mr. Abhas Mishra |
| For Respondent | Mr R. Ramachandran, Mr Prateek Dhir |
| Thiruvananthapuram GSTAT | Read PDF |