

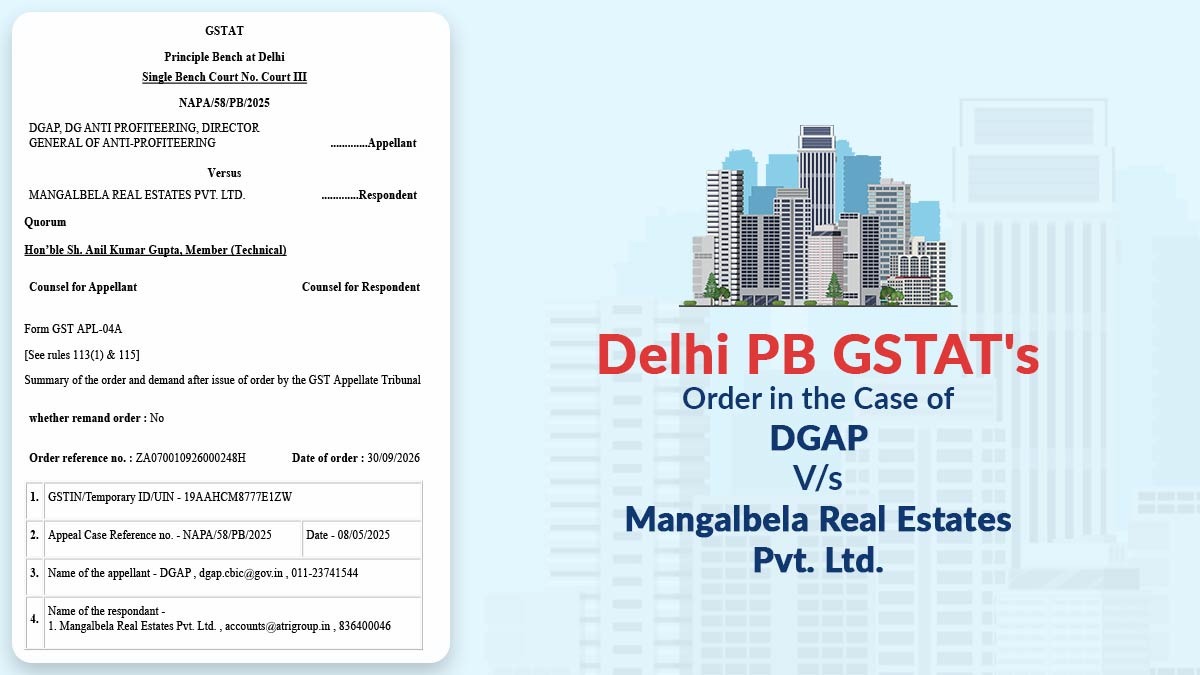
The Principal Bench of the Goods and Services Tax Appellate Tribunal (GSTAT) at Delhi directed Mangalbela Real Estates Pvt. Ltd. to pay Rs. 31.20 lakh to 66 homebuyers of its Atri Green Valley Project in Kolkata, including 18% annual interest.
A single-member bench comprising Technical Member Anil Kumar Gupta rejected the company’s objections against a re-investigation. The bench held that by failing to pass on the benefit of additional Input Tax Credit (ITC) to homebuyers, the company had violated Section 171(1) of the Central Goods and Services Tax (CGST) Act, 2017. It stated:
“The Respondent has not challenged the entitlement of the 66 eligible homebuyers, the total saleable area, the sold area, the per square feet benefit, or the aggregate profiteered amount.”
The matter has arisen from a complaint alleging that Mangalbela Real Estates did not provide the additional ITC benefit to homebuyers after the rollout of GST.
After re-investigation, the Directorate General of Anti-Profiteering (DGAP) discovered that the company’s available ITC had surged from 2.37% in the pre-GST period to 8.42% after the rollout of GST. The DGAP computed the profiteered amount at Rs. 27.86 lakh. It includes Rs. 3.34 lakh in GST; the total amount payable to the 66 eligible homebuyers came to Rs. 31,20,542.
The company contested the re-investigation. It claimed that the Competition Commission of India does not have the authority to reopen the proceedings and that the investigation was barred by limitation.
Dismissing these objections, the Tribunal stated that the re-investigation was in line with the Delhi High Court’s judgment in the case of ‘Reckitt Benckiser India Private Limited vs. Union of India’. In that judgment, the previous methodology for calculating profiteering in real estate projects had been found to be flawed.
It said that the time limit for filing the investigation report under the CGST rules was directory and that the delay did not make the proceedings invalid.
The Bench observed that the company did not contest the DGAP’s calculations or provide proof to specify that it had passed on the ITC benefit to the homebuyers. Under section 171(3A) of the CGST Act, no penalty was liable to be paid because the alleged profiteering period ended before the provision came into effect on 1 January 2020.
Recommended: Delhi (PB) GSTAT Finds No Profiteering as ITC-to-Purchase Ratio Decreased by 0.12% After GST Implementation
Accordingly, the GSTAT has directed Mangalbela Real Estates to pay Rs 31,20,542 to 66 homebuyers apportioned based on the area of the units they sold within three months. Additionally, interest at the rate of 18% per annum must be paid for the period starting from the date the benefit became applicable up to the date of actual payment.
| Case Title | DGAP Vs Mangalbela Real Estates Pvt. Ltd. |
| Case No. | NAPA/58/PB/2025 |
| GSTIN | 19AAHCM8777E1ZW |
| Delhi PB GSTAT | Read Order |