

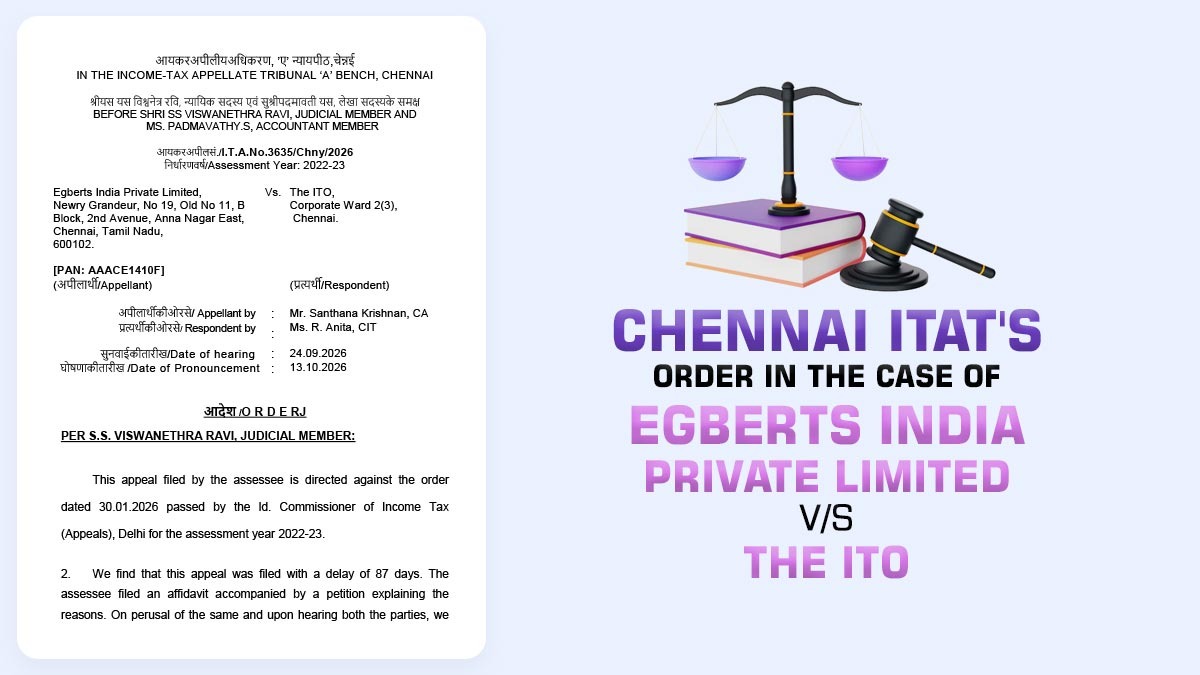
Egberts India Private Limited submitted its income tax return for AY 2022-23 reporting total income of Rs 5,88,38,660. The AO, via an assessment order dated 25 March 2024 passed u/s 143(3) read with Section 144B of the Income Tax Act, 1961, evaluated the taxpayer’s income at Rs 21,31,16,511.
U/s 68, the AO made an addition of Rs 5,42,87,785 for unexplained cash credits and another addition of Rs 10 crore u/s 69 for unexplained investments.
Such additions arose from the purchase of time deposits during FY 2021-22 and a rise in share capital. The AO asked the taxpayer to provide the pertinent information and supporting documents via notices u/s 142(1) and show-cause notices.
However, as the requisite material proof was not provided, the AO proceeded with additions. Afterwards, CIT(A) upheld them.
Read Also: Kerala HC: Additional Evidence Can’t Be Used to Revise Voluntary Tax Returns
The Tribunal condoned the 87-day delay in submitting the appeal after considering the taxpayer’s affidavit and petition explaining the causes for the delay.
In the proceedings, the taxpayer asked for the consideration of additional proof covered in a paper book and requested the case be remanded to the AO for fresh consideration. The revenue does not object to the request.
The Tribunal took into account the relevance of the additional documents to the disputed issues regarding the rise in the share capital and the purchase of the time deposits and stated that the proof was necessary for the impartial adjudication of the case.
It quashed the order of the Commissioner of Income Tax (Appeals) [CIT(A)] and remanded the case to the AO for fresh consideration, providing the taxpayer an opportunity to submit proof in support of its claims.
| Case Title | Egberts India Private Limited vs The ITO |
| Case No. | I.T.A.No.3635/Chny/2026 |
| Appellant by | Mr. Santhana Krishnan |
| Respondent by | Ms. R. Anita |
| Chennai ITAT | Read Order |