

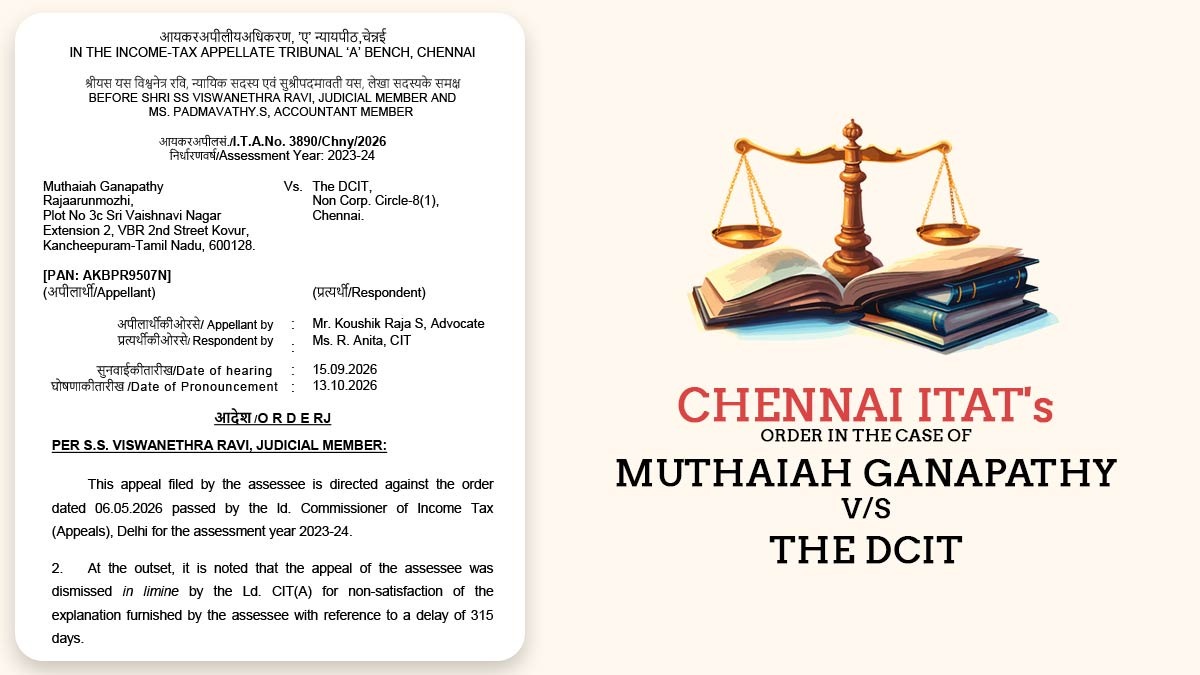
The taxpayer, Muthaiah Ganapathy, submitted an appeal before the Tribunal against the order dated 6 May 2026 passed by the CIT(A), which had dismissed his appeal because of the failure to explain a delay of 315 days in filing the appeal.
Before the CIT(A), the taxpayer requested condonation of the delay. He explained that he could not file the appeal within the prescribed time limit due to long-standing health issues and a serious illness. He argued that the delay was neither intentional nor deliberate.
The Tribunal observed that the AO had computed the income of the taxpayer at Rs 16,78,659 against the returned income of Rs. 54,57,580, with additions concerning unsecured loans from others, sundry creditors, and disallowance of expenses.
Before the AO, no proof was submitted, and the CIT(A) had not analyzed the significant grounds of appeal because the delay was not condoned.
The Tribunal considered the facts and, in the interest of justice, stated that the taxpayer should be provided another chance to challenge the issues on merits.
It quashed the order of the CIT(A) and asked the authority to condone the delay and adjudicate the appeal on merits. Therefore, the taxpayer’s appeal was permitted for statistical purposes.
| Case Title | Muthaiah Ganapathy vs. The DCIT |
| Case No. | I.T.A.No. 3890/Chny/2026 |
| For Petitioner | Mr. Koushik Raja S, Advocate |
| For Respondent | Ms. R. Anita, CIT |
| ITAT Chennai | Read Order |