

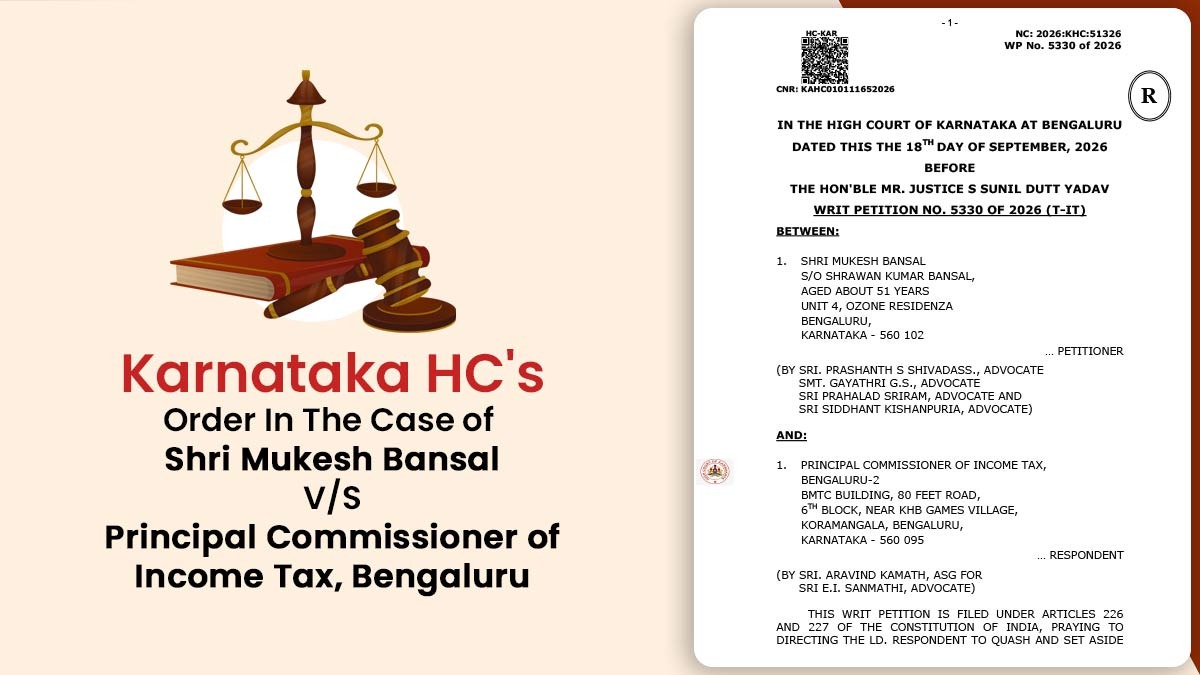
The Karnataka High Court quashed the revision proceedings initiated against taxpayer Mukesh Bansal after his revised ITR for the AY 2019-20 resulted in a refund of Rs 27.13 crore.
Justice S. Sunil Dutt Yadav stated that an intimation issued under section 143(1) of the Income Tax Act, without any adjustment, cannot be considered as an order for practising revisionary powers u/s 263 of the Act. The Bench said that:
“…The corollary would be that, only an intimation under Section 143(1) after adjustment would be treated to be an order under Section 246 and 246A of the I.T. Act. The right of an Assessee is preserved, where adjustment is made under Section 143(1) permitting him to challenge the intimation by resorting to a grievance mechanism of appeal under Section 246 and 246A of the I.T. Act.”
Bansal had submitted his return for AY 2019-20, reporting total income of Rs 231.73 crore and claiming a refund of Rs. 6,07,570. Thereafter, he approached the Central Board of Direct Taxes seeking condonation of delay and permission to submit a revised return.
After their application was considered, they filed a revised return. In this, they treated the amount received from the repurchase of unexercised Employee Stock Options (ESOPs) by their former employer as “Capital Gains” instead of “Salary.”
Also Read: Taxability of ESOP Under Income Tax Act
U/s 143(1), the revised return was processed, which resulted in a refund of Rs 27.13 crore along with interest. Afterwards, the Principal Commissioner of Income Tax, Bengaluru-2, initiated the revision proceedings u/s 263. The Revenue seeks treatment of the ESOP-related receipt as capital gains and objected to the interest provided on the refund.
Bansal contested the revision proceedings before the HC, claiming that section 263 cannot be invoked against an intimation issued u/s 143(1), especially where no adjustment had been made.
The Court said that Section 143(1) delivers a limited yet large automated process which has only particular adjustments, whereas Section 143(2) provides for scrutiny of the return and allows for a comprehensive inquiry, culminating in the issuance of an assessment order.
The Bench relied on the ruling of the Apex Court in Assistant Commissioner of Income Tax v. Rajesh Jhaveri Stock Brokers Private Limited, and said that an intimation u/s 143(1) cannot ordinarily be considered as an assessment order. It observed that the intimation in the case of Bansal was provided without any adjustment. Thus, it could not be considered as an order for Section 263.
Furthermore, the Court observed that finding whether ESOP compensation should be taxed under the head ‘Salary’ rather than ‘Capital Gains’ would require an inquiry that goes beyond the limited scope of Section 143(1). The same exercise can be performed via scrutiny proceedings u/s 143(2).
It added that if the Revenue assumed that the consideration of the ESOP compensation was wrong, then it could have subjected the revised return to scrutiny u/s 143(2). It could not have invoked Section 263 by treating the intimation received under Section 143(1) as an assessment order.
The Court mentioned that it was not analysing the question of whether the ESOP compensation was charged to tax as salary or capital gains. The question before the Court was whether an intimation received under Section 143(1) could be subjected to revision under Section 263. The Bench stated that:
“The Assessing Officer under Section 143(1) may be of the view that such treatment by the Assessee of ‘Repurchase of ESOPs’ cannot be treated as income from ‘Capital Gains’, but must be treated as ‘Salary’. However, such inquiry would immediately take the proceedings outside the purview of Section 143(1).”
It said that “where the intimation under Section 143(1) does not amount to an order, the question of resorting to Section 263 in the present factual matrix does not arise”
Thus, the HC concluded that the impugned notice was issued without jurisdiction, quashed it, and permitted the writ petition of Bansal.
| Case Title | Shri Mukesh Bansal V/S Principal Commissioner of Income Tax, Bengaluru-2 |
| Case No. | WRIT PETITION NO. 5330 OF 2026 (T-IT) |
| Counsel For Appellant | Prashanth S. Shivadass, Gayathri G.S., Prahalad Sriram and Siddhant Kishanpuria, Advocates. |
| Counsel For Respondent | Arvind Kamath, Additional Solicitor General, assisted by E.I. Sanm |
| Karnataka High Court | Read Order |