

After the Supreme Court remanded similar re-assessment cases to the respective High Courts for fresh consideration, the Himachal Pradesh High Court granted permission to approach the court afresh against the re-assessment proceedings and to challenge Section 147A of the Income Tax Act.
The applicant, Nirdosh Bhushan, had submitted a writ petition contesting the Section 148A(d) order and the Section 148 notice. He had contested the sanction or approval u/s 151 and the proceedings emerging from the reassessment notice.
Previously, the HC had disposed of the writ petition after noting that the problem was already pending before the Apex Court. The High Court had directed that the petitioner’s case be decided based on the Supreme Court’s verdict and had stayed further proceedings in the meantime.
Afterward, the Supreme Court determined a batch of reassessment matters in Income Tax Officer v. Tej Partap Singh on April 10, 2026. The Apex Court quashed the rulings based on limited grounds and remanded the case to the respective High Courts for fresh consideration. It allowed taxpayers a chance to contest Section 147A and related provisions before the High Courts.
Read Also: Centre Challenges HC’s Striking Down of Section 147A of Income Tax Act Before SC
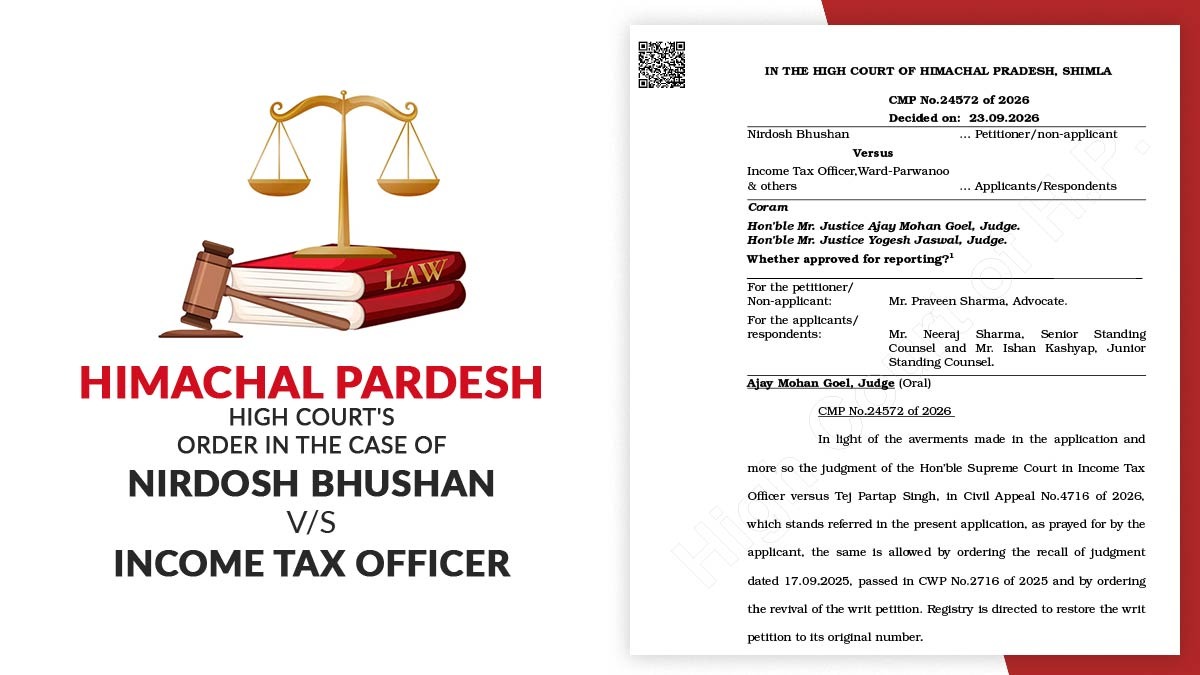
Following the Supreme Court’s verdict, the Revenue Department sought the recall of the Himachal Pradesh High Court’s earlier order. The High Court granted the application, recalled the previous order, and restored the writ petition to its original number.
The Division Bench, Justice Ajay Mohan Goel and Justice Yogesh Jaswal said that, “In light of the fact that the Hon’ble Supreme Court of India was pleased to remand the matters before it to the respective Hon’ble High Courts with liberty to the petitioner therein to lay challenge to Section 147A of the Income Tax Act, if so advised, as prayed for, this petition is closed with liberty to the petitioner to approach the Court afresh on the same cause of action, on which, he had approached the Court earlier with further liberty to the petitioner to lay challenge to Section 147-A of the Income Tax Act and pray any other relief, to which, the petitioner may be entitled to on account of subsequent developments.”
Recommended: Punjab & Haryana HC Quashes Section 147A in Landmark Tax Reassessment Ruling
The Court further directed that the security previously granted to Bhushan would continue for 90 days from the date of the order. The Court clarified that if he does not approach the High Court within that timeframe, the security would lapse.
| Case Title | Nirdosh Bhushan vs. Income Tax Officer |
| Case No. | CMP No.24572 of 2026 |
| For Petitioner | Mr Praveen Sharma, Advocate |
| For Respondent | Mr Neeraj Sharma |
| Supreme Court Order | Read Order |