

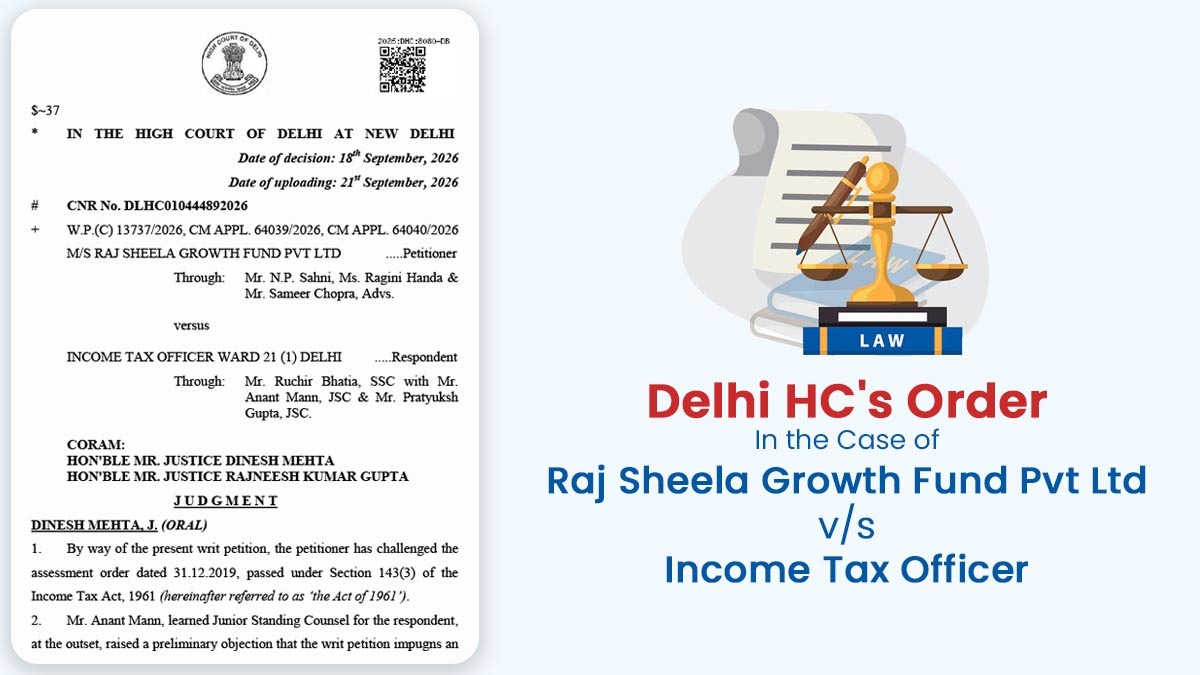
The Delhi High Court has refused to exercise its writ jurisdiction in a challenge related to the jurisdiction of an income tax officer to pass an assessment order, noting that the taxpayer had already claimed the regulatory remedy of appeals against the assessment order and the appeal had been due before the Commissioner of Income Tax (Appeals) since January 2020.
The Division Bench of Justices Dinesh Mehta and Rajneesh Kumar Gupta requested the CIT(A) to determine the pending appeal within two months. A writ petition was heard by the court contesting an assessment order dated December 31, 2019, passed under section 143(3) of the Income Tax Act, 1961.
In the beginning, the Revenue raised a preliminary objection that the assessment order was already under challenge in a statutory appeal before the CIT(A), which had been pending since January 24, 2020.
It was claimed that the applicant could not pursue the statutory appeal and a writ petition before the HC. The applicant had claimed that it had approached the HC concerning the issue of jurisdiction.
Also Read: Successor AO Cannot Reopen IT Assessment Solely Due to a Different Opinion from Original AO
HC had already ruled in favour of the applicant on the jurisdictional question in its judgment dated May 8, 2024, in an earlier proceeding of AY 2015-16. Hence, it claimed that the pendency of the statutory appeal must not avert the taxpayer from invoking the writ jurisdiction.
For context, in a judgment dated May 8, 2024, concerning the taxpayer, the Delhi High Court examined whether an assessment could be conducted by an Assessing Officer who lacked jurisdiction over the case, in the absence of a transfer order under Section 127 of the Income Tax Act.
The Court held that if a case is transferred from the Assessing Officer having jurisdiction over the taxpayer to another Assessing Officer who lacked jurisdiction under Sections 120 and 124, a transfer order u/s 127 was mandatory. Without such an order, the other Assessing Officer could not be vested with the jurisdiction to pass an assessment order.
In that case, the assessment of the taxpayer had been centralised with the DCIT, Central Circle-16/20, New Delhi from AY 2008-09 onwards.
The court did not discover any valid decentralisation or Section 127 transfer order had been provided to prove the following transfer of the case to ITO Ward 21(1), New Delhi. On the ground of jurisdictional error, it quashed the assessment orders dated December 31, 2017, and September 30, 2021.
The HC in this case observed that the applicant had claimed the statutory remedy of appeal and therefore declined to exercise jurisdiction.
| Case Title | Raj Sheela Growth Fund Pvt Ltd v. Income Tax Officer |
| Case No. | W.P.(C) 13737/2026 |
| For Petitioner | Mr N.P. Sahni, Ms Ragini Handa, Mr Sameer Chopra |
| For Respondent | Mr Ruchir Bhatia, Mr Anant Mann, Mr Pratyuksh Gupta |
| Delhi High Court | Read Order |