

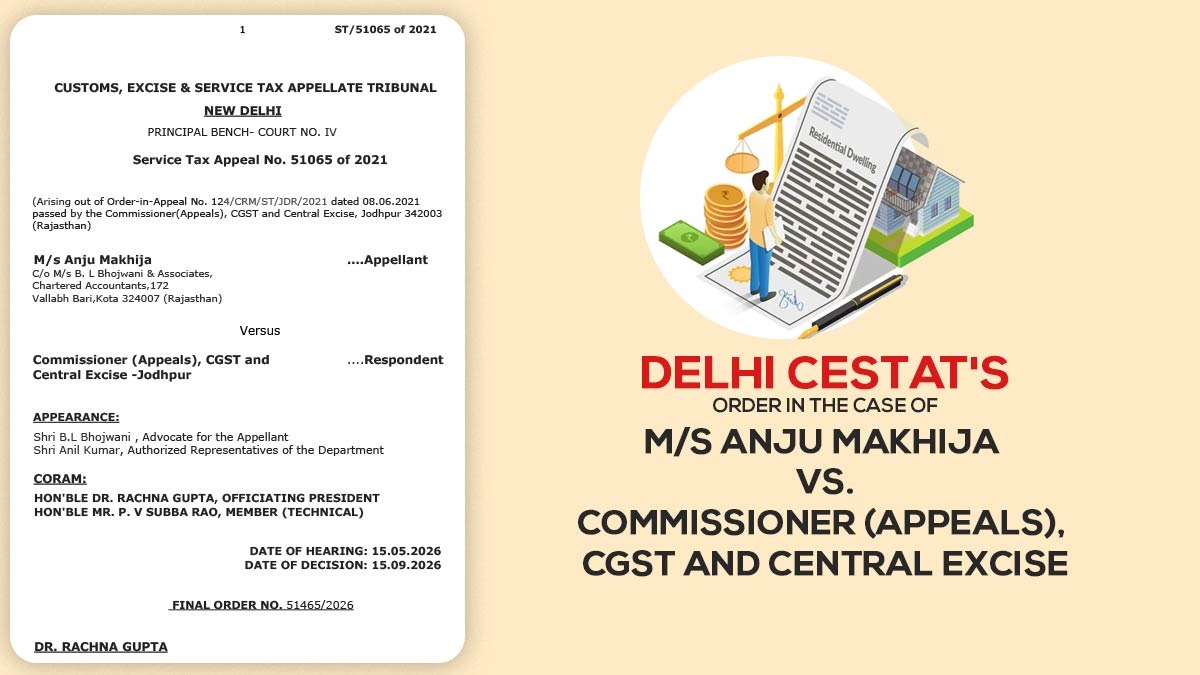
The Delhi Bench of the Customs, Excise and Service Tax Appellate Tribunal (CESTAT) held that a hostel utilised for residential purposes qualifies as a residential dwelling.
Consequently, the tribunal ruled that rental income derived from leasing such property was exempt from service tax during the negative-list regime.
The proceedings against Anju Makhija (appellant) have arisen from third-party information obtained from the Income Tax Department.
As per ITR and Form 26AS data, the department considered her receipts as consideration for taxable services and issued a show cause notice (SCN) demanding Rs 19,72,702 in service tax along with interest and penalties.
Counsel for the appellant argued that a portion of the amount was derived from the rental of immovable properties used for residential purposes and specifically informed the department that the property had been rented out for use as a hostel.
The appellant further contended that the rental of residential property for residential use does not fall within the ambit of service tax.
The counsel for the appellant said that the department had proceeded on ITR and Form 26AS numbers without finding out the type of the receipts. The appellant has given written replies and supporting documents, but those submissions were not regarded by the lower authorities.
The counsel for the revenue has mentioned that the appellant did not furnish adequate documentary evidence, especially the related rental agreements, to specify that the properties were rented for residential use.
They stated that the passbooks and chart prepared by the appellant were insufficient to establish the nature of the amounts received as rent.
The two-member bench, Dr Rachna Gupta (Officiating President) and P.V. Subba Rao (Technical Member), said that the Finance Act, 1994 did not specify the expression “residential dwelling”.
The tribunal referenced the Bombay High Court ruling in Bandu Ravgi N vs Acharya Ratna Desh Bhushan Shikshan Prasark Mandal, Kolapur, which explained “hostel qualifies to be called as residential dwelling as it is nothing but a house of residents for the students for a comparatively longer period as compared to the stay in hostel, motel etc.”
Read Also: CESTAT: Rent Paid to Directors Exempt from Service Tax Under RCM
The tribunal said that Section 66D(m) does not include services via renting a residential dwelling for use as a residence from taxable services.
It mentioned that the rental income obtained by the appellant was not subject to tax. The impugned order was quashed, and the appeal was permitted.
| Case Title | M/s Anju Makhija Vs Commissioner (Appeals), CGST and Central Excise |
| Case No. | No. 51065 of 2021 |
| For the Appellant | Shri B.L Bhojwani |
| For the Representatives | Shri Anil Kumar |
| Delhi CESTAT | Read Order |