

The 57th GST Council, on 8 October 2026, has suggested rationalising the cancellation process in two phases. In the 1st phase, the system should automatically accept applications in FORM GST REG-16 once all pending returns are submitted and all dues are paid, where (i) the taxpayer has not passed on ITC surpassing Rs 2.5 lakh in any month since registration, or (ii) the taxpayer has passed on ITC exceeding Rs 2.5 lakh in a month but has filed the final return in FORM GSTR-10 within the stipulated time. In phase 2, all applications should be accepted automatically, with FORM GST REG-16 amended to capture GSTR-10 details in the application itself.
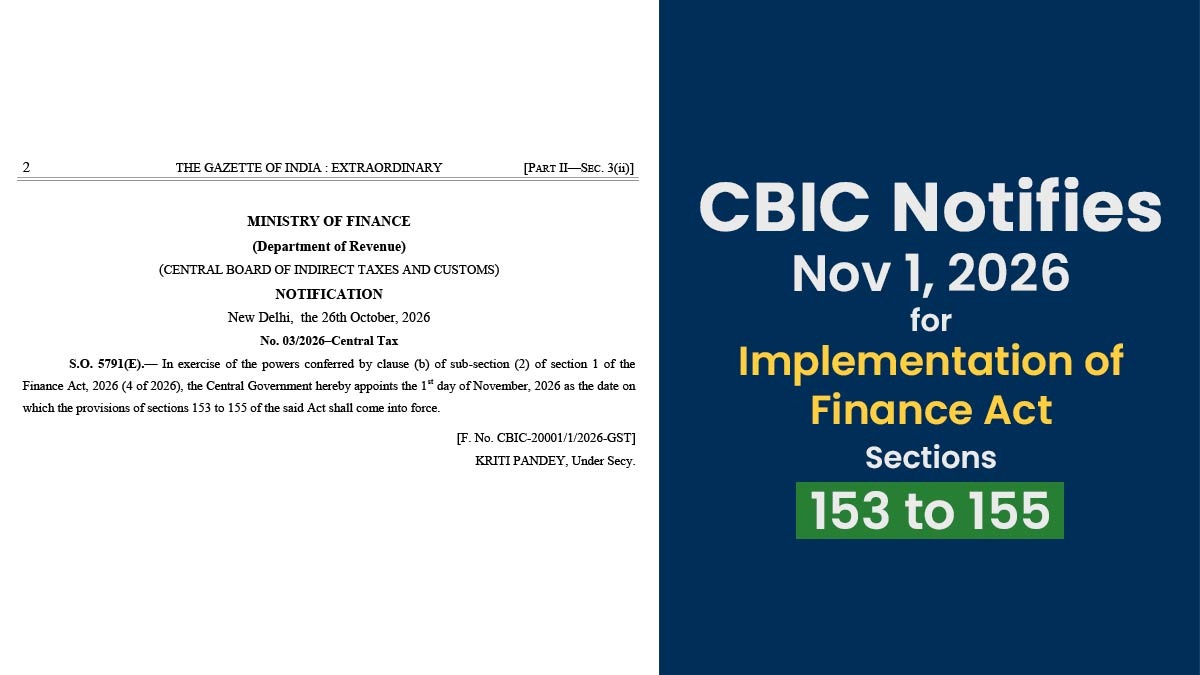
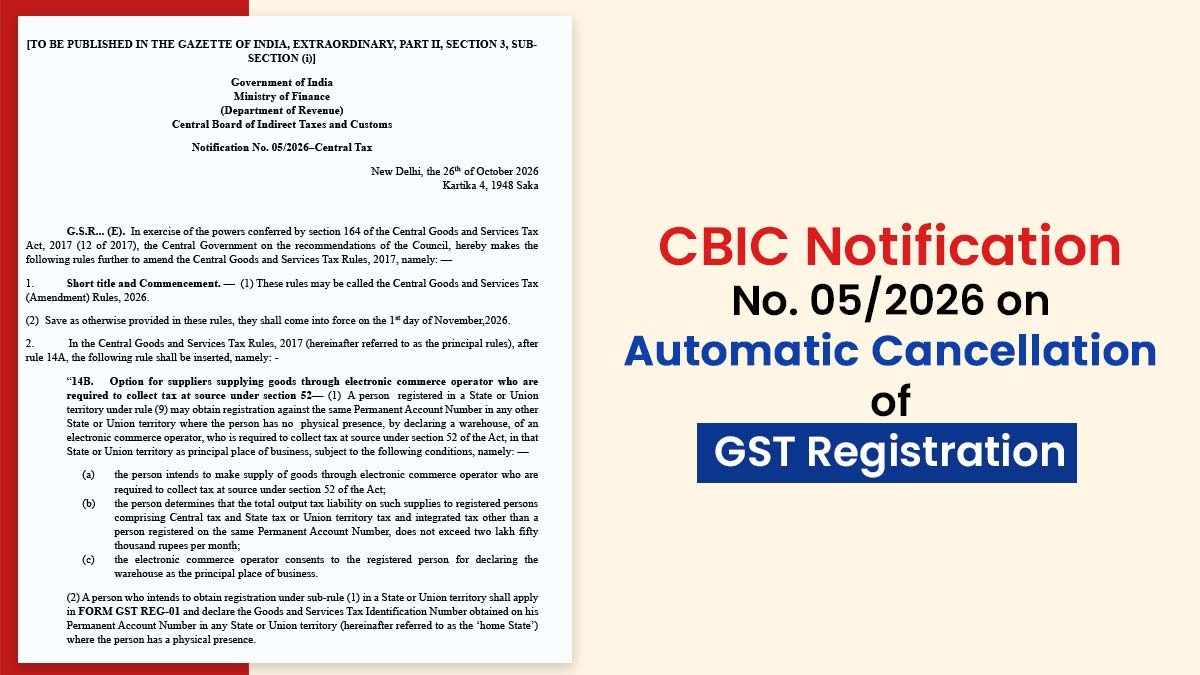
The complete notification:-
Now, the CBIC, vide Notification No. 05/2026-Central Tax dated 26.10.2026, has superseded Rule 20 of the CGST Rules, 2017 (titled “Cancellation of registration on request of taxpayer”) with effect from 01.11.2026, implementing Phase 1. The replaced rule provides as follows:
Application [Rule 20(1)]: An application in Form GST REG-16 must be filed within 30 days of the event that necessitates the cancellation. This application must include details regarding inputs held in stock, inputs contained in semi-finished or finished goods, and capital goods held in stock. Additionally, it must provide information on the tax liability arising from these items, payments made, and the relevant supporting documents. The 30-day time limit is not applicable in the case of the death of a sole proprietor.
Pre-conditions for filing [Rule 20(2)]: No application can be filed unless (a) all returns, including, where applicable, the details in Form GST CMP-08 have been filed for the periods ending up to the date from which the cancellation of registration is requested; and (b) if Form GSTR-1/IFF has been filed for any tax period, then Form GSTR-3B for that same tax period has also been filed.
Returns for the residual period and suspension [Rule 20(3) and (4)]: Returns for the period remaining up to the date of the application or the date from which cancellation is requested should be filed by their respective due dates. From the time the application is submitted until the proceedings are concluded, the registration shall be considered suspended.
Automatic cancellation by the portal [Rule 20(5)]: If the returns have been submitted on time and the tax, interest, fees, penalties, or any other dues have been paid, the registration will be canceled electronically by the common portal from the requested date, provided one of the following conditions is met: (a) The output tax liability (CGST, SGST/UTGST, IGST, and cess) reported in FORM GSTR-1/1A/IFF on supplies to registered persons did not exceed ₹2.5 lakh in any month from the date of registration until the date of application, or (b) The registered person has filed FORM GSTR-10 within three days of the due date for submitting the returns mentioned in sub-rule (3). This cancellation will be communicated through the new FORM GST REG-38.
Official route for other cases [Rule 20(6) to (12)]: If there are pending returns or unpaid dues, the application will be forwarded to the proper officer. The officer must take action within 15 days by either cancelling the registration using FORM GST REG-19 or issuing a deficiency notice via FORM GST REG-03. The applicant has 15 days to respond using FORM GST REG-04.
The officer is then required to either approve the application (FORM GST REG-19) or reject it (FORM GST REG-05) within another 15 days. If the applicant fails to respond, it will result in a deemed rejection, communicated through FORM GST REG-05A. If the officer does not act within 15 days of receiving the application or the applicant’s reply, the application will be deemed approved and notified with FORM GST REG-19.
Lawful heirs [Rule 20(13)]: The rule applies mutatis mutandis to legal heirs of a deceased proprietor.
Change in sufficient date of revocation[Rule 20(14) to (20)]: In cases where the officer believes that the effective date of cancellation should be changed to an earlier date, as per Section 29(3), a show cause notice must be issued using the new FORM GST REG-34. The applicant must reply within 30 days using FORM GST REG-35.
The officer will then issue either an order dropping the proceedings (FORM GST REG-36) or an order changing the effective date (FORM GST REG-37) within 30 days of the reply or within 60 days of the notice if no reply is received. If no order is made within 60 days of the notice, the proceedings are considered dropped (FORM GST REG-36). Once the effective date is changed, it cannot be altered again.
Significant modifications: FORM GST REG-16 has been revised wef 01.12.2026 to rationalise the reasons for cancellation (e.g., “no longer liable to be registered under Section 22 or 24, or opting out of voluntary registration under Section 25(3)”, “transfer of business on account of death of the proprietor”, “transfer of business for any other reason including amalgamation, demerger or other disposal”), to insert an option to file a NIL return for the period after the last return filed up to the date of cancellation, and to recast the tables for stock and ITC reversal.
Rule 44 has also been amended from 01.12.2026 so that the GST ITC reversal on inputs/capital goods in stock is determined and provided in FORM GST REG-16 (in addition to FORM GST ITC-03), and the reference to Section 29(5) in Rule 44(1) has been omitted.
From 1st November, 2026, the substituted Rule 20 and new FORM GST REG-38 will come into force. From 1st December, 2026, the amendments to FORM GST REG-16 and Rule 44 will come into force.
It is important to note that sub-rules (14) to (20) of Rule 20 will come into effect on November 1, 2026. Meanwhile, the corresponding FORMS GST REG-34 to REG-37 will be effective starting April 1, 2027.
Taxpayers intending to surrender their registration should ensure that all returns, including GSTR-3B for each period during which GSTR-1/IFF has been filed, are submitted and all dues are paid before applying. This will ensure that the application is processed automatically by the portal.
Read CBIC Notification No. 05/2026