

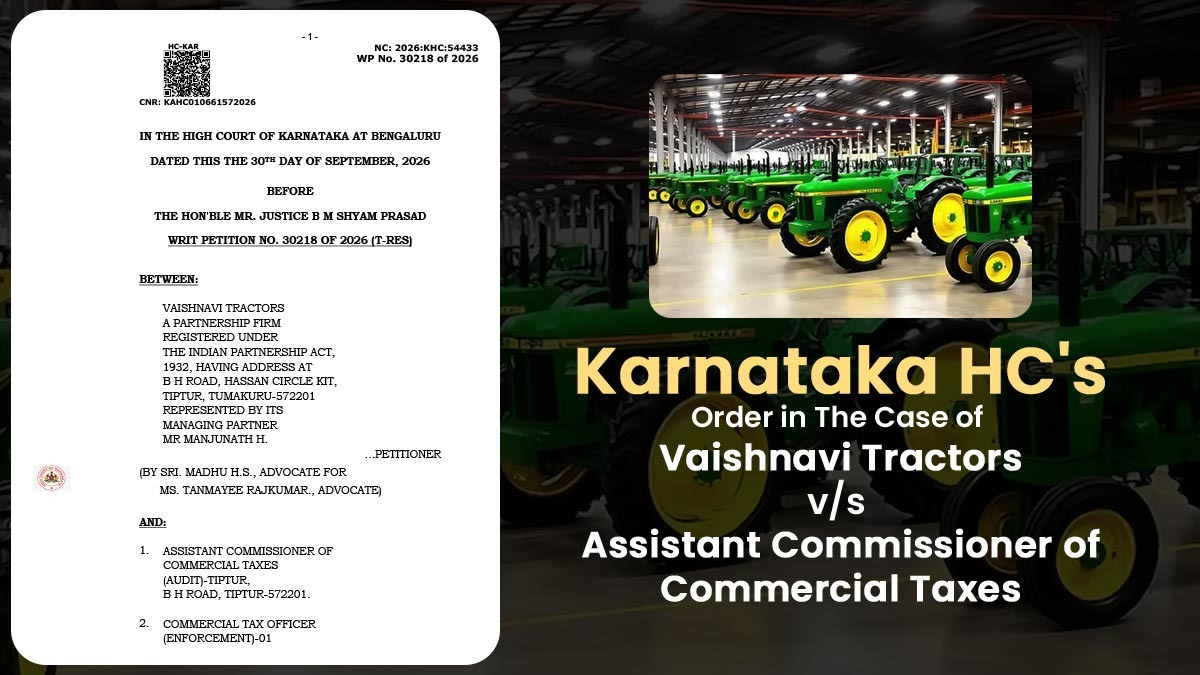
The Karnataka High Court permitted Vaishnavi Tractors, a family-run tractor dealership, another chance to specify the genuineness of its transactions after finding sufficient bona fides in its explanation for not responding to the show cause notice (SCN).
Justice B.M. Shyam Prasad has said that if a taxpayer fails to respond to GST proceedings due to a misunderstanding, specifically, the belief that matters pertaining to the relevant tax period had already been settled by the authorities, then such proceedings may be restored. The bench observed:
“The petitioner’s bona fides are considered in the amalgam of the afore two sets of circumstances. If the petitioner, who did not have the assistance of dedicated or specialised tax personnel, has not participated in the proceedings under a mistaken belief that the subject Show Cause Notice relating to the tax period which is already seized of by the authorities and which now stand dropped, this Court is of the view that bona fides are brought out justifying an interference for restoration.”
Vaishnavi Tractors challenged an adjudication order dated December 22, 2025, passed by the authorities u/s 73 of the GST Act for the financial year 2021-22.
Additionally, they challenged the summary of the order issued in Form GST DRC-07 on December 23, 2025, as well as a garnishee notice issued in Form GST DRC-13 on September 9, 2026.
The dispute arose from an allegation that the dealership had failed to reverse the Input Tax Credit (ITC) for the credit notes issued via the tractor manufacturer. The department asked to recover the tax liability, including interest and penalties.
This identical dispute had also arisen for the preceding financial years, from 2017-18 to 2020-21. The dealership cited a clarification dated March 7, 2019, which pertained to the reversal of Input Tax Credit (ITC) in instances where manufacturers issue credit notes.
The Court observed that the authorities had not accepted the dealership’s reliance on the clarification for FY 2017-18 and had dismissed its rectification application.
The dealership will need to file a statutory first appeal against this rejection. However, the authorities accepted the dealership’s arguments supported by clarifications for the financial years 2019-20 and 2020-21, and concluded the proceedings for those years.
For the financial year 2021-22, the dealership neither responded to the intimation provided in Form GST DRC-01A nor to the ‘show cause notice’ issued in Form GST DRC-01.
The family-run dealership stated that they did not have any staff members with expertise in tax matters. Consequently, they mistakenly assumed that these notices pertained to previous years (FY 2019-20 and FY 2020-21) cases that had either already been concluded or were already under appeal. Due to this misunderstanding, they missed the opportunity to respond to these notices.
Accepting this clarification as valid, the High Court set aside the adjudication order and restored the proceedings subject to the condition that the dealership deposits 10% of the demanded tax by November 30, 2026.
Read Also: Karnataka HC Sets Aside GST Registration Cancellation Due to Taxpayer’s Judicial Custody
The dealership is required to submit its supporting documents by December 11, 2026, following which the authorities have been directed to review these documents and pass a reasoned order.
| Case Title | Vaishnavi Tractors vs. Assistant Commissioner of Commercial Taxes |
| Case No. | WP NO. 30218 OF 2026 (T-RES) |
| For the Petitioner | Madhu H.S., and Tanmayee Rajkumar |
| For the Respondent | Jyothi M. Maradi |
| Karnataka High Court | Read Order |