

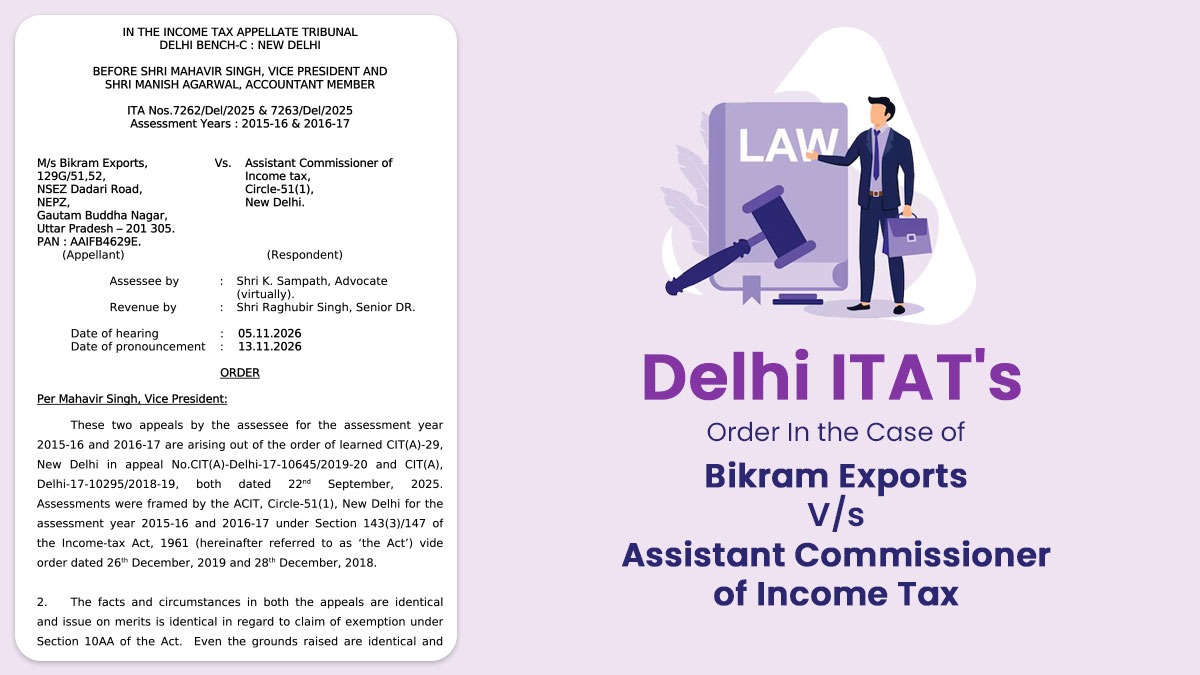
The ITAT Delhi Bench permitted the appeal of a jewellery manufacturer, stating that using hand tools, karigars, and contract labour rather than heavy machinery does not exempt tax on handmade jewellery. The tribunal stated that the taxpayer satisfied the provisions for a Section 10AA deduction at its Noida SEZ unit, as the law requires manufacturing or production but does not mandate the use of machinery.
The tribunal said that the operations performed by the karigars and contract labour inside the SEZ premises are specified as manufacturing by the unit itself. Earlier, the assessing officer refused M/s Bikram Exports’ Section 10AA exemption, even after its Rs 53 crore turnover at the Noida SEZ, citing minimal machinery (₹21,927), ₹4.94 crore in production expenses, and Section 194C TDS deductions as evidence of outsourcing. This disallowance was upheld by CIT(A), specifying subcontracting rules under Rule 41 of the SEZ Rules, 2006.
The taxpayer before the Tribunal has stated that it produced handmade jewellery inside the SEZ using hand tools, karigars, and contract labour, claiming that the absence of heavy machinery does not rule out manufacturing. It was stated that customers’ proprietary designs cannot be disclosed without their consent, and it was also noted that the corresponding account records have not been rejected.
Accepting these arguments, the Tribunal said that the use of machinery is not mandatory under Section 10AA. Furthermore, the engagement of skilled workers within a Special Economic Zone (SEZ) cannot be classified as ‘external outsourcing ‘, especially given that the movement of goods took place under the supervision of the Customs Department, and all records from the procurement of gold to the final export were duly submitted.
“Neither man nor material can enter or exit the SEZ without the approval and attestation of the customs authorities posted at the entry and exit gates of the SEZ. Therefore, the ‘inescapable conclusion’ as stated to have been arrived at by the Assessing Officer ‘that the production activity is not conducted in-house by the Assessee firm at its unit in Noida’ is erroneous”, it stated.
The Tribunal accepted the taxpayer’s explanation for the confidentiality of foreign customers’ designs and observed that common designs and templates had been produced before the authorities. It stated that the taxpayer had performed export transactions and received the corresponding export proceeds.
Also Read: Calcutta HC: An Explanation to I-T Section 10AA(1) is Constitutionally Valid Added by Finance Act
Therefore, the Tribunal stated that the disallowance of the exemption u/s 10AA was not justified and asked that the exemption be permitted for the relevant assessment years.
“… the Assessing Officer records that the assessee had carried out huge exports to the tune of Rs. 253 crores. In fact, the exports were only to the tune of Rs. 53 crores as elsewhere mentioned by the Assessing Officer herself in the impugned order. In view of the above, the claim of the assessee for exemption under Section 10AA of the Act is allowed”, it stated.
For Assessment Year 2016-17, the Tribunal allowed the assessee’s claim for bonus expenditure of ₹16,13,250. The authorities observed a difference between the amount of ₹16,11,450 shown in the tax audit report and the amount of ₹16,13,250 supported by the documents provided by the taxpayer.
The tribunal treated a minor ₹2,000 difference with the tax audit report as a clerical error since the supporting documents were valid. Both appeals were allowed.
| Case Title | Bikram Exports Vs Assistant Commissioner of Income Tax |
| Case No. | ITA.No.7262 & 7263/Del/2025 |
| Assessee by | Shri K. Sampath |
| Revenue by | Shri Raghubir Singh |
| Delhi ITAT | Read Order |