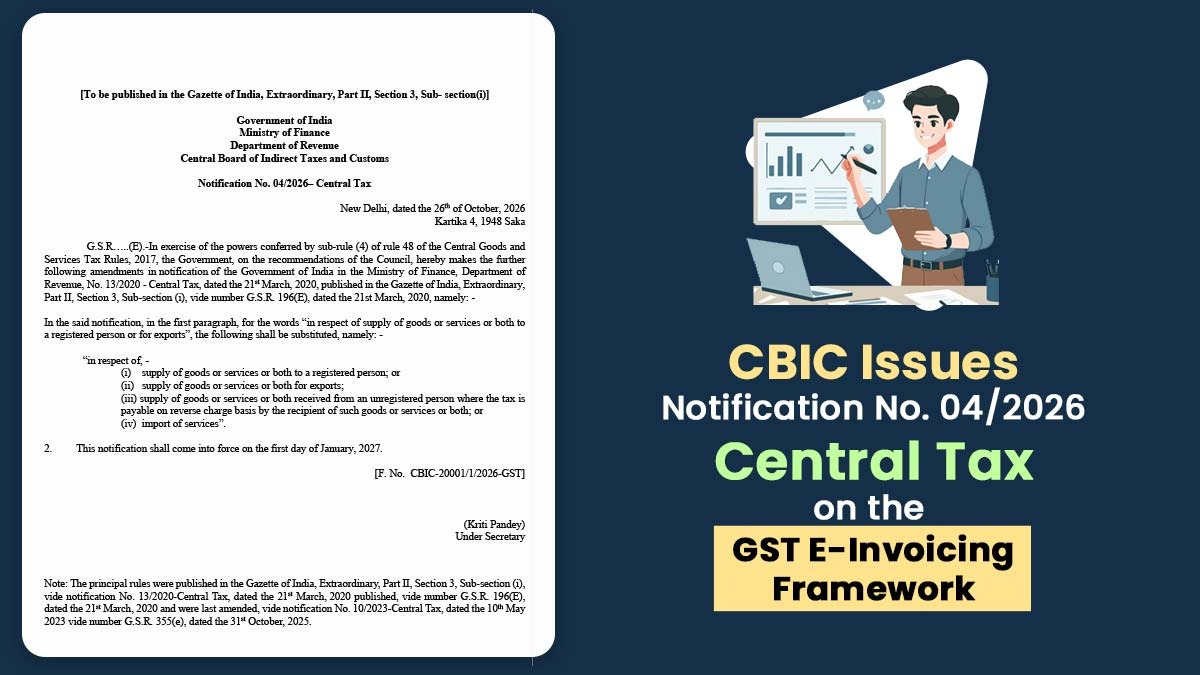


The 57th GST Council on October, 8, 2026, has suggested various process reforms such as automatic registration amendments and cancellations, the simplified registration scheme for e-commerce sellers, system-based refunds, an objection procedure against blocking of ITC, common standards for show cause notices and adjudication, and extension of e-invoicing to RCM supplies.
To implement these recommendations, several forms associated with the CGST Rules, 2017, needed to be changed. Consequently, under the ‘Central Goods and Services Tax (Amendment) Rules, 2026’, more than 40 forms have been modified, amended, or newly introduced, all of which will come into effect on various dates.
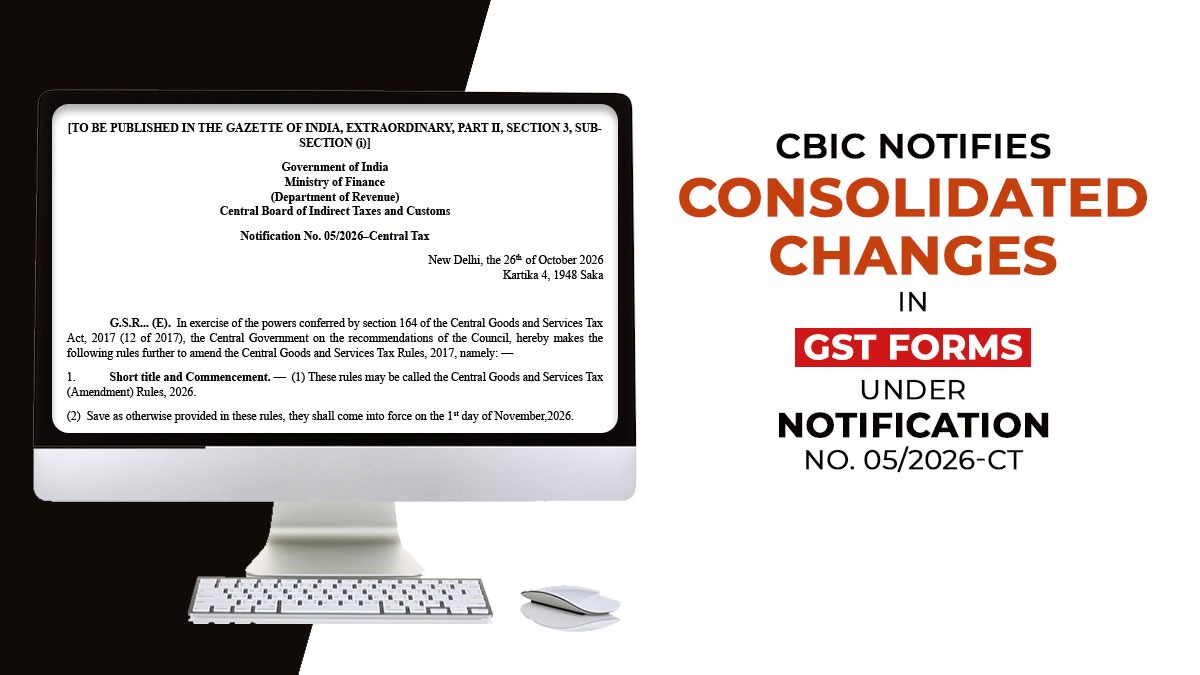
A complete CBIC notification:
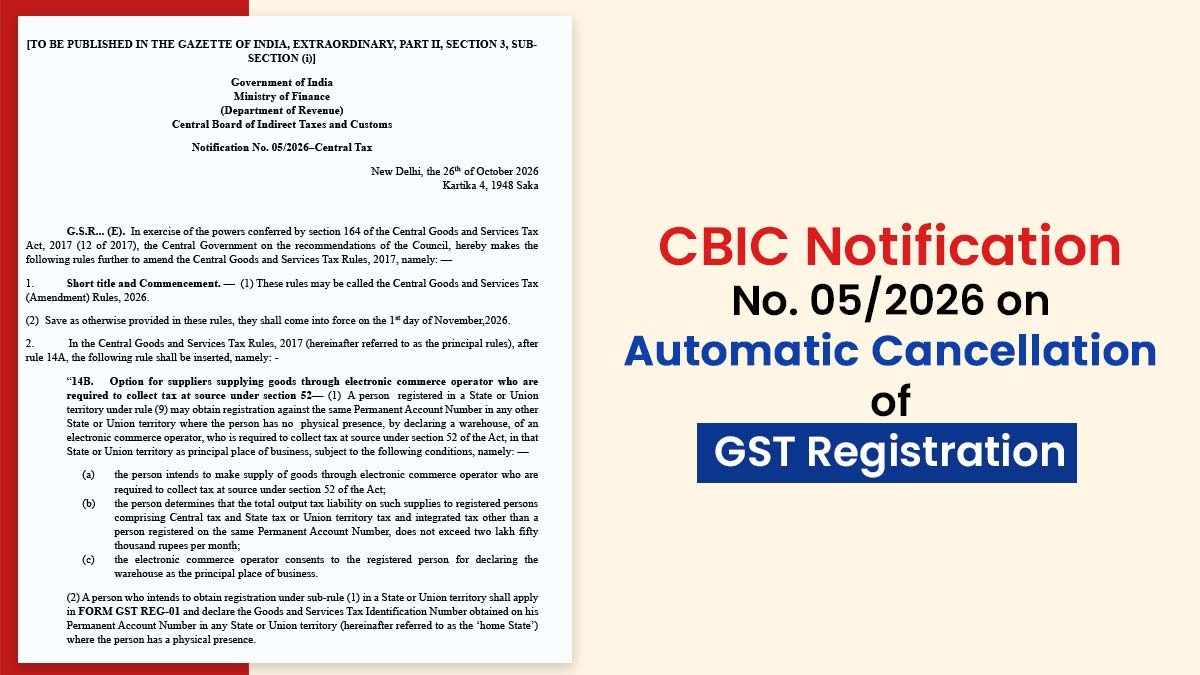
Now, the CBIC, vide Notification No. 05/2026-Central Tax dated 26.10.2026, has made the below-mentioned amendments to the forms (effective 01.11.2026 unless otherwise stated):
[A] Composition forms:
- Form GSTR-4: Table 5 substituted on the same lines as CMP-08 and new instructions 5A to 5C inserted; Form GSTR-4A updated for rule reference.
- Form GST CMP-02 and CMP-04- Table 5 (category of registered person) replaced to list (i) manufacturers other than notified goods, (ii) suppliers of restaurant/catering services under clause (b) of paragraph 6 of Schedule II, (iii) any other supplier eligible under Section 10(1), and persons eligible under Section 10(2A).
- Form GST CMP-08- Table 3 substituted to separately report outward supplies of goods, outward supplies of services (other than those made through an ECO liable under Section 9(5)), and outward supplies of services made via an ECO where the ECO is obligated to pay tax u/s 9(5); new norms 3A to 3C specify that composition taxpayers must pay tax on Section 9(5) supplies but should include them in aggregate turnover.
[B] Registration forms
- Form GST REG-03, REG-04, REG-05 and REG-15: The references within the rules have been updated in accordance with new Rules 19 and 20, as well as new Rule 14B.
- New Form GST REG-05A: Notification of ‘deemed rejection’ of an application (for registration, amendment, or cancellation), issued when the applicant fails to respond to a notice or fails the verification process.
- Form GST REG-14 substituted: Amendment application in registration/UIN/enrolment particulars, aligned with the substituted Rule 19 and the new Rule 83C.
- Form GST REG-01 substituted- It now directs to Rules 8(1), 9A, 14A and 14B; delivers options and declarations for registration under Rule 14A (field 4.1) and Rule 14B (field 4.2, with the home-State GSTIN); captures ECO GSTIN and legal name where the ECO warehouse is declared as principal place of business; adds “E-Commerce Operator’s Warehouse under Rule 14B” and co-working space as categories of possession of premises with the mentioned document lists; includes a new nature of business activity “supply of goods via electronic commerce operator under Rule 14B”; and mentions drop-down lists of documents to be uploaded, in line with Circular No. 257/03/2026-GST.
- Form GST REG-16 (w.e.f. 01.12.2026): The reasons for cancellation have been explained; a new option to file ‘NIL’ returns has been given for the period spanning from the date of the last filed return to the date from which the cancellation of registration has been requested; and the tables of stock, reversal of Input Tax Credit (ITC), and tax payable have been restructured.
- Form GST REG-17 substituted, REG-18, REG-19, REG-20 and REG-22 amended, and REG-31 substituted – These will be effective from 01.04.2027, to align with the substituted Rules 21A, 22 and 23A (system-based suspension, cancellation and revocation).
- Form GST REG-32 and REG-33 substituted: Application to opt out under Rule 14A or Rule 14B, and the order related thereto.
New Forms GST REG-34 (show cause notice for change in effective date of cancellation), REG-35 (reply), REG-36 (order dropping proceedings) and REG-37 (order changing effective date) – w.e.f. 01.04.2027, as mentioned in the Notification, and new Form GST REG-38 (intimation of cancellation of registration by the common portal).
[C] Return forms
- Form GSTR-6 – Tables 7 and 11 omitted; instructions on same-period distribution deleted; Form GSTR-6A updated to serve as the auto-drafted statement for the ISD under Rule 60(2).
- Form GSTR-3B – Rule reference changed from Rule 61(5) to Rule 61(1).
- Form GSTR-5 – Instructions revised to reflect the deadline of the 13th of the succeeding month.
- Form GSTR-7A (w.e.f. 01.01.2027) – Table 7 (details of supplies and amount of tax deducted) substituted to capture invoice/document number, date and value along with the amount paid to the deductee liable for TDS and tax deducted under IGST, CGST and SGST/UTGST.
- Form GSTR-9 and 9C – Instructions amended to extend the reporting relaxations/options available for FY 2023-24 and FY 2024-25 (Tables 5D–5F, 5H–5K, 6B–6D, 15, 16, 17 and 18 of GSTR-9 and Tables 5B–5N and 14 of GSTR-9C) to “FY 25-26 onwards”, giving continuity to the easier annual return reporting.
[D] Refund forms
- Form GST RFD-01 substituted (w.e.f. 01.12.2026) – Statements and declarations will be recorded in a structured, system-readable format, eliminating the need to upload scanned documents for claims related to ‘zero-rated’ supplies and ‘inverted duty structure‘. Additionally, this will include new statements for merchant-export supplies and Input Tax Credit (ITC) details, as well as a declaration concerning exemption from prosecution in cases involving tax evasion of more than Rs 2.5 crore.
- Form GST RFD-07 – rule reference rationalised to Rule 92(2).
[E] Demand and recovery forms
- Form GST DRC-01 substituted (w.e.f. 01.04.2027): The summary of the show cause notice now requires the selection of the proceeding under which the notice is issued. This includes options from Annexure A, such as mismatch under Rule 88D, assessment, scrutiny, audit, erroneous refund, investigation, and other relevant categories based on prior intimations, notices, or reports. In addition, the grounds for demand must be chosen from a standard list in Annexure B, which includes misclassification, incorrect claim of concessional notifications, RCM liability, composition, valuation, nature of supply, time of supply, interest, late fees, undeclared supply, ITC issues, erroneous refund, and TDS/TCS. Furthermore, a tabular statement is required, detailing tax, interest, penalties, and other dues categorised by tax period, rate, and place of supply.
- Form GST DRC-01A amended (w.e.f. 01.04.2027) – Pre-notice intimation to likewise specify the proceeding (Annexure A) and grounds (Annexure B).
- Form GST DRC-07 amended (w.e.f. 01.04.2027) – Order summary to carry the SCN number and date as new serial number 1.
- Form GST DRC-22 – Split into Part A (order of provisional attachment) and Part B (order rejecting objection) under Rule 159.
The New Forms GST DRC-26 (order restricting debit from electronic credit ledger under Rule 86A), DRC-27 (objection against such order) and DRC-28 (order on the objection: Part A allowing, Part B rejecting) – w.e.f. 01.04.2027.
[F] E-invoice schema
- Form GST INV-01 (w.e.f. 01.01.2027) – The schema has been upgraded to Version 1.2. The supply type codes now include RCMDOM (domestic supply from an unregistered person under Reverse Charge Mechanism) and RCMIMP (import of services). In addition to these, the existing codes B2B, B2C, SEZWP, SEZWOP, EXPWP, EXPWOP, DEXP, SEZWPA, and SEZWPNA remain valid. This change follows the extension of e-invoicing as outlined in Notification No. 04/2026-Central Tax.
Useful date: The amendments in this form will be effective from 1st November 2026, unless otherwise indicated above. From 1st December 2026, the amendments to Form GST REG-16 and Form GST RFD-01 will be applicable, Form GSTR-7A and Form GST INV-01 from 1st January, 2027; and the forms linked to the revised suspension/cancellation mechanism, Rule 86A and the standardised show cause notice format (REG-17, REG-18, REG-19, REG-20, REG-22, REG-31, REG-34 to REG-37, DRC-01, DRC-01A, DRC-07, DRC-26 to DRC-28) from 1st April, 2027. Taxpayers and professionals must update their compliance templates and software as per that.
Read Notification