

The Himachal Pradesh High Court has stated that a reassessment notice issued by a jurisdictional Assessing Officer rather than through an automated, ‘faceless’ allocation process u/s 148 of the Income Tax Act, 1961, constitutes a breach of the ‘E-Assessment of Income Escaping Assessment Scheme, 2022’.
A division bench of Justice Ajay Mohan Goel and Justice Yogesh Jaswal upheld the Income Tax Appellate Tribunal’s (ITAT) decision to set aside the reassessment proceedings against Pooja Aggarwal.
The court stated that the notifications pertaining to reassessment proceedings explicitly mandate that notices under section 148 must be issued through an automated allocation process and in a ‘faceless’ manner.
“In terms of this notification, which is statutory in nature, as the E-Assessment of Income Escaping Assessment Scheme, 2022 was notified by the Central Government, in exercise of powers conferred by sub-sections (1) and (2) of Section 151-A of the Income Tax Act, 1961, issuance of notice under Section 148 of the Income Tax Act, has to be through automated allocation, in accordance with risk management strategy formulated by the Board, as referred to in Section 148 of the Act for issuance of notice and in a faceless manner, to the extent provided in Section 144B of the Act with reference to making assessment or reassessment of total income or loss of assesse.
Thus, the notification is unambiguous and clear that the notice under Section 148 has to be issued through automated allocation and in a faceless manner.”
On December 29, 2023, the Income Tax Department issued a notice to Agarwal, proposing the reopening of his assessment. This notice, issued by the concerned Assessing Officer in Shimla, was challenged before the ITAT because it violated Section 151A and Notification No. 18/2022.
The tribunal set aside the assessment. The department argued in its appeal that the notice was valid and that it was not mandatory for it to be issued through the ‘faceless’ system. The High Court reviewed the 2022 scheme notified u/s 151A.
Clause 3 of this scheme provides that the processes for assessment, re-assessment, and re-computation under Section 147, as well as the issuance of notices u/s 148, must be carried out through an automated allocation mechanism, in accordance with the risk management strategy formulated by the Central Board of Direct Taxes (CBDT). Furthermore, under Section 144B, this entire process must be conducted in a ‘faceless’ manner.
While applying this condition, the Bench observed that the notice was issued by the Assessing Officer (AO) having the relevant jurisdiction in Shimla, rather than through an automated system in a ‘faceless’ manner.
“This demonstrates that the notice in the present case was not issued through automated allocation in a faceless manner, but was issued in contravention of Clause 3 of the E-Assessment of Income Escaping Assessment Scheme, 2022. This is exactly what has been held by the learned Tribunal,” the court stated.
Also Read: HP High Court Permits Fresh Challenge to Section 147A After SC Remand
Also, the bench observed that the department did not specify that the Tribunal’s findings were perverse or unsupported by the record. Holding that the notice breached Clause 3 of the 2022 Scheme, the High Court upheld the Tribunal’s decision to set aside the assessment order and dismissed the department’s appeal.
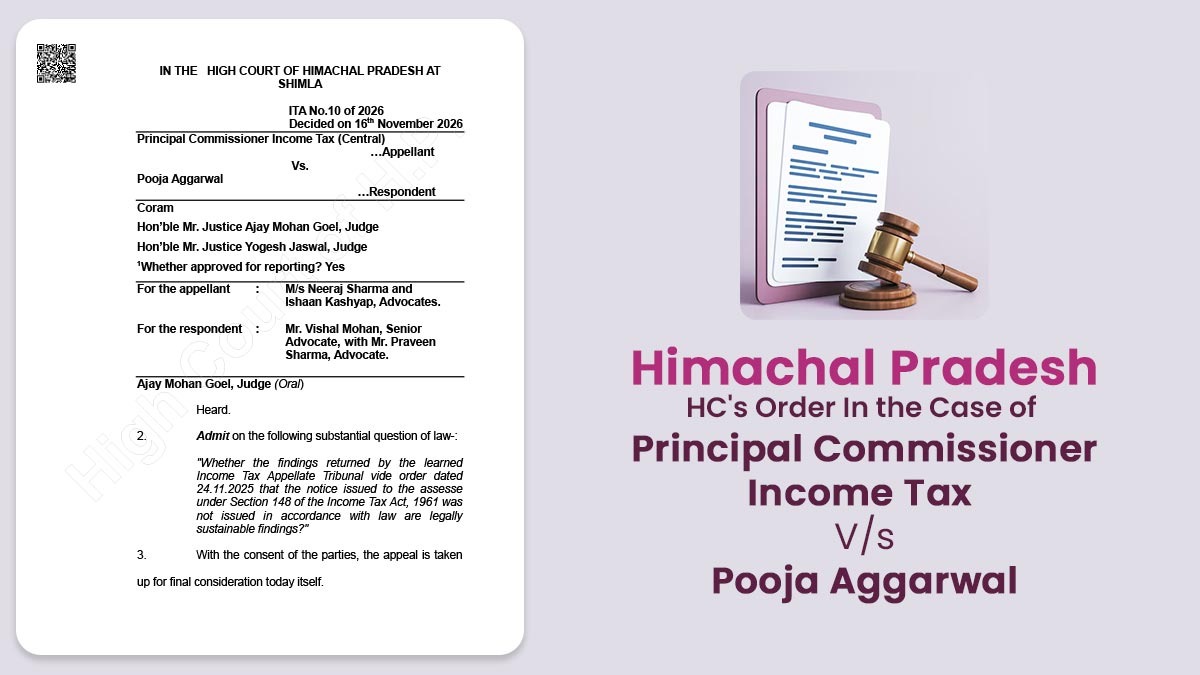
| Case Title | Principal Commissioner of Income Tax Vs Pooja Aggarwal |
| Case No. | ITA No.10 of 2026 |
| For the Appellant | M/s Neeraj Sharma, Ishaan Kashyap |
| For the Respondent | Mr Vishal Mohan, Mr Praveen Sharma |
| Himachal Pradesh High Court | Read Order |