

The Chennai Bench of the Income Tax Appellate Tribunal (ITAT) quashed the entire reassessment process because the Assessing Officer (AO) had not obtained the necessary approval for issuing a notice u/s 148.
This approval was required to be obtained from the authority specified under Section 151(ii) of the Income Tax Act; however, the three-year time limit from the end of the relevant assessment year had already elapsed.
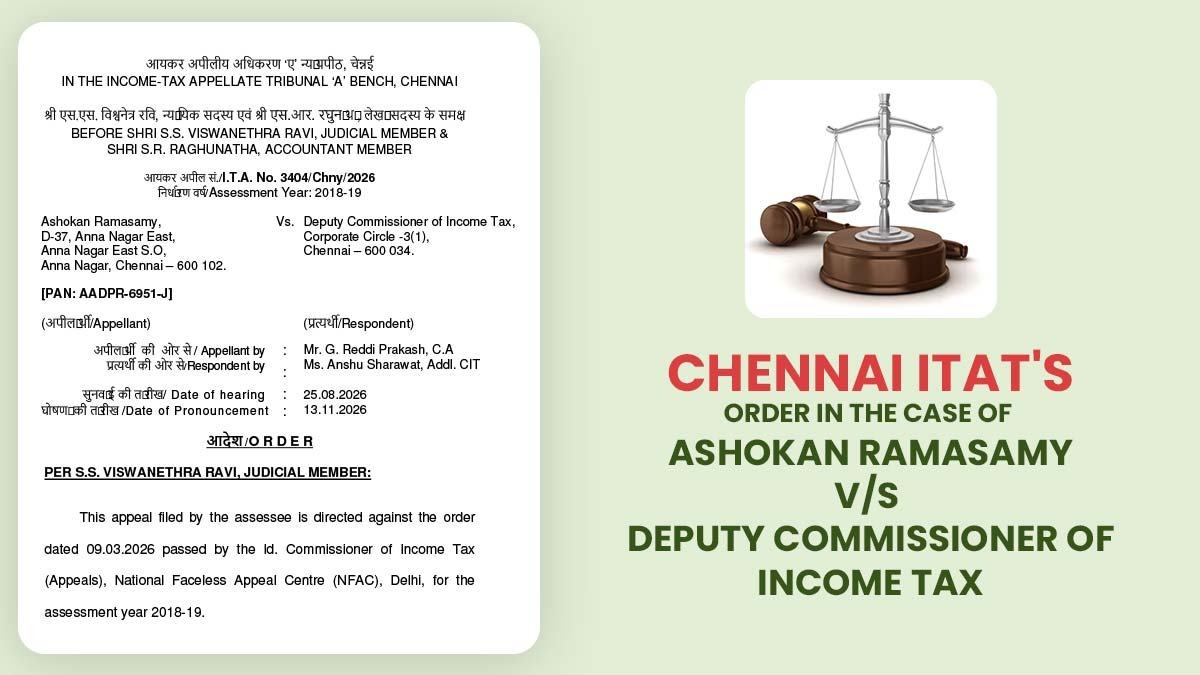
The current dispute involves Ashokan Ramasamy, who has contested an order issued on March 9, 2026, by the Commissioner of Income Tax (Appeals) [CIT(A)] at the National Faceless Appeal Centre (NFAC) in Delhi.
This pertains to the AY 2018-19. Ramasamy is appealing before the ITAT, Chennai Bench, arguing that the Assessing Officer (AO) issued a notice under Section 148 on April 6, 2022, after receiving approval from the Principal Commissioner of Income Tax (PCIT), Chennai-3.
Since the relevant assessment year ended on March 31, 2019, over three years had passed by the time the notice was issued. Thus, approval should ideally have been obtained from the Principal Chief Commissioner of Income Tax or another authority specified u/s 151(ii), instead of the Principal Commissioner.
Read Also: Madras HC: IT Notice U/S 148 Must Be Approved by Tax Authority After 3-Year Limitation Lapses
In support of this claim, the taxpayer cited an earlier judgment by the Madras High Court in the ‘Chokkalingam Thangavel’ case, which had addressed a similar issue.
The court clarified that once a period of more than three years has elapsed, obtaining approval from the authority specified under Section 151(ii) is mandatory. Failure to comply with this requirement renders the reassessment proceedings without jurisdiction.
The tribunal reviewed all relevant submissions and arguments and concluded that, in this case, the three years for issuing a notice under Section 148 had already expired.
Therefore, the Assessing Officer (AO) should have obtained the necessary approval from the Principal Chief Commissioner of Income Tax or another authority specified under Section 151(ii).
However, in this instance, the approval was obtained from the PCIT, which is legally invalid. As a result, the tribunal declared the notice dated April 6, 2022, invalid and set aside the subsequent reassessment order dated March 9, 2024.
| Case Title | Ashokan Ramasamy vs. Deputy Commissioner of Income Tax |
| Case No. | I.T.A. No. 3404/Chny/2026 |
| Appellant by | Mr G. Reddi Prakash |
| Respondent by | Ms. Anshu Sharawat |
| Chennai ITAT | Read Order |