

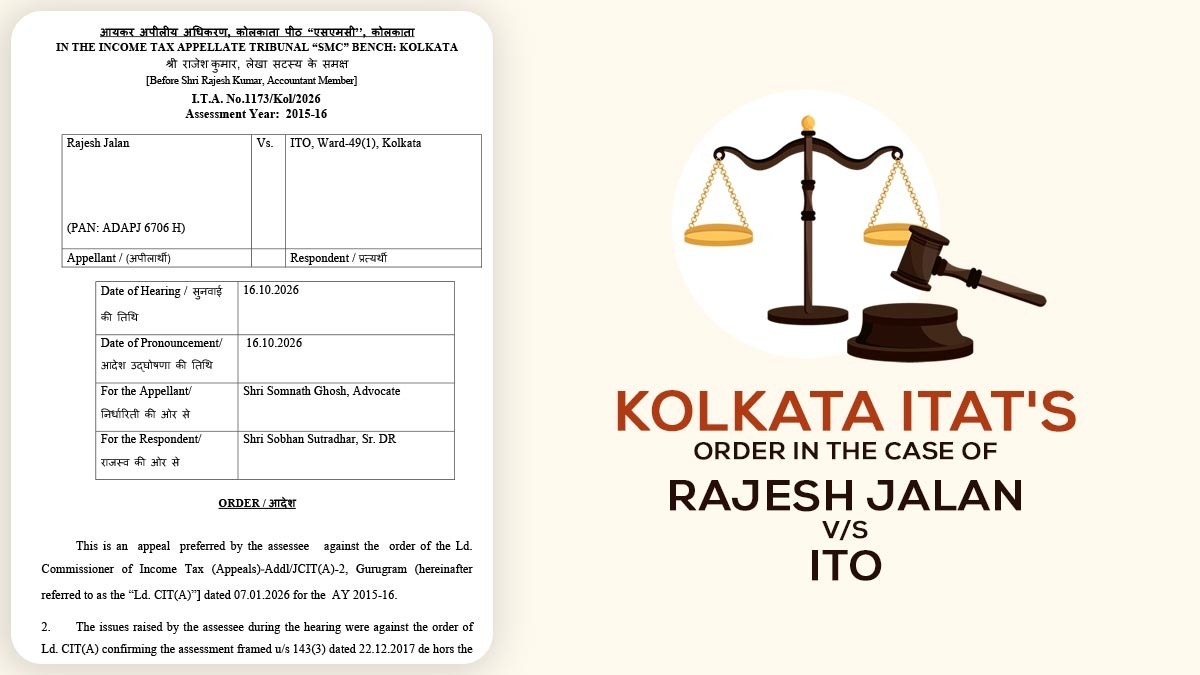
The ITAT Kolkata set aside the assessment order passed against Rajesh Jalan, holding that the taxpayer was not provided with the notice u/s 143(2) of the Income Tax Act, 1961. The Tribunal discovered that the assessment faced a jurisdictional defect related to the financial limits specified under the CBDT norms.
The taxpayer has submitted the ITR for the AY 2015-16, reporting an aggregate income of Rs 1.96 lakh. The assessing officer in the scrutiny has considered the long-term capital gains (LTCG) emerging from the sale of 4,000 equity shares of Jackson Investments Ltd. as fake, alleging that the share prices had been artificially surged through manipulation.
The AO has finished the assessment after the taxpayer’s income addition of LTCG. The dissatisfied taxpayer appealed to the Commissioner of Income Tax (Appeals) [CIT(A)], which upheld the impugned assessment.
The taxpayer before the Income Tax Appellate Tribunal (ITAT) claimed that the assessment was not valid because the notice under section 143(2), dated August 1, 2016, had been returned via the postal authorities with the remark “Left” on September 14, 2016. The records of the Revenue did not specify that the notice was later given to the taxpayer.
The tribunal observed that “notice in this case issued u/s 143(2) dated 1.08.2016 was returned by the postal authority with the postal comment “Left” on 14.09.2016 and thereafter the database was checked and did not find out how the notice was served on the assessee. The Ld. Counsel vehemently claimed before the Bench that this issuance of notice would not meet the requirement of good service and is not sufficient. Whereas the Act mandates the service of the notice on the assessee. Thus, in our opinion, the notice was not served at all.”
Subsequently, it noted that the notice u/s 143(2) had been issued via the Assistant Commissioner of Income Tax (ACIT), whereas the reported income of the taxpayer was less than Rs 15 lakh.
It stated that the action breached CBDT Circular No. 1/2011 dated January 31, 2011, which specifies the jurisdictional limits for non-corporate taxpayers.
Read Also: Delhi HC Sets Aside 153C Order, Finds Satisfaction Note Recorded Beyond Limitation Period
The Tribunal placed reliance on the decision of the Calcutta High Court in Kusum Goyal v. ITO and concluded that the assessment has jurisdictional issues.
The Tribunal stated that the proper service of this mandatory notice was crucial and that its non-service makes the assessment proceedings invalid. Therefore, the ITAT set aside the impugned assessment order dated December 22, 2017.
| Case Title | Rajesh Jalan Vs ITO |
| Case No. | I.T.A. No.1173/Kol/2026 |
| For Petitioner | Shri Somnath Ghosh |
| For Respondent | Shri Sobhan Sutradhar |
| ITAT Kolkata | Read Order |