

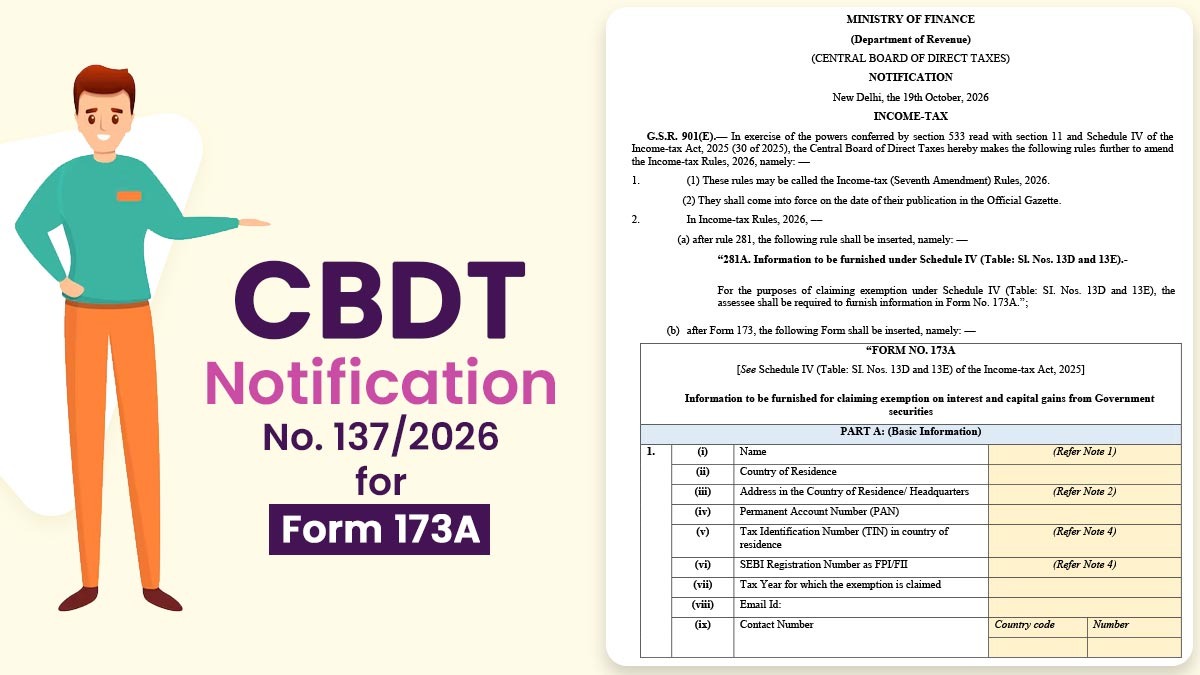
The Central Board of Direct Taxes (CBDT) has said that it is mandatory to provide data in a new Form 173A to claim income tax exemption on interest and capital gains from government securities.
The form has been added to the Income-tax Rules, 2026, through the Income-tax (Seventh Amendment) Rules, 2026, notified on October 19 under Notification No. 137/2026. The rules come into effect on the date of their publication in the Official Gazette.
The amendment introduces a new Rule 281A after Rule 281. It requires taxpayers to furnish the information in Form 173A to claim tax exemptions under Schedule IV (Table, Sl. Nos. 13D and 13E) of the Income-tax Act, 2025. The new form has been inserted immediately after Form 173.
Part A of the form seeks basic information. These are the name, country of residence, address in the country of residence or headquarters, Permanent Account Number (PAN), tax year for which the exemption is claimed, email address, and contact number.
It also seeks the Tax Identification Number (TIN) in the country of residence and the SEBI registration number as a foreign portfolio investor (FPI) or foreign institutional investor (FII). This information is optional for the Bank for International Settlements (BIS).
Part B of the form asks for the details of the exempt income claimed. The filer is required to provide the International Securities Identification Number (ISIN), the type of government security, and its tenor. The types listed are Treasury Bills, fixed-rate bonds, floating-rate bonds, State Development Loans (SDLs), and others.
Read Also: CBDT Notification No. 120/2026 Amends Registration Forms, Extends Deadline to March 31, 2027
The filer should provide the total value of securities held on April 1 and March 31, and the value of securities bought in the year. The form seeks the sale consideration of securities sold in the year, the gross interest received or accrued in the tax year, and the capital gains earned in the tax year.
Amounts should be filled in rupees unless otherwise provided. Part B can be repeated if needed. The form ends with a declaration, signed by the principal officer, that the details are correct to the best of the signatory’s knowledge and belief.
On April 1, 2026, the Income Tax Act 2025 came into effect. The Income-tax Rules, 2026 were published in the Gazette of India on March 20, 2026.
Entries 13D and 13E were added to Schedule IV via the Income-tax (Amendment) Ordinance, 2026, published on June 5. The ordinance came into force from April 1, 2026. Under these entries, any interest earned on government securities, as well as any capital gains arising from their sale, exchange, or transfer, are exempt from tax.
Entry 13D includes foreign institutional investors, as specified in section 210(6)(a) of the Income-tax Act, 2025. Entry 13E includes the Bank for International Settlements, the institution established at the Hague Conference and based in Basel, Switzerland.
The term ‘government security’ has the same meaning as assigned to it under Section 2(f) of the Government Securities Act, 2006. Form 173A now specifies the information that should be provided to claim the exemption under both entries.
Read CBDT Notification No. 137/2026