

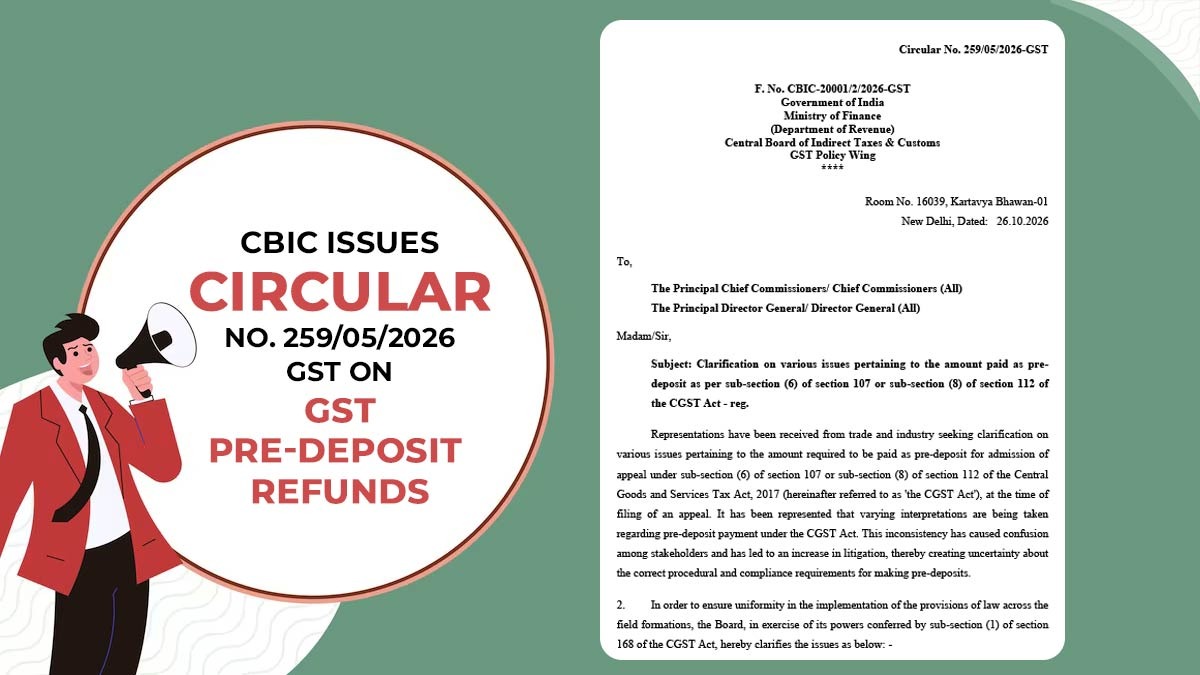
As per the Ministry of Finance (Department of Revenue), the Central Board of Indirect Taxes and Customs (CBIC) has issued a circular providing clarification on distinct problems of the amount paid as a pre-deposit under sub-section (6) of section 107 or sub-section (8) of section 112 of the CGST Act.
For an appeal filed under sub-section (6) of Section 107 or sub-section (8) of Section 112 of the Central Goods and Services Tax (CGST) Act, 2017, to be admitted, the payment of a pre-deposit amount is mandatory.
The Board has received several representations from the trade and industry sectors highlighting various issues related to this pre-deposit requirement.
The Board observed that there are distinct interpretations of the pre-deposit payment, which led to confusion among stakeholders. In conclusion, litigation has surged over time. Regarding pre-deposits, stakeholders are unsure about the correct procedural and compliance provisions.
Important: GSTAT: GST Portal Technical Errors Cannot Prejudice Taxpayer’s Statutory Right of Appeal
Consequently, to ensure the uniform application of Section 112 of the CGST Act, 2017 across all jurisdictions, the CBIC has issued a clarification, exercising its powers under sub-section (1) of Section 168 of the CGST Act.
Clarifying that the board has responded to 6 of the most common questions among stakeholders. One of the questions is, “When the Appellate Authority or Appellate Tribunal issues an order, should it be required to explicitly state that the pre-deposit paid by the appellant must be refunded?”
Read Also: GST Council Proposes Reduction of Pre-Deposit for Penalty Appeals U/S 107 & 112 from 25% to 10%
In response to this question, the CBIC has stated that when any amount paid by an appellant under sub-section (6) of Section 107 or sub-section (8) of Section 112 is required to be refunded as a result of an order passed by the Appellate Authority or the Appellate Tribunal.
The Board has stated that it is not always required to specify that the pre-deposit needs to be deposited in such an order.
CBIC mentioned that when the appellant obtains the order, he/she should submit the refund claim for the pre-deposit by submitting FORM GST RFD-01.