

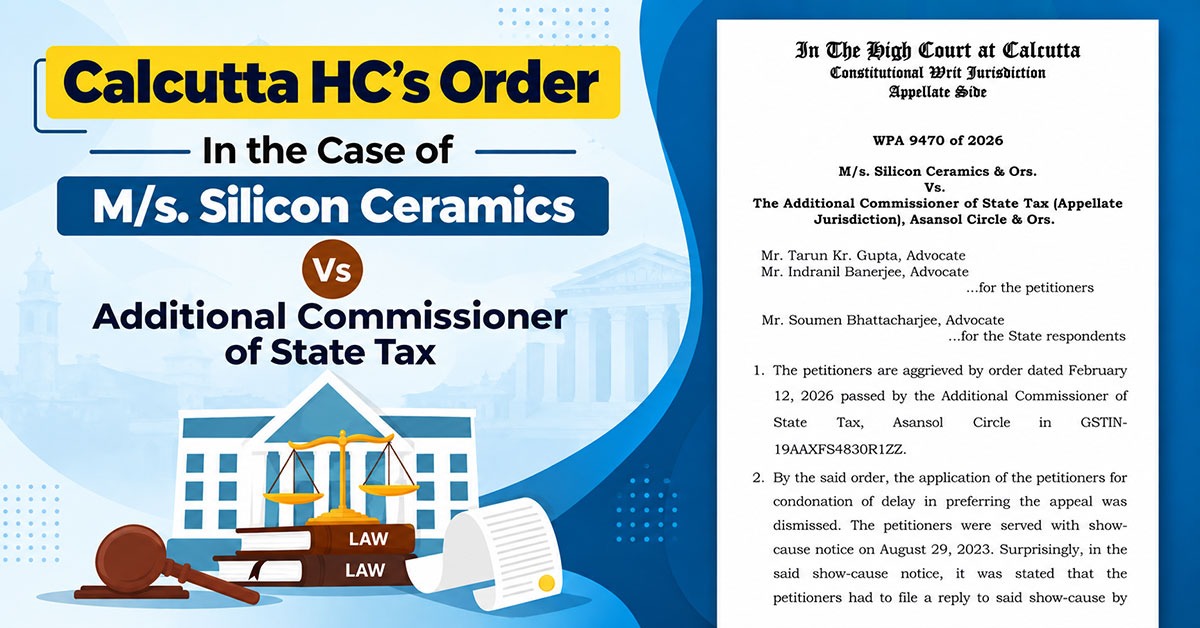
The Calcutta High Court set aside a goods and services tax (GST) order that was passed without furnishing an adequate chance to be heard, as the SCN was given via the additional notices portal.
The petitioners, M/s. Silicon Ceramics & Ors., submitted the writ petition and asked for condonation of delay in filing the appeal. However, the authorities rejected the petition, and a Show Cause Notice (SCN) was issued requiring them to give a response.
However, the columns for the date, time, and venue of the personal hearing in the notice stated “Not Applicable.” Subsequently, an ‘Order-in-Original’ was passed because the petitioner didn’t reply to the ‘show-cause notice.’
As the SCN was uploaded on the additional notices portal, it escaped their attention, the petitioners claimed. Upon subsequently becoming aware of the original order, the petitioners filed an application seeking condonation of the delay in filing the appeal. The authorities did not consider the application, prompting the petitioners to contest the order.
Counsel for the respondents argued that the petitioners’ application for condonation of delay was rejected because the authorities held the view that the time limit prescribed by law for filing an appeal could not be extended for the petitioners.
Justice Aryak Dutt said that “It is an admitted fact that the notices for show-cause had been served on the additional notices portal and therefore, it is possible that the petitioners may have overlooked such additional notices portal and did not get the opportunity to reply to the show-cause. Therefore, I set aside the order impugned dated February 12, 2026 and the order in original dated October 3, 2023, inasmuch as the same was passed without considering the contentions of the petitioners or the documents to be filed by them in support of such contentions.”
Also Read: How GST Software Fixes Common Mistakes in SCN Replies
The Court also clarified that while making the decision, the authorities would not consider the ground of ‘limitation’ to reject the petitioners’ arguments, and they must act strictly in accordance with the law. The petitioners were asked to respond to the SCN as well as furnish all the documents in support thereof within 4 weeks from the judgment date.
| Case Title | M/s. Silicon Ceramics Vs Additional Commissioner of State Tax |
| Case No. | WPA 9470 of 2026 |
| For Petitioner | Mr Tarun Kr. Gupta, Mr Indranil Banerjee |
| For Respondent | Mr Soumen Bhattacharjee |
| Calcutta High Court | Read Order |