

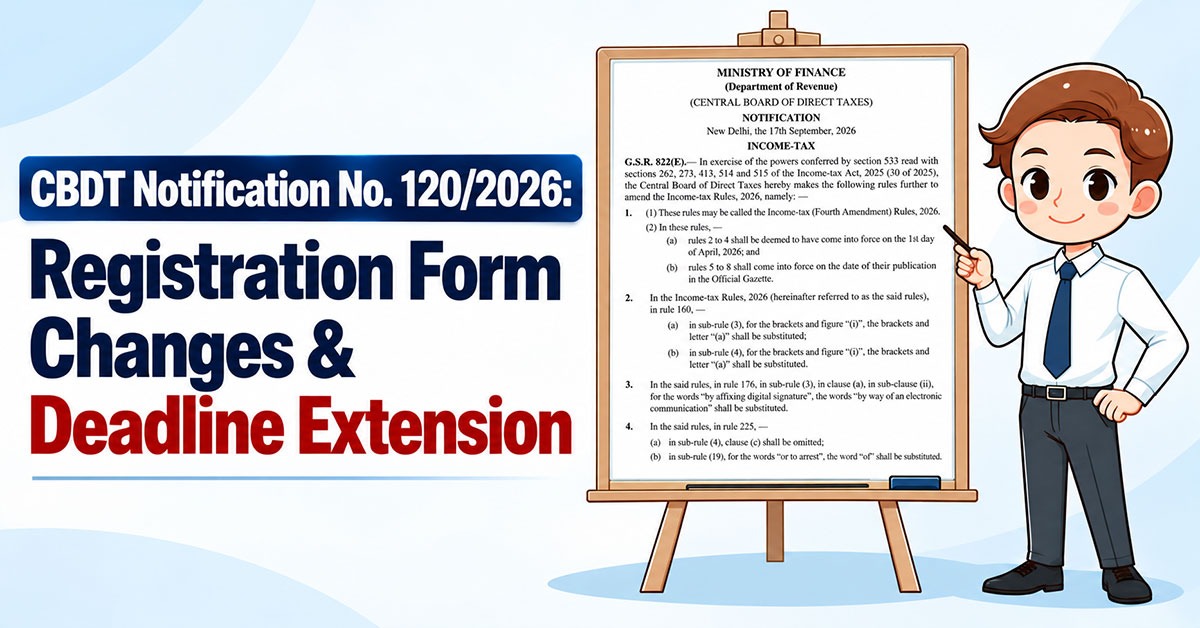
The Central Board of Direct Taxes (CBDT) has revised the forms used to register valuers and authorised income-tax practitioners under the Income-tax Act, 2025.
These changes have been announced via Notification No. 120/2026 dated September 17. The notification also extends the deadline for meeting mandatory registration requirements from September 30, 2026, to March 31, 2027.
Form 169: Registration for Valuers
Form 169 is for individuals applying for registration as a valuer under section 514 of the Income-tax Act 2025. In this form, applicants are asked to provide information such as their PAN, address, contact details, educational qualifications, professional qualifications, and work experience.
Applicants also have to specify the categories of assets for which they wish to register as valuers. These categories include assets such as immovable property, jewellery, plant and machinery, securities, and business assets. This form also seeks information from applicants regarding their evaluation experience, including details of relevant work undertaken over the past three years.
For professionals already registered as valuers under the Wealth-Tax Act, 1957, this form facilitates the submission of details regarding their existing registration and the associated certificate. It is also essential that the applicant provides information regarding their eligibility under the rules and submits the prescribed documents.
Form 171 for Registration of Income Tax Practitioners
Form 171 is for those individuals who wish to register as authorised income-tax practitioners u/s 515 of the Income-tax Act, 2025.
This form requires the applicant to provide their Permanent Account Number (PAN), residential and office addresses, contact details, educational and professional qualifications, and, where applicable, information about the firm with which they are associated. Applicants are required to provide documents supporting their qualifications.
Individuals who are already registered as authorised Income-tax Practitioners under the Income-tax Act, 1961, are required to provide details of their existing registration and the relevant certificate.
This form also seeks information regarding matters that could affect the applicant’s eligibility under the rules.
Existing Tax Professionals Receive More Time
The latest notification also grants existing professionals more time to fulfil registration requirements under the new tax law. The due date under the concerned norms has been extended from September 30, 2026 to March 31, 2027.
For valuers who were registered under the erstwhile Wealth-Tax Act, the revised procedure provides a mechanism to submit details of their existing registration under the new framework.
What Does It Specify
The immediate change for professionals is that they must use the revised form and provide the information and documents specified under the new rules.
For existing valuers and authorised income-tax practitioners covered under the transitional provisions, the extended deadline grants them time until March 31, 2027, to fulfil the applicable registration requirements.
The revised registration rules reflect a clear policy intent to professionalise tax valuation and representation. By emphasising qualifications, disclosure, and independence right from the outset, the CBDT is moving towards a system that ensures greater accountability for both taxpayers and tax professionals.
Read Notification No. 120/2026