

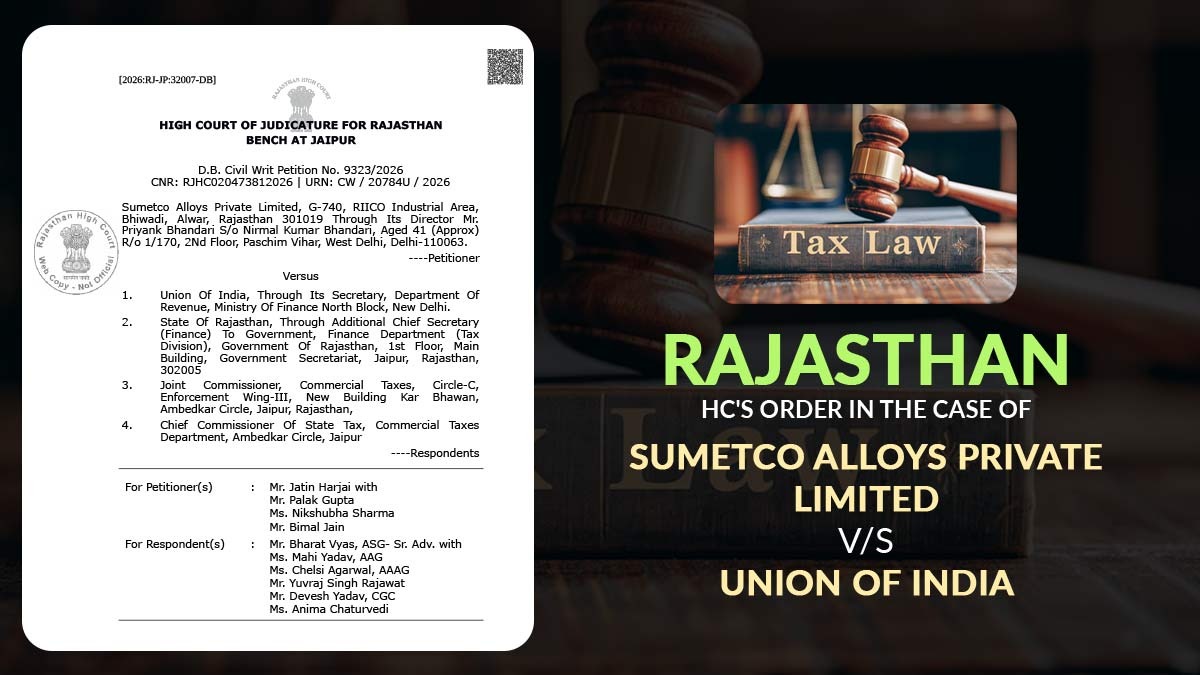
The Rajasthan High Court has maintained the constitutional validity of Section 16(2)(c) of the Central Goods and Services Tax Act, 2017, holding that actual tax payment by the supplier is a valid condition for claiming ITC.
A Division Bench of Justices Arun Monga and Ashutosh Kumar dismissed Sumetco Alloys Private Limited’s challenge to Section 16(2)(c) and its challenge to a Rs. 56.44 crore GST demand for the financial years 2020-21 to 2023-24. The judges said that:
“Section 16(2)(c) suffers from no constitutional infirmity. Secondly, the existence of the reversal and re-availment mechanism under Section 41, read with Sections 73 and 74, is a sufficient answer to the charge of arbitrariness”
Sumetco manufactures pure lead and lead ingots. It contested a demand of Rs 56,44,08,265 after the department alleged that it had incorrectly claimed the ITC on purchases from specific suppliers.
The company claimed that the purchases were real and supported by tax invoices, bank payments, e-way bills, transport documents, and other records. ITC must not be rejected solely because of a supplier’s default when the recipient has fulfilled its own obligations.
The department alleged that the transactions include bogus invoices, fake supplies, and multi-layered paper transactions without actual movement of goods. A show cause notice (SCN) was furnished u/s 74 when the demand order was issued.
The High Court stated that the conditions u/s 16(2) must be fulfilled cumulatively and that ITC is not an absolute or constitutional right, but rather a statutory facility available only upon the fulfilment of certain conditions.
The Court further noted that Section 41 contains provisions for the reversal of ITC if the supplier has not paid the tax, while also permitting its re-availment once the supplier discharges the liability.
The High Court placed reliance on the decision of the Apex Court in Bhandari Scrap Traders v. Union of India and denied Sumetco’s appeal to read down Section 16(2)(c) to safeguard bona fide purchasers. It stated that the Supreme Court had earlier upheld the provisions and denied a similar appeal.
Sumetco’s claim that its transactions were bona fide has been denied by the Bench, holding that the problem involves disputed questions of fact. Since the department had invoked Section 74 on allegations of bogus invoices and fake supplies, the court said that the case needs analysis of proof and could not be determined in writ proceedings.
It denied the challenge to the Section 74 proceedings. It stated that the 33-page SCN has certain allegations of fraud and suppression of information.
It noted that following the amendment to Rule 142(1A)-where “shall” was replaced with “may”-the issuance of Form GST DRC-01A was no longer mandatory.
The judges denied the appeal on the ground of bias, based on the same officer who had performed the investigation and adjudicated the case, noting that the GST law allows the proper officer to conduct both operations.
Since Sumetco had received a notice, filed a detailed reply, and was also granted an opportunity for a hearing, the Bench held that any grievance regarding the consideration of its reply could be raised in the statutory appeal u/s 107. The Bench observed:
“Since the vires challenge fails, to permit bypassing Section 107 by labelling a grievance on merits as a breach of natural justice would render the appellate hierarchy, and the pre-deposit condition that Parliament has attached to it, nugatory”
Therefore, the HC disposed of the writ petition and provided 30 days to Sumetco to submit a plea. It asked the department to provide Sumetco credit for Rs 50 lakh it had deposited via Form GST DRC-03 for the statutory pre-deposit.
| Case Title | Sumetco Alloys Private Limited vs. Union Of India |
| Case No. | D.B. Civil Writ Petition No. 9323/2026 |
| Counsel For Appellant | Mr Jatin Harjai, Mr Palak Gupta, Ms Nikshubha Sharma, and Mr Bimal Jain |
| Counsel For Respondent | Mr Bharat Vyas, Ms Mahi Yadav, Ms. Chelsi Agarwal, Mr. Yuvraj Singh Rajawat, and Mr. Devesh Yadav |
| Rajasthan High Court | Read Order |