

The petitioner initially filed his income tax returns using Form 16 provided by his employer. In this form, the income received from repurchasing Employee Stock Options (ESOPs) under the Flipkart Stock Option Scheme, 2012, was categorised as salary income.
Later, he sought to revise these returns, arguing that this income should be classified as capital gains instead of salary.
He contended that the ESOPs had already vested in him; therefore, the income should not be classified as salary simply because he had not converted the options into shares before their repurchase.
Seeking condonation of delay and consequential refunds, the petitioner approached the Principal Commissioner of Income Tax under Section 119(2)(b) of the Income Tax Act, 1961, to file revised returns.
However, the applications for all five assessment years were dismissed via separate orders dated February 27, 2026.
Before the High Court, the petitioner claimed that the authority had incorrectly assessed the merits of the proposed revised returns instead of focusing on the reasons for the delay and the genuine financial hardship detailed in the applications.
Furthermore, the petitioner had quantified the refunds that would be available upon the revision of the returns, but these details were not taken into consideration.
Read Also: Kerala HC: Tax Refund Application Filed Under Section 119(2)(b) After 9 Years Not Condonable
The High Court said that the jurisdiction u/s 119(2)(b) of the Act is intended to assess the reasons for the delay and the genuine hardship presented by the applicant.
The Court concluded that the Principal Commissioner had effectively made a decision regarding the taxability of the ESOP repurchase proceeds while reviewing the applications for condonation of delay.
Since the authority relied on the opinion of the Assessing Officer regarding the merits of the case, rather than conducting an independent evaluation of the reasons for the delay and the genuine hardship claimed by the petitioner, the rejection orders could not be upheld.
Therefore, the HC set aside all five rejection orders on February 27, 2026, and restored the corresponding applications for reconsideration. The applicant was given a chance to provide further justification.
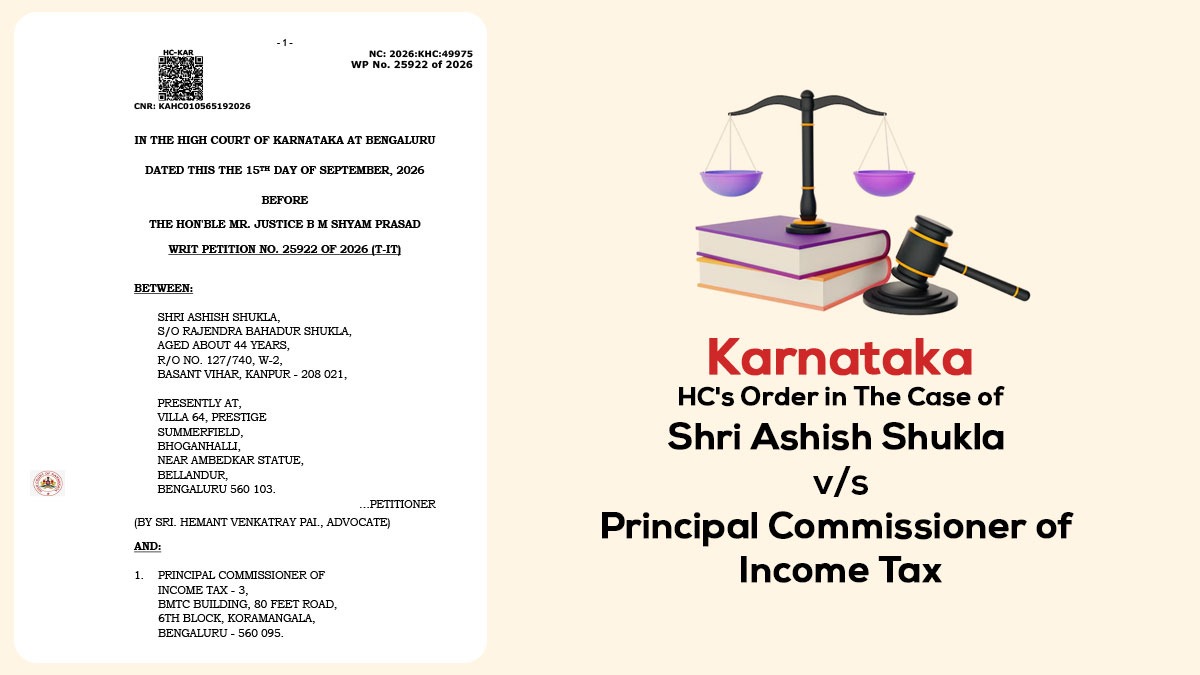
| Applicant Name | Shri Ashish Shukla vs. Principal Commissioner of Income Tax |
| GSTIN of the applicant | NO. 25922 OF 2026 (T-IT) |
| Applicant | Sri. Hemant Venkatray Pai |
| Respondent | Sri. M. Thirumalesh |
| Karnataka High Court | Read Order |