

Adhering to tax-related compliance proposed by the Indian government is mandatory for taxpayers in India. Such compliance also includes adhering to the due dates of GST return filing, about the complete compliance calendar detailed here and specified by the Indian government.
Non-compliance with the due dates of GST return filing as per the June compliance calendar may result in the imposition of heavy penalties by the government on taxpayers in India. When it comes to tax evasion and corruption, tax compliance emerges as a central focus of the Indian government and the tax department.
In any case, a good citizen should always pay their taxes on time while adhering to all major tax-related rules and regulations proposed by the government, as it is vital for the upliftment of the economy. Paying taxes as per the compliance calendar by taxpayers also helps the government properly function the administrative work related to tax collection. Taxpayers can also avoid heavy penalties and fines imposed by the government by filing their Income Tax returns on time.
Here are some of the major due dates concerning various tax compliance by the October 2026 calendar:
October 2026 Compliance Calendar of Income Tax
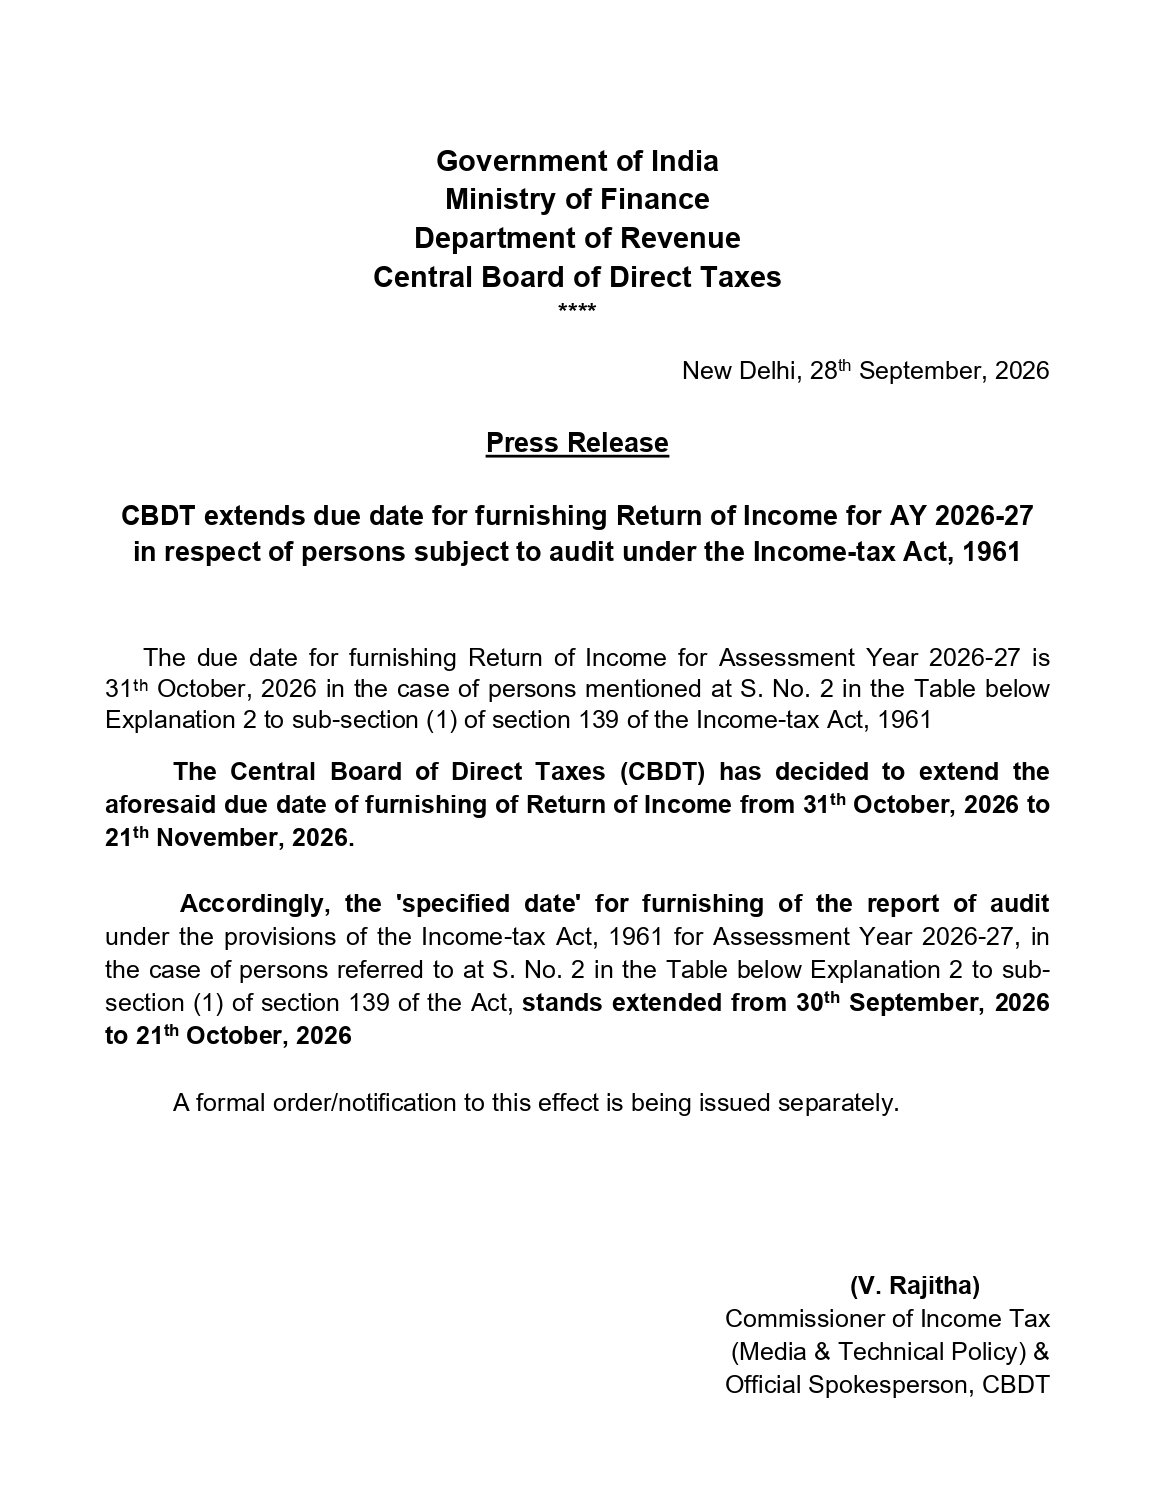
Note: CBDT has extended the due date for filing the tax audit report from 30th September to 21st October 2026 and ITR filing from 31st October to 21st November 2026. Read Press Release
| Date | Description | Sections |
|---|---|---|
| 07-10-2026 | “Due date for furnishing Form No. 137 (Income-tax Rules, 2026) by an office of the Government where TDS/TCS for the month of September, 2026 has been paid without the production of a challan.” | Form No. 137 |
| 07-10-2026 | “Due date for deposit of TDS for the period July 2026 to September 2026 when Assessing Officer has permitted quarterly deposit of TDS under section 392(1) or 393(1) [Table Sl. Nos. (1)(i) and (ii), and 5(ii) and (iii)] of the Income-tax Act, 2025” | Deposit of TDS |
| 07-10-2026 | “Due date for deposit of tax deducted/collected for the month of September 2026. However, all sum deducted/collected by an office of the government shall be paid to the credit of the Central Government on the same day where tax is paid without production of challan” | Tax Deducted/Collected |
| 07-10-2026 | “Upload the declarations received from recipients in Form No. 121 (Income-tax Rules, 2026) during the quarter ending September, 2026” | Form No. 121 |
| 07-10-2026 | “Uploading of declarations received in Form No. 127 (Income-tax Rules, 2026) from the buyer in the month of September, 2026” | Form No. 127 |
| 15-10-2026 | “Statement in Form No. 1 (Income-tax Rules, 2026) by the stock exchange for the month of September 2026, in respect of transactions in which client codes have been modified after registering in the system.” | Form No. 1 |
| 15-10-2026 | “Issue of certificate in Form No. 132 (Income-tax Rules, 2026) under section 395(4) of the Income-tax Act 2025 for tax deducted at source under section 393(1) [Table Sl. No. 2(i), 3(i), 6(ii) & 8(vi)] of the Income-tax Act 2025 in the month of August, 2026” | Form No. 132 |
| 15-10-2026 | “Furnishing of quarterly statement in Form No. 147 (Income-tax Rules, 2026) to be furnished by an authorised dealer in respect of remittances made for the quarter ending September 30, 2026” | Form No. 147 |
| 15-10-2026 | “Furnishing of quarterly statement in Form No. 148 (Income-tax Rules, 2026) to be furnished by a unit of IFSC, as referred to section section 147(1)(b) of the Income-tax Act, 2025, in respect of remittances made for the quarter ending September 30, 2026” | Form No. 148 |
| 15-10-2026 | “Furnishing of statement in Form No. 92 (Income-tax Rules, 2026) by the specified fund or stock broker in respect of a non-resident referred to in rule 157 for the quarter ending September 30, 2026” | Form No. 92 |
| 30-10-2026 | “Furnishing of challan-cum-statement in Form No. 141 (Income-tax Rules, 2026) in respect of deduction of tax under section 393(1) [Table Sl. No. 2(i), 3(i), 6(ii) & 8(vi)] of the Income-tax Act, 2025 for the month of September 2026.” | Form No. 141 |
| 31-10-2026 | “Intimation in Form II by Sovereign Wealth Fund in respect of investment made in India for quarter ending September, 2026” | Form II by Sovereign Wealth Fund |
| 31-10-2026 | “Furnishing of Form No. 10BBD (Income-tax Rules, 1962) reporting details of funds received from eligible persons, directly or through an Alternative Investment Fund, during the Previous Year 2025-26 (if the assessee is required to submit return of income on or before October 31, 2026)” | Form No. 10BBD |
| 31-10-2026 | “Intimation in Form No. 175 (Income-tax Rules, 2026) by a pension fund in respect of each investment made in India for quarter ending September 2026” | Form No. 175 |
| 31-10-2026 | “Audit report under section 44AB (Income-tax Act, 1961) for the assessment year 2026-27 in the case of an assessee who is also required to submit a report pertaining to international or specified domestic transactions under section 92E (Income-tax Act, 1961)” | Assessment Year 2026-27 |
| 31-10-2026 | “Filing of quarterly statement of tax deposited in Form No. 142 (Income-tax Rules, 2026) in relation to transfer of virtual digital asset under section 393(1) [Table: S. No. 8(vi)] of the Income-tax Act, 2025 to be furnished by an Exchange for the quarter ending September 30, 2026″Filing of quarterly statement of tax deposited in Form No. 142 (Income-tax Rules, 2026) in relation to transfer of virtual digital asset under section 393(1) [Table: S. No. 8(vi)] of the Income-tax Act, 2025 to be furnished by an Exchange for the quarter ending September 30, 2026 | Form No. 142 |
| 31-10-2026 | “Filing of quarterly statement of collection of tax at source under section 397(3)(b) of the Income-tax Act, 2025 in Form No.143 (Income-tax Rules, 2026) for the quarter ending September 30, 2026” | Form No.143 |
| 31-10-2026 | “Filing of quarterly statement of TDS in Form No. 144 (Income-tax Rules, 2026) in respect of payments other than salary made to non-residents for quarter ending September 30, 2026” | Form No. 144 |
| 31-10-2026 | “Intimation by a designated constituent entity, resident in India, of an international group in Form No. 3CEAB (Income-tax Rules, 1962) for the accounting year 2025-26″Intimation by a designated constituent entity, resident in India, of an international group in Form No. 3CEAB (Income-tax Rules, 1962) for the accounting year 2025-26 | Form No. 3CEAB |
| 31-10-2026 | “Furnishing of Statement in Form No. 98 (Income-tax Rules, 2026) to the concerned Director/Joint Director (Intelligence and Criminal Investigation) containing declaration received in Form No. 97 (Income-tax Rules, 2026) during April 1, 2026 to September 30, 2026” | Form No. 98 |
| 31-10-2026 | “Furnishing of statement in Form No.3CFA (Income-tax Rules, 1962) for exercising the option to pay tax at a concessional rate under Section 115BBF (Income-tax Act, 1961) for income in the nature of royalty arising from patent developed and registered in India (if the assessee is required to submit return of income by October 31, 2026)” | Form No.3CFA |
| 31-10-2026 | “Furnishing of an annual statement of exempt income under Section 10(4D) (Income-tax Act, 1961) and income taxable under Section 115AD (Income-tax Act, 1961) in Form No.10-IK (Income-tax Rules, 1962) (if assessee is required to submit return of income by October 31, 2026)” | Annual Statement |
| 31-10-2026 | “Filing of quarterly statement in Form No. 138 (Income-tax Rules, 2026) by employers responsible for TDS from salaries paid to employees under section 392 or by specified bank in respect of income paid to specified senior citizen under section 393(1) [Table: Sl. No. 8(iii)] of the Income-tax Act, 2025 for the quarter ending September 30, 2026” | Form No. 138 |
| 31-10-2026 | “Filing of quarterly statement in Form No. 140 (Income-tax Rules, 2026) by deductors responsible for deduction of tax at source on non-salary payments such as commission, brokerage, professional fees, rent, etc. made to residents for the quarter ending September 30, 2026” | Form No. 140 |
| 31-10-2026 | “Submission of a report from a Chartered Accountant in Form No. 3CEJA (Income-tax Rules, 1962) for the previous year 2025-26 for the purpose of section 9A (Income-tax Act, 1961) regarding fulfilment of certain conditions by an eligible investment fund. etds-relevant-section” | Form No. 3CEJA |
| 31-10-2026 | “Furnishing of certificate in Form No.10-IJ (Income-tax Rules, 1962) issued by a Chartered Accountant certifying the annual statement of exempt income of the specified fund, being a category-III AIF, under Section 10(23FF) (Income-tax Act, 1961) (if the assessee is required to submit the return of income on or before November 30, 2026)” | Form No.10-IJ |
| 31-10-2026 | “Filing intimation in Form No.3CEAC (Income-tax Rules, 1962) by a constituent entity resident in India (whose parent entity is not resident in India), notifying the prescribed authority of the details of the parent entity/alternate reporting entity for Country-by-Country Reporting purposes. (assuming reporting accounting year is January 1, 2025, to December 31, 2025)” | Form No.3CEAC |
| 31-10-2026 | “Report to be furnished under section 92E (Income-tax Act, 1961) in Form No. 3CEB (Income-tax Rules, 1962) in respect of international transactions and specified domestic transaction” | Form No. 3CEB |
Recommended: Income Tax Return Filing Due Dates
GST Compliance Calendar of October 2026
| Due Dates | Compliance Particulars | Forms/(Filing Mode) |
|---|---|---|
| 11.10.2026 | The last date to file the GSTR-1 form is 11th October 2026, for taxpayers having an annual aggregate turnover of more than INR 1.5 crore or those who have opted for monthly return filing. | GSTR 1 |
| 13.10.2026 | Quarterly (T.O. up to 1.5 Crore) | GSTR 1 |
| 13.10.2026 | Monthly (September 2026) | IIF |
| 20.10.2026 | Annual Turnover of more than INR 5cr in the Previous FY | September 2026 | GSTR 3B |
| 20.10.2026 | Annual Turnover of up to INR 5cr in the previous FY | September 2026 | GSTR 3B |
| 22.10.2026 | Quarterly | GSTR 3B (G1) |
| 24.10.2026 | Quarterly | GSTR 3B (G2) |
| 13.10.2026 | All non-resident persons must file the GSTR-5 alongside the payment of GST on or before the given due date in September 2026. | GSTR 5 |
| 20.10.2026 | All the non-resident ODIAR service providers should file their monthly return GSTR-5A on or before the given due date of 20th October 2026, for the month of September 2026. | GSTR 5A |
| 13.10.2026 | Every Input Service Distributor (ISD) must file GSTR-6 on or before the given due date of 13th October for the period of September 2026. | GSTR 6 |
| 10.10.2026 | The due date for filing GSTR 7 for the period of September 2026 is 10th October. | GSTR-7 |
| 10.10.2026 | The due date for furnishing GSTR 8 for the period August 2026 for registered e-commerce taxpayers in India who are liable to pay TCS should be deducted on or before deducted on or before 10th October. | GSTR 8 |
| 18.10.2026 | Quarterly | CMP-08 |

Dear Sir / Madam,
Please provide me with a monthly “Statutory and Tax Compliance Calendar for November 2025”.
The email id is
akshayrajeev77@gmail.com
akshayrajeev2158@gmail.com
Rgds/ Akshay
Nice
itne bade company ko pata nhi h kya GSTR-5 ki due date 13 of every month hoti h
Sir, this post is not updated by the company. It is marketing teamwork and this update came in Budget 2022. thanks