

Adhering to tax-related compliance proposed by the Indian government is mandatory for taxpayers in India. Such compliance also includes adhering to the due dates of GST return filing, about the complete compliance calendar detailed here and specified by the Indian government.
Non-compliance with the due dates of GST return filing as per the June compliance calendar may result in the imposition of heavy penalties by the government on taxpayers in India. When it comes to tax evasion and corruption, tax compliance emerges as a central focus of the Indian government and the tax department.
In any case, a good citizen should always pay their taxes on time while adhering to all major tax-related rules and regulations proposed by the government, as it is vital for the upliftment of the economy. Paying taxes as per the compliance calendar by taxpayers also helps the government properly function the administrative work related to tax collection. Taxpayers can also avoid heavy penalties and fines imposed by the government by filing their Income Tax returns on time.
Here are some of the major due dates concerning various tax compliance by the November 2026 calendar:
November 2026 Compliance Calendar of Income Tax
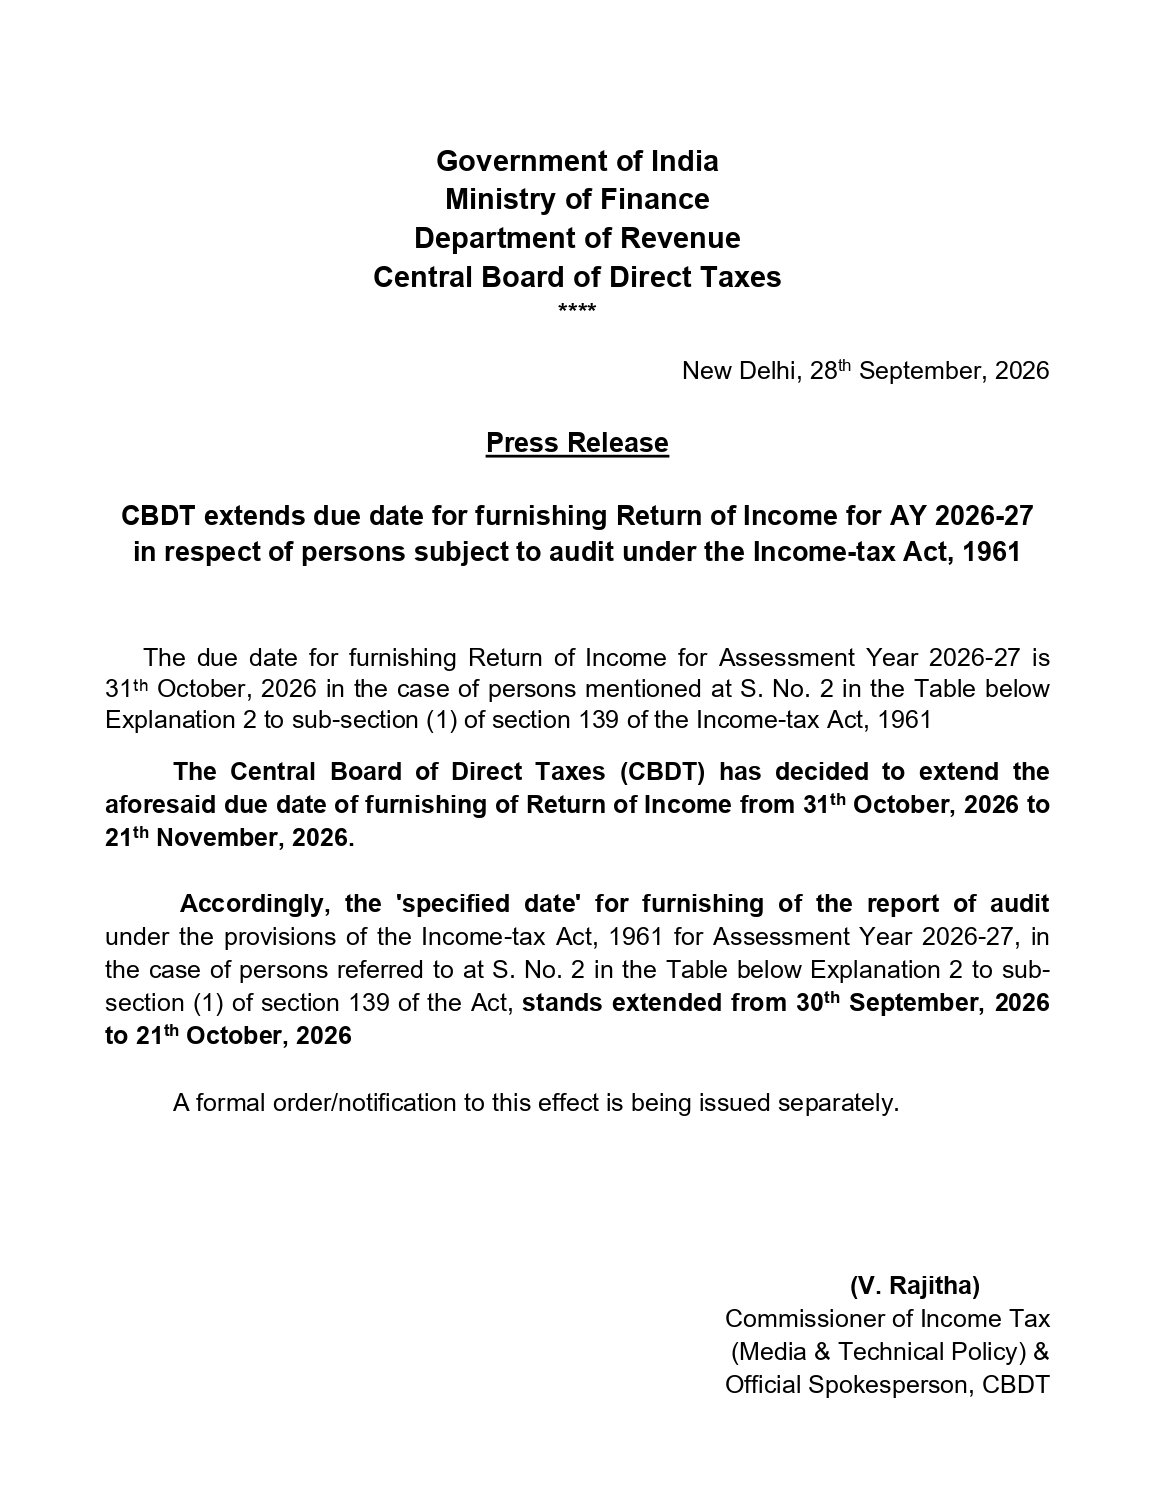
Note: CBDT has extended the due date for filing the tax audit report from 30th September to 21st October 2026 and ITR filing from 31st October to 21st November 2026. Read Press Release
| Date | Description | Sections |
|---|---|---|
| 07-11-2026 | “Due date for deposit of Tax deducted/collected for the month of October 2026. However, all sum deducted/collected by an office of the government shall be paid to the credit of the Central Government on the same day where tax is paid without production of challan” | Tax Deducted/Collected |
| 07-11-2026 | “Uploading of declarations received in Form No. 127 (Income-tax Rules, 2026) from the buyer in the month of October, 2026” | Form No. 127 |
| 14-11-2026 | “Issue of certificate in Form No. 132 (Income-tax Rules, 2026) under section 395(4) of the Income-tax Act 2025 for tax deducted at source under section 393(1) of the Income-tax Act 2025 [Table Sl. No. 2(i), 3(i), 6(ii) & 8(vi)] in the month of September, 2026” | Form No. 132 |
| 15-11-2026 | “Due date for furnishing Form No. 137 (Income-tax Rules, 2026) by an office of the Government where TDS/TCS for the month of October, 2026 has been paid without the production of a challan.” | Form No. 137 |
| 15-11-2026 | “Statement in Form 1 (Income-tax Rules, 2026) by the stock exchange for the month of October 2026, in respect of transactions in which client codes have been modified after registering in the system.” | Form 1 |
| 15-11-2026 | “Issuance of TCS certificate in Form No. 133 (Income-tax Rules, 2026) under section 395(4) of the Income-tax Act, 2025 for tax collected at source for the quarter ending September 30, 2026” | Form No. 133 |
| 15-11-2026 | “Issuance of TDS certificate in Form No. 131 (Income-tax Rules, 2026) for TDS other than on salary, pension or interest income of specified senior citizen under section 393(1) of the Income-tax Act, 2025 for the quarter ending September 30, 2026” | Form No. 131 |
| 15-11-2026 | “Furnishing of quarterly statement in Form No. 147 (Income-tax Rules, 2026) to be furnished by an authorised dealer in respect of remittances made for the quarter ending September 30, 2026” | Form No. 147 |
| 21-11-2026 | “Due date for furnishing the return of income for the Assessment Year 2026–27 by the following assessees: A company to whom the provisions of Section 92E of the Income-tax Act, 1961 do not apply. An assessee whose accounts are required to be audited, to whom the provisions of Section 92E of the Income-tax Act, 1961 do not apply. A partner of a firm whose accounts are required to be audited, or the spouse of such partner (where Section 5A of the Income-tax Act, 1961 applies), to whom the provisions of Section 92E of the Income-tax Act, 1961 do not apply. Note: The due date for furnishing of return of income for Assessment Year 2026-27 has been extended from October 31, 2026, to November 21, 2026, vide Circular No. 07/2026 dated 28-09-2026″ | Assessment Year |
| 21-11-2026 | “Statement by scientific research association, company university, college or other association or Indian scientific research company as required by Rules 5D, 5E and 5F of the Income-tax Rules, 1962 (if due date of submission of return of income is October 31, 2026) Note: The due date for furnishing of statement has been extended from October 31, 2026, to November 21, 2026, vide Circular No. 07/2026 dated 28-09-2026″ | Scientific Research Association |
| 21-11-2026 | “Furnishing of annual statement in Form No. 10-II (Income-tax Rules, 1962) in respect of exempt income under Section 10(23FF) (Income-tax Act, 1961) by specified fund, being a category-III AIF (if assessee is required to submit return of income on or before October 31, 2026) Note: The due date for furnishing of statement has been extended from October 31, 2026, to November 21, 2026, vide Circular No. 07/2026 dated 28-09-2026″ | Form No. 10-II |
| 21-11-2026 | “Furnishing of an annual statement of income exempt under section 10(4D) (Income-tax Act, 1961) in Form 10-IG (Income-tax Rules, 1962) (if assessee is required to submit return of income on or before October 31, 2026) Note: The due date for furnishing of statement has been extended from October 31, 2026, to November 21, 2026, vide Circular No. 07/2026 dated 28-09-2026″ | Form 10-IG |
| 21-11-2026 | “Furnishing of an annual statement of income taxable at concessional rate under section 115AD (Income-tax Act, 1961) in Form 10-IH (Income-tax Rules, 1962) (if assessee is required to submit return of income on or before October 31, 2026) Note: The due date for furnishing of statement has been extended from October 31, 2026, to November 21, 2026, vide Circular No. 07/2026 dated 28-09-2026″ | Form 10-IH |
| 21-11-2026 | “Furnishing of audit report in Form No. 10BC (Income-tax Rules, 1962) along with particulars forming part of its Annexure by electoral trust Note: The due date for furnishing of report has been extended from October 31, 2026, to November 21, 2026, vide Circular No. 07/2026 dated 28-09-2026″ | Form No. 10BC |
| 21-11-2026 | “Furnishing of Form No. 10BBD (Income-tax Rules, 1962) reporting details of funds received from eligible persons, directly or through an Alternative Investment Fund, during the Previous Year 2025-26 (if the assessee is required to submit return of income on or before October 31, 2026) Note: The due date for furnishing of Form has been extended from October 31, 2026, to November 21, 2026, vide Circular No. 07/2026 dated 28-09-2026″ | Form No. 10BBD |
| 21-11-2026 | “Furnishing of report in Form No.10CCF (Income-tax Rules, 1962) certifying that the amount of deduction under Section 80LA (Income-tax Act, 1961) has been correctly claimed during the previous year 2025-26 (if the assessee is required to submit return of income on or before October 31, 2026) Note: The due date for furnishing of Form has been extended from October 31, 2026, to November 21, 2026, vide Circular No. 07/2026 dated 28-09-2026″ | Form No.10CCF |
| 21-11-2026 | “Furnishing of declaration in Form No.10BA (Income-tax Rules, 1962) by an assessee claiming deduction under Section 80GG (Income-tax Act, 1961) in respect of the rent paid for residential accommodation (If the assessee is required to furnish the return of income on or before October 31, 2026) Note: The due date for furnishing of Form has been extended from October 31, 2026, to November 21, 2026, vide Circular No. 07/2026 dated 28-09-2026″ | Form No.10BA |
| 21-11-2026 | “Furnishing of statement in Form No.10-EE (Income-tax Rules, 1962) for exercising the option to claim relief under Section 89A (Income-tax Act, 1961) for income arising from retirement benefit account maintained in a notified country at the time of withdrawal or redemption (if the assessee is required to submit the return of income on or before October 31, 2026) Note: The due date for furnishing of Form has been extended from October 31, 2026, to November 21, 2026, vide Circular No. 07/2026 dated 28-09-2026″ | Form No.10-EE |
| 21-11-2026 | “Furnishing of statement in Form No. 3CFA (Income-tax Rules, 1962) for exercising the option to pay tax at a concessional rate under Section 115BBF (Income-tax Act, 1961) for income in the nature of royalty arising from patent developed and registered in India (if the assessee is required to submit return of income by October 31, 2026) Note: The due date for furnishing of Form has been extended from October 31, 2026, to November 21, 2026, vide Circular No. 07/2026 dated 28-09-2026″ | Form No. 3CFA |
| 21-11-2026 | “Furnishing of Form No.10E (Income-tax Rules, 1962) by an employee claiming relief under Section 89 (Income-tax Act, 1961) when salary is paid in arrears or in advance, etc. (if the assessee is required to submit the return of income on or before October 31, 2026) Note: The due date for furnishing of Form has been extended from October 31, 2026, to November 21, 2026, vide Circular No. 07/2026 dated 28-09-2026″ | Form No.10E |
| 21-11-2026 | “Furnishing of an annual statement of exempt income under Section 10(4D) (Income-tax Act, 1961) and income taxable under Section 115AD (Income-tax Act, 1961) in Form No.10-IK (Income-tax Rules, 1962) (if assessee is required to submit return of income by October 31, 2026) Note: The due date for furnishing of Form has been extended from October 31, 2026, to November 21, 2026, vide Circular No. 07/2026 dated 28-09-2026″ | Form No.10-IK |
| 21-11-2026 | “Furnishing of Form No. 5C (Income-tax Rules, 1962) containing details of attribution of capital gain taxable under Section 45(4) (Income-tax Act, 1961) to the capital asset remaining with the firm, AOP, or BOI after reconstitution (if the firm, AOP, or BOI is required to furnish return of income on or before October 31, 2026) Note: The due date for furnishing of Form has been extended from October 31, 2026, to November 21, 2026, vide Circular No. 07/2026 dated 28-09-2026″ | Form No. 5C |
| 21-11-2026 | “Furnishing of audited accounts in Form No.3CLA (Income-tax Rules, 1962) to the Secretary, Department of Scientific and Industrial Research, in case the company is eligible for deduction under Section 35(2AB) (Income-tax Act, 1961) (if the assessee is required to submit return of income on or before October 31, 2026) Note: The due date for furnishing of Form has been extended from October 31, 2026, to November 21, 2026, vide Circular No. 07/2026 dated 28-09-2026″ | Form No.3CLA |
| 21-11-2026 | “Furnishing of a certificate, by the Notified Pension Fund, issued by a Chartered Accountant in Form No.10BBC (Income-tax Rules, 1962) in respect of compliance with the provisions of Section 10(23FE) (Income-tax Act, 1961) Note: The due date for furnishing of Certificate has been extended from October 31, 2026, to November 21, 2026, vide Circular No. 07/2026 dated 28-09-2026″ | Form No.10BBC |
| 21-11-2026 | “Furnishing of certificate Form No.10CCE (Income-tax Rules, 1962) by a resident individual being a patentee claiming deduction under Section 80RRB (Income-tax Act, 1961) in respect of royalty income on patents (if the assessee is required to submit return of income on or before October 31, 2026) Note: The due date for furnishing of Form has been extended from October 31, 2026, to November 21, 2026, vide Circular No. 07/2026 dated 28-09-2026″ | Form No.10CCE |
| 21-11-2026 | “Furnishing of certificate of foreign inward remittance in Form No.10H (Income-tax Rules, 1962) by a resident individual being an author/patentee claiming deduction under Section 80QQB/Section 80RRB (Income-tax Act, 1961) in respect of income earned from any source outside India (if the assessee is required to submit the return of income on or before October 31, 2026) Note: The due date for furnishing of Form has been extended from October 31, 2026, to November 21, 2026, vide Circular No. 07/2026 dated 28-09-2026″ | Form No.10H |
| 21-11-2026 | “Furnishing of the certificate in Form No. 10-IA (Income-tax Rules, 1962) from the medical authority certifying ‘person with disability’, ‘severe disability’, ‘autism’, ‘cerebral palsy’ or ‘multiple disability’ for the purposes of Section 80DD and Section 80U (Income-tax Act, 1961). (If the assessee is required to furnish the return of income on or before October 31, 2026) Note: The due date for furnishing of Form has been extended from October 31, 2026, to November 21, 2026, vide Circular No. 07/2026 dated 28-09-2026″ | Form No. 10-IA |
| 30-11-2026 | “Furnishing of Form No. 5C (Income-tax Rules, 1962) containing details of attribution of capital gain taxable under section 45(4) (Income-tax Act, 1961) to the capital asset remaining with the firm, AOP, or BOI after reconstitution (if the firm, AOP, or BOI is required to furnish the return of income by November 30, 2026)” | Form No. 5C |
| 30-11-2026 | “Furnishing of the certificate in Form No. 62 (Income-tax Rules, 1962) by the amalgamated company, confirming achievement of the prescribed production level and its continuation in subsequent years. (if the company is required to submit return of income on or before November 30, 2026)” | Form No. 62 |
| 30-11-2026 | “Furnishing of the certificate in Form No. 10-IA (Income-tax Rules, 1962) from the medical authority certifying ‘person with disability’, ‘severe disability’, ‘autism’, ‘cerebral palsy’ or ‘multiple disability’ for the purposes of sections 80DD and 80U (Income-tax Act, 1961). (If the assessee is required to furnish the return of income on or before November 30, 2026)” | Form No. 10-IA |
| 30-11-2026 | “Due date for furnishing the return of income for the Assessment Year 2026–27 by an assessee, including a partner of a firm or the spouse of such partner (where Section 5A of the Income-tax Act, 1961 applies), who is required to furnish a report under Section 92E of the Income-tax Act, 1961.” | Assessment Year 2026–27 |
| 30-11-2026 | “Furnishing of declaration in Form No. 10BA (Income-tax Rules, 1962) by an assessee claiming deduction under Section 80GG (Income-tax Act, 1961) in respect of the rent paid for residential accommodation (If the assessee is required to furnish the return of income on or before November 30, 2026)” | Form No. 10BA |
| 30-11-2026 | “Furnishing of report in Form No. 10CCF (Income-tax Rules, 1962) certifying that the amount of deduction under section 80LA (Income-tax Act, 1961) has been correctly claimed during the previous year 2025-26 (if the assessee is required to submit return of income on or before November 30, 2026)” | Form No. 10CCF |
| 30-11-2026 | “Report in Form No. 3CEAA (Income-tax Rules, 1962) by a constituent entity of an international group for the Accounting Year 2025-26” | Form No. 3CEAA |
| 30-11-2026 | “Furnishing of audited accounts in Form No. 3CLA (Income-tax Rules, 1962) to the Secretary, Department of Scientific and Industrial Research, in case the company is eligible for deduction under Section 35(2AB) (Income-tax Act, 1961) [if the assessee is required to submit return of income on or before November 30, 2026)” | Form No. 3CLA |
| 30-11-2026 | “Furnishing of certificate in Form No. 10CCD (Income-tax Rules, 1962) by a resident individual being an author (including a joint author) claiming deduction under section 80QQB (Income-tax Act, 1961) in respect of royalty income (if the assessee is required to submit return of income on or before November 30, 2026” | Form No. 10CCD |
| 30-11-2026 | “Furnishing of certificate Form No. 10CCE (Income-tax Rules, 1962) by a resident individual being a patentee claiming deduction under section 80RRB (Income-tax Act, 1961) in respect of royalty income on patents (if the assessee is required to submit return of income on or before November 30, 2026)” | Form No. 10CCE |
| 30-11-2026 | “Statement by scientific research association, company university, college or other association or Indian scientific research company as required by Rules 33, 34 and 35 of the Income-tax Rules, 2026 (if due date of submission of return of income is November 30, 2026)” | Scientific Research Association |
| 30-11-2026 | “Furnishing of statement in Form No. 10-EE (Income-tax Rules, 1962) for exercising the option to claim relief under section 89A (Income-tax Act, 1961) for income arising from retirement benefit account maintained in a notified country at the time of withdrawal or redemption (if the assessee is required to submit the return of income on or before November 30, 2026)” | Form No. 10-EE |
| 30-11-2026 | “Furnishing of the application in Form No. 3CEFA, Form No. 3CEFB & Form No. 3CEFC (Income-tax Rules, 1962) for opting for Safe Harbour” | Form No. 3CEFA, Form No. 3CEFB & Form No. 3CEFC |
| 30-11-2026 | “Furnishing of statement in Form No. 3CFA (Income-tax Rules, 1962) for exercising the option to pay tax at a concessional rate under section 115BBF (Income-tax Act, 1961) for income in the nature of royalty arising from patent developed and registered in India (if the assessee is required to submit return of income by November 30, 2026) | Form No. 3CFA |
| 30-11-2026 | “Furnishing of Form No. 10E (Income-tax Rules, 1962) by an employee claiming relief under section 89 (Income-tax Act, 1961) when salary is paid in arrears or in advance, etc. (if the assessee is required to submit the return of income on or before November 30, 2026)” | Form No. 10E |
| 30-11-2026 | “Furnishing of certificate of foreign inward remittance in Form No. 10H (Income-tax Rules, 1962) by a resident individual being an author/patentee claiming deduction under Section 80QQB/80RRB (Income-tax Act, 1961) in respect of income earned from any source outside India (if the assessee is required to submit the return of income on or before November 30, 2026)” | Form No. 10H |
| 30-11-2026 | “Furnishing of an annual statement of income taxable at concessional rate under section 115AD (Income-tax Act, 1961) in Form 10-IH (Income-tax Rules, 1962) (if assessee is required to submit return of income on or before November 30, 2026)” | Form 10-IH |
| 30-11-2026 | “Furnishing of an annual statement of exempt income under section 10(4D) (Income-tax Act, 1961) and income taxable under section 115AD (Income-tax Act, 1961) in Form No. 10-IK (Income-tax Rules, 1962) (if assessee is required to submit return of income by November 30, 2026)” | Form No. 10-IK |
| 30-11-2026 | “Submission of statement of income distributed by venture capital company or venture capital fund in respect of income distributed during the previous year 2025-2026 in Form No. 64 (Income-tax Rules, 1962)” | Form No. 64 |
| 30-11-2026 | “Electronic submission of statement in Form No. 49C (Income-tax Rules, 1962) by a non-resident under Section 285 (Income-tax Act, 1961) having a liaison office in India for the Financial Year 2025-26” | Form No. 49C |
| 30-11-2026 | “Furnishing of Form No. 10BBD (Income-tax Rules, 1962) reporting details of funds received from eligible persons, directly or through an Alternative Investment Fund, during the Previous Year 2025-26 (if the assessee is required to submit return of income on or before November 30, 2026)” | Form No. 10BBD |
| 30-11-2026 | “Furnishing of annual statement in Form No. 10-II (Income-tax Rules, 1962) in respect of exempt income under section 10(23FF) (Income-tax Act, 1961) by specified fund, being a category-III AIF (if assessee is required to submit return of income on or before November 30, 2026)” | Form No. 10-II |
| 30-11-2026 | “Furnishing of an annual statement of income exempt under section 10(4D) (Income-tax Act, 1961) in Form 10-IG (Income-tax Rules, 1962) (if assessee is required to submit return of income on or before November 30, 2026)” | Form 10-IG |
| 30-11-2026 | “Furnishing of challan-cum-statement in Form No. 141 (Income-tax Rules, 2026) in respect of deduction of tax under section 393(1) [Table Sl. No. 2(i), 3(i), 6(ii) & 8(vi)] of the Income-tax Act, 2025 for the month of October 2026.” | Form No. 141 |
Recommended: Income Tax Return Filing Due Dates
GST Compliance Calendar of November 2026
| Due Dates | Compliance Particulars | Forms/(Filing Mode) |
|---|---|---|
| 11.11.2026 | The last date to file the GSTR-1 form is 11th November 2026, for taxpayers having an annual aggregate turnover of above INR 5 crore or those who have opted for monthly return filing. | GSTR 1 |
| 13.11.2026 | Monthly (October 2026) | IIF |
| 20.11.2026 | Annual Turnover of more than INR 5cr in the Previous FY | October 2026 | GSTR 3B |
| 20.11.2026 | Annual Turnover of up to INR 5cr in the previous FY | October 2026 | GSTR 3B |
| 13.11.2026 | All non-resident persons must file the GSTR-5 alongside the payment of GST on or before the given due date in October 2026. | GSTR 5 |
| 20.11.2026 | All the non-resident ODIAR service providers should file their monthly return GSTR-5A on or before the given due date of 20th November 2026, for the month of October 2026. | GSTR-5A |
| 13.11.2026 | Every Input Service Distributor (ISD) must file GSTR-6 on or before the given due date of 13th November for the period of October 2026. | GSTR 6 |
| 10.11.2026 | The due date for filing GSTR-7 for the period of October 2026 is 10th November. | GSTR-7 |
| 10.11.2026 | The due date for furnishing GSTR 8 for the period October 2026 for registered e-commerce taxpayers in India who are liable to pay TCS should be deducted on or before deducted on or before 10th November. | GSTR 8 |

this line may be Rectify ‘Previous FY 2021- 2022 GSTR 3B20.06.2022 Annual Turnover of more than INR 5cr in Previous FY May 2022 GSTR 3B
Updates gst
31-4-2021. Due date For GSTR-4. Please Check…
Please correct the due date of GSTR 4 to 30/04/2021 instead of 31/04/2021
useful and valuable updations
Good