

The Goods and Services Tax Network (GSTN), following Notification No. 05/2026-Central Tax dated October 26, 2026, has implemented significant changes to the GST registration amendment process on the GST portal.
These changes, notified through amended GST rules, have come about as a result of the replacement of provisions relating to the amendment of registration under Rule 19 of the Central Goods and Services Tax (CGST) Rules, 2017. Under the revised system, the process for making changes to GST registration details has been facilitated for several categories.
While modifications related to the Principal Place of Business (PPoB) will continue to be analysed by a ‘proper officer’ (authorised official), other changes will be processed through online verification and a prescribed OTP-based authentication.
One of the key changes is that, wherever applicable, the amended registration certificate will be made available electronically once the necessary online verifications have been completed. This process will eliminate the need for the officer-level scrutiny that is typically required for other categories of amendments.
This advisory is crucial for businesses, tax professionals, and GST practitioners who manage amendments to GST registration details.
GSTN Advisory on Changes to GST Registration Process
Vide the Notification No. 05/2026-Central Tax dated 26.10.2026, Rule 21 of the Central Goods and Services Tax Rules, 2017, the provisions for the amendment of registration under Rule 19 of the CGST Rules, 2017 have been replaced. On the GST portal, the corresponding changes have been implemented.
Modification of Principal Place of Business(PPOB)
For amendment of the Principal Place of Business (PPOB), the application will continue to be analysed by the Proper Officer in accordance with Rule 19 of the Central Goods and Services Tax Rules, 2017.
Changes to Other Registration Details
- Concerning the other revisions, such as changes in the legal name of the business and addition, deletion, or retirement of partners, directors, Karta, etc., Additional Place of Business, and other amendments to the particulars of Form REG-01 other than the Principal Place of Business, the certificate of registration shall stand amended upon submission and online validation.
- Online verification of the mobile number and email address is mandatory for both the Primary Authorised Signatory and a designated promoter, partner, director, Karta, member, or trustee.
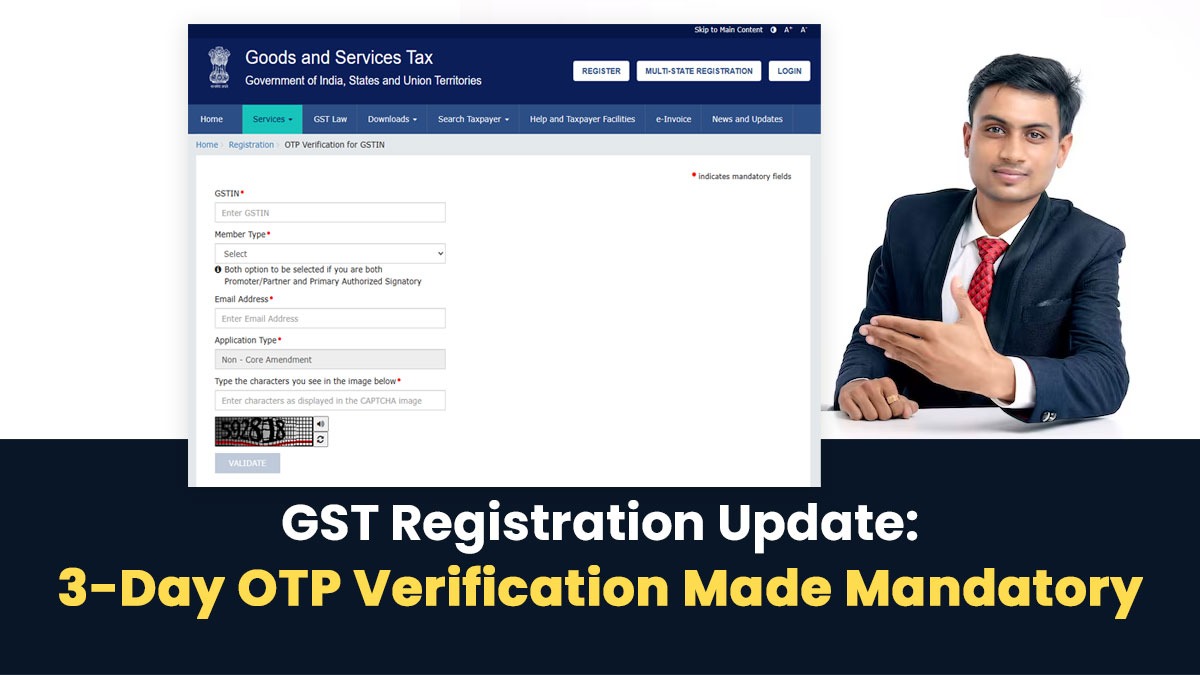
- The specified online verification of the mobile number and email address (OTP verification) can be performed via the Common Portal using the following link: https://services.gst.gov.in/services/otpVerification, which can also be accessed through: Services->Registration->OTP verification of GSTIN.
- A time period of 3 days from the date of submission of the application will be provided for completing the prescribed OTP verification. If verification is not concluded successfully within this period, the Application Reference Number (ARN) will not be generated.
- PAN, Director Identification Number (DIN) and Corporate Identification Number (CIN), wherever applicable, will be validated online by the system. After successful completion of the required validations, the ARN will be generated.
- Once the required online verification and validations are successfully completed, the amended Registration Certificate will be made available to the registered taxpayer on the common portal.
Taxpayers must provide precise particulars and upload the pertinent supporting documents at the time of filing Form GST REG-14. They must ensure successful completion of the said online verification, wherever applicable.
Read GST Advisory