

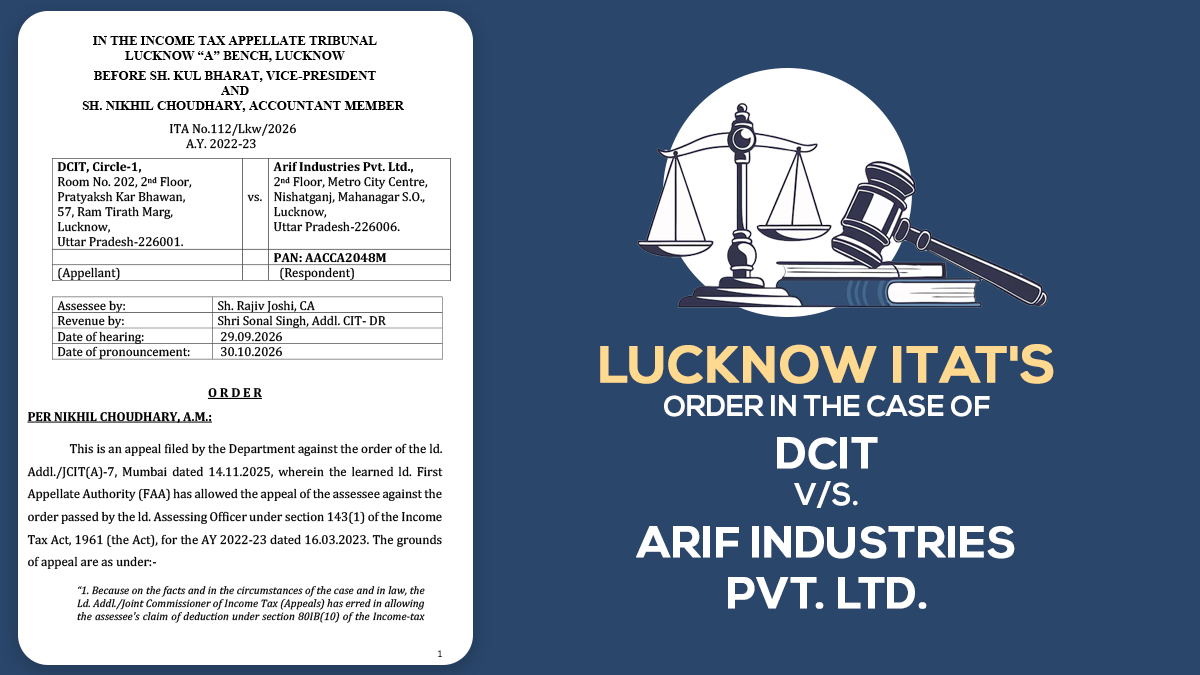
The taxpayer has submitted an ITR for AY 2022-23, reporting a total income of Rs 1,87,10,752. During the processing of the return under Section 143(1) of the Act, the CPC rejected the taxpayer’s claim for a deduction of Rs 3,36,91,079 under Section 80IB(10), stating that the audit report in Form 10CCB had not been submitted within the prescribed time. Afterward, a tax demand of Rs 58,95,760 was raised against the taxpayer.
The taxpayer argued that both their income tax return and the audit report in Form 10CCB had been submitted on 13/10/2022, that is, before the prescribed due date for filing the return. Furthermore, the taxpayer had also submitted their tax audit report in Form 3CA-3CD, as required under Section 44AB, on 30/09/2022. The taxpayer contested this adjustment before the ‘First Appellate Authority,’ which accepted their appeal.
The Tribunal examined the arguments from both sides and found that a similar issue had already been considered by another of its benches. This matter pertains to the same assessee and relates to the same assessment year (ITA No. 638/Lkw/2024, order dated 28/10/2025). The same bench held that since Form 10CCB was submitted before the due date for filing the income tax return, that is, on 13/10/2022, the taxpayer’s claim for a deduction was in accordance with the law and should be accepted.
Regarding the issue of the timing for filing Form 10CCB, the Tribunal analysed the provisions of Section 80IB. It stated that the condition that requires the audit report to be provided within the specified time u/s 44AB is incorporated in Sections 80IB(7A), 80IB(7B), 80IB(11B) and 80IB(11C). However, no such provisions have been stipulated u/s 80IB(10).
Therefore, the Tribunal stated that the deduction claimed u/s 80IB(10) could not be denied solely on the grounds that Form 10CCB was not filed one month prior to the due date stipulated u/s 139(1). The Tribunal rejected all the arguments raised by the Revenue Department and upheld the deduction under Section 80IB(10) in favour of Arif Industries Private Limited.
| Case Title | DCIT vs. Arif Industries Pvt. Ltd. |
| Case No. | ITA No.112/Lkw/2026 |
| Assessee by | Sh. Rajiv Joshi, CA |
| Revenue by | Shri Sonal Singh, Addl. CIT- DR |
| ITAT Lucknow | Read Order |