

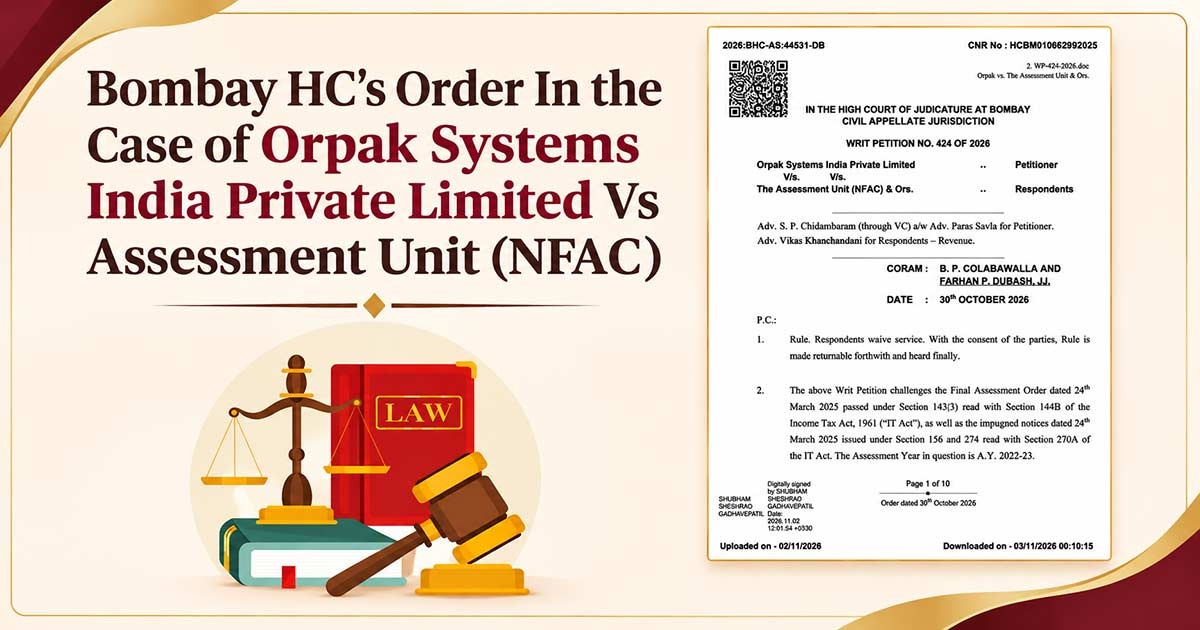
The Bombay High Court states that the Income Tax Department cannot pass a final assessment order against an eligible taxpayer without initially issuing a draft assessment order, as mandated under Section 144B and Section 144C of the Income Tax Act, 1961.
A Division Bench including Justices B.P. Colabawalla and Farhan P. Dubash set aside the final assessment order passed against Orpak Systems India Private Limited, after the Revenue admitted that it had not issued a draft assessment order. The judges said that:
“These provisions clearly stipulate that in case of an eligible assessee, a Draft Assessment Order has to be served on the Petitioner to enable the Petitioner to approach the DRP.”
This matter came to light when the income tax return of ‘Orpack Systems India’ for the assessment year 2022-23 was selected for scrutiny. Following a ‘transfer pricing adjustment’ of nearly Rs 2.41 crore, the assessing officer issued a final assessment order directly, without initially issuing a ‘draft assessment order’.
The company contested this order. It argued that under section 144C, the department is required to issue a ‘draft assessment order’ before passing the final assessment order, so that the company may file its objections before the ‘Dispute Resolution Panel’ (DRP).
The Revenue Department acknowledged that it had not issued a draft assessment order, but argued that this omission was an inadvertent procedural error. The Department requested that the matter be remanded so that the Assessing Officer could rectify this deficiency.
The High Court denied this claim and placed reliance on its earlier decisions in Danfoss Fluid Power Private Limited v. Union of India and Barentz India Private Limited v. Assessment Unit, which had dealt with similar violations. It refused to remand the case to the Assessing Officer, stating that:
“As far as the prayer for remand is concerned, we see no reason to remand the matter back to the Assessing Officer.”
Also Read: Delhi High Court: Final Assessment U/S 143 Invalid if Pending Objections Before DRP Are Ignored
However, the bench clarified that if permitted under the law, the department could initiate fresh proceedings by issuing a draft assessment order. The question of whether or not such proceedings could be initiated was left open. Therefore, the HC permitted the writ petition and set aside the final assessment order.
| Case Title | Orpak Systems India Private Limited Vs Assessment Unit (NFAC) |
| Case No. | Writ Petition No. 424 of 2026 |
| For Petitioner | S. P. Chidambaram, Paras Savla |
| For Respondent | Vikas Khanchandani |
| Bombay High Court | Read Order |