

The Goods and Services Tax Appellate Tribunal (GSTAT), Agra Bench, has said that construction services furnished to the Indian Railways do not automatically entitled for a concessional 12% GST rate only because of the receivers identity. It is crucial to provide structural proof by the taxpayers and billing breakups that their work satisfies the particular criteria for the concession.
The respondent/taxpayer, in a registered joint venture, undertook construction and related work for North Central Railway (bridges, earthwork, signaling relocation) valued at Rs ₹12,13,74,088 and paid 12% GST.
Read Also: GST Impact on the Indian Railway Network
The dispute arises in the case that the tax authorities have categorised the operation as general construction services (SAC 995423/995424) that levies the standard 18% GST rate. They had issued a demand for differential tax of ₹72,82,446, including interest and penalties.
Earlier, the first appellate authority initially quashed the Rs 72,82,446 demand in favour of the taxpayer. Afterwards, the UP State Tax Department appealed to the GSTAT.
The GSTAT has permitted the appeal of the department. It quashed the first appellate order and restored the original June 2025 adjudication order.
The major part specified in the case is that for lower tax rates, only contracting with Indian railways is not adequate. It is crucial for the taxpayers to substantiate the exact nature of the supply to claim concessional GST entries.
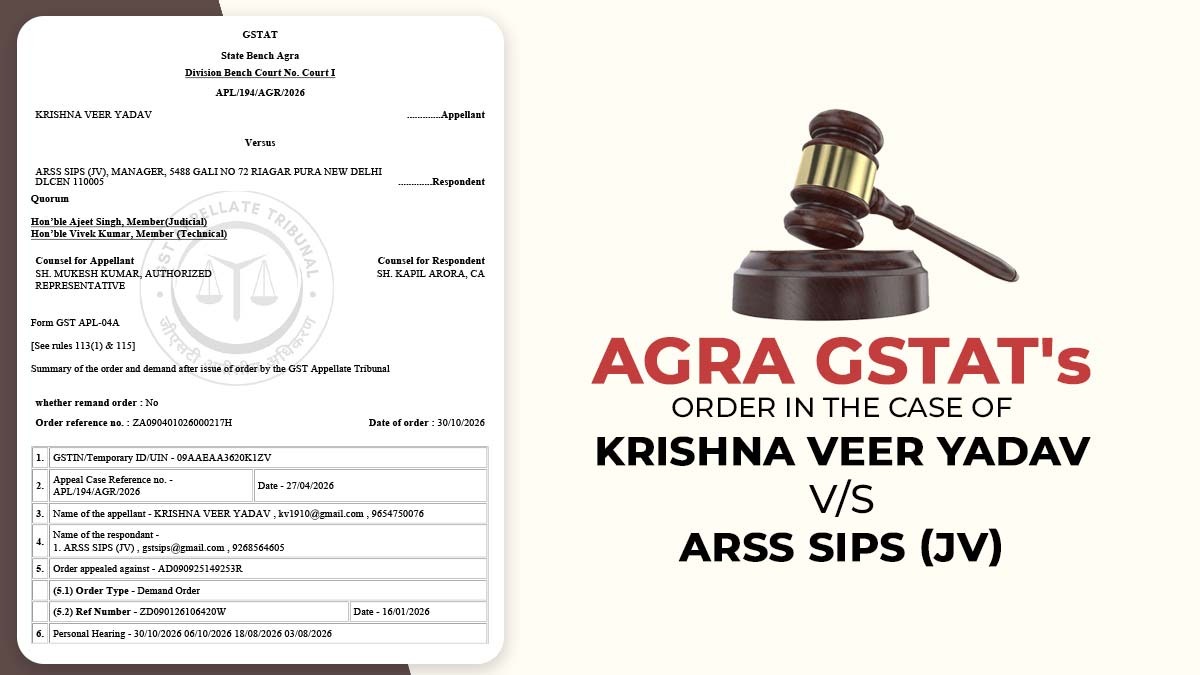
| Applicant Name | Krishna Veer Yadav vs. ARSS SIPS (JV) |
| GSTIN of the applicant | 09AAEAA3620K1ZV |
| Applicant | SH. Mukesh Kumar |
| Respondent | SH. kapil arora |
| Agra GSTAT | Read Order |