

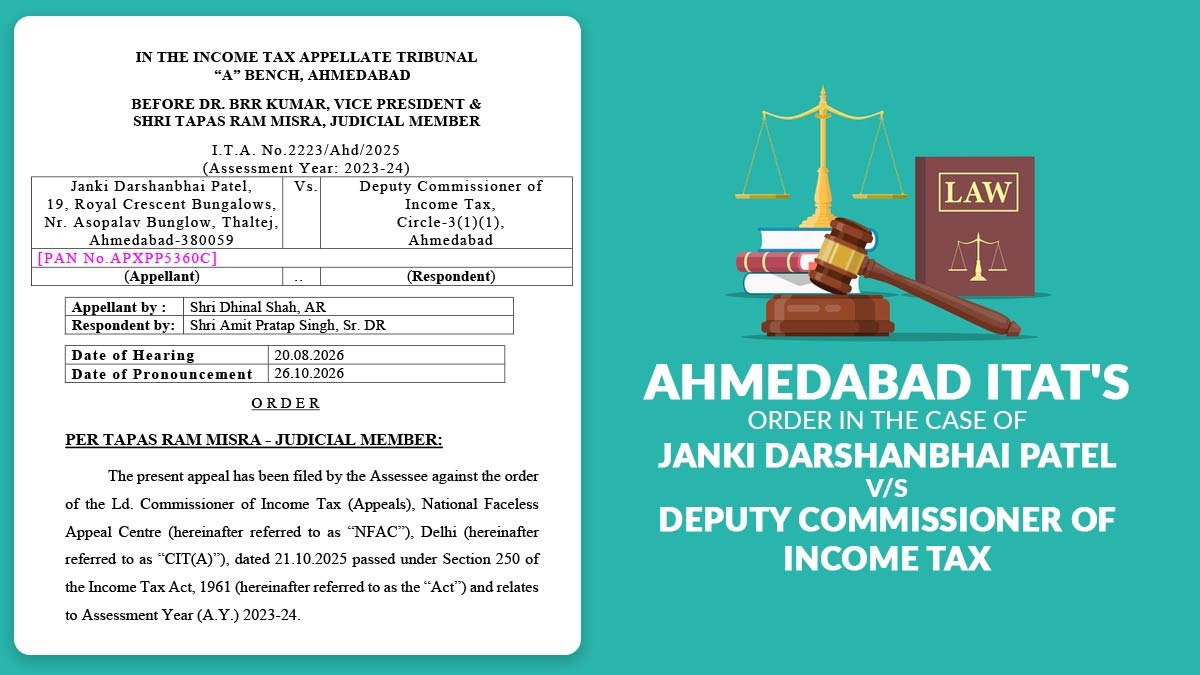
The taxpayer submitted her ITR for AY 2023-24, reporting total income of Rs 16,68,66,420. During the assessment, the AO noted the sale of non-agricultural land (converted from agricultural to other use), in which the taxpayer held a 50% share alongside a co-owner.
Under Section 2(13) of the Act, the Assessing Officer (AO) treated the sale consideration of Rs. 3,92,68,000 as business income. The AO also disallowed the deduction for the acquisition cost of Rs. 3,07,07,422 and treated the entire sale proceeds as taxable business income.
Furthermore, the AO considered the sum of Rs 49,64,279 received from business trusts, including REITs, as ‘taxable income from other sources’ and rejected the taxpayer’s claim for exemption under sections 10(23FD) and 10(23FC). The CIT(A) carried both additions and dismissed the appeal of the taxpayer.
The Tribunal reviewed Section 2(13) of the Income-tax Act, 1961, which includes within the definition of ‘business’ any venture that is like trade.
The Tribunal stated that the taxpayer had considered the land as an investment and reported the income from its sale under the head of capital gains.
The department had accepted this approach in the immediately preceding assessment year AY 2022-23. The taxpayer had also clarified that, in the year in question, all the parcels of land were sold to a single buyer, ‘ Anantbag Plantations Private Limited ‘, whereas the authorities believed that the land had been sold to several different buyers.
Accordingly, the Tribunal directed the AO to evaluate the income under the head “Capital Gains” rather than business income. In this regard, the AO has been directed to verify whether the land was held for two years before its transfer.
If so, the taxpayer’s claim for ‘long-term capital gains‘ should be accepted. Furthermore, the AO has also been instructed to examine the treatment accorded to the land in the taxpayer’s computation for Assessment Year (AY) 2024–25.
The Tribunal reviewed the combined implications of Sections 10(23FD), 10(23FC), 115UA, and 194LBA of the Income Tax Act, 1961.
It clarified that the taxation framework for business trusts operates under a pass-through mechanism, meaning that specified income keeps its original character in the hands of the unit holder.
The Tribunal noted that dividend income distributed by a business trust becomes taxable for the unit holder if the underlying special purpose vehicle (SPV) has chosen to exercise the option under Section 115BAA. On the other hand, if the SPV has not exercised this option, the specified dividend income remains exempt for the unit holder.
The taxpayer in this case had provided declarations and tax communications validating that the underlying SPVs had not chosen to exercise Section 115BAA.
Form 26AS indicated that tax was deducted on the taxable interest component, but not on the exempt dividend component. The Tribunal determined this treatment to be in line with the statutory framework.
Read Also: ITAT Ahmedabad Condones 218-Day Delay, Remands Senior Citizen’s LTCG Case for Fresh Hearing
Consequently, it concluded that the income of Rs 49,64,279 was correctly claimed as exempt and instructed the Assessing Officer (AO) to remove the addition made under the category of “Income from Other Sources.”
| Case Title | Janki Darshanbhai Patel vs. Deputy Commissioner of Income Tax |
| Case No. | I.T.A. No.2223/Ahd/2025 |
| Appellant by | Shri Dhinal Shah |
| Respondent by | Shri Amit Pratap Singh |
| Ahmedabad ITAT | Read Order |