

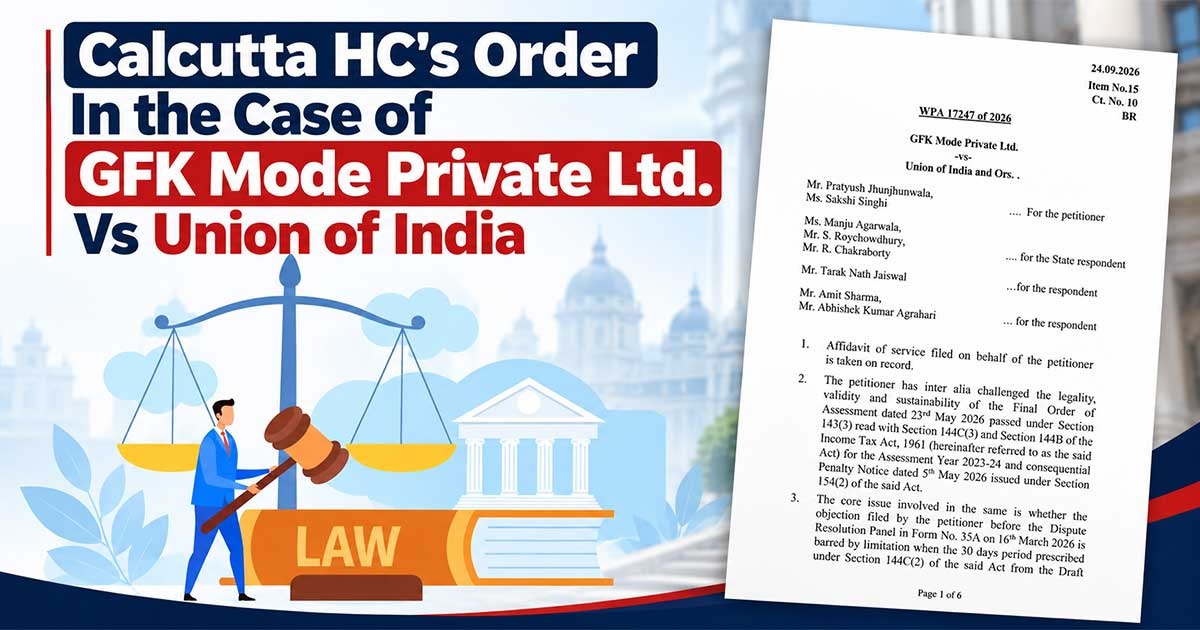
The Calcutta High Court ruled that a taxpayer’s objection to a draft income-tax assessment cannot be rejected for missing the deadline if the 30-day period expires on a Sunday and the objection is filed on the next working day.
Justice Smita Das Dey was hearing a petition filed by GFK Mode Pvt. Ltd. The company’s objection had been rejected by the Dispute Resolution Panel (DRP) as time-barred.
“Consequently, this Court holds that the objection filed by the petitioner on 16th March 2026 was well within the prescribed period of 30 days as contemplated under the statute. The rejection of the same as time-barred by respondent No. 3 is erroneous and unsustainable in law.”
The Court placed reliance on Section 10 of the General Clauses Act, which authorises an act to be accomplished on the subsequent working day when the deadline falls on a day when the office is closed.
It said that the process under section 144C of the Income Tax Act is crucial, and the assessing officer cannot pass the final assessment order without complying with the DRP procedure.
Therefore, the HC quashed the final assessment order and directed the DRP to determine the company’s objection on merits after providing it with a personal hearing. The consequential penalty proceedings were kept on hold till the determination of the DRP proceedings.
| Case Title | GFK Mode Private Ltd. Vs Union of India |
| Case No. | WPA 17247 of 2026 |
| For Petitioner | Mr Pratyush Jhunjhunwala, Ms Sakshi Singhi |
| For the State Respondent | Ms Manju Agarwala, Mr S. Roychowdhury, Mr R. Chakraborty |
| For the Respondent | Mr Tarak Nath Jaiswal, Mr Amit Sharma, Mr Abhishek Kumar Agrahari |
| Calcutta High Court | Read Order |