

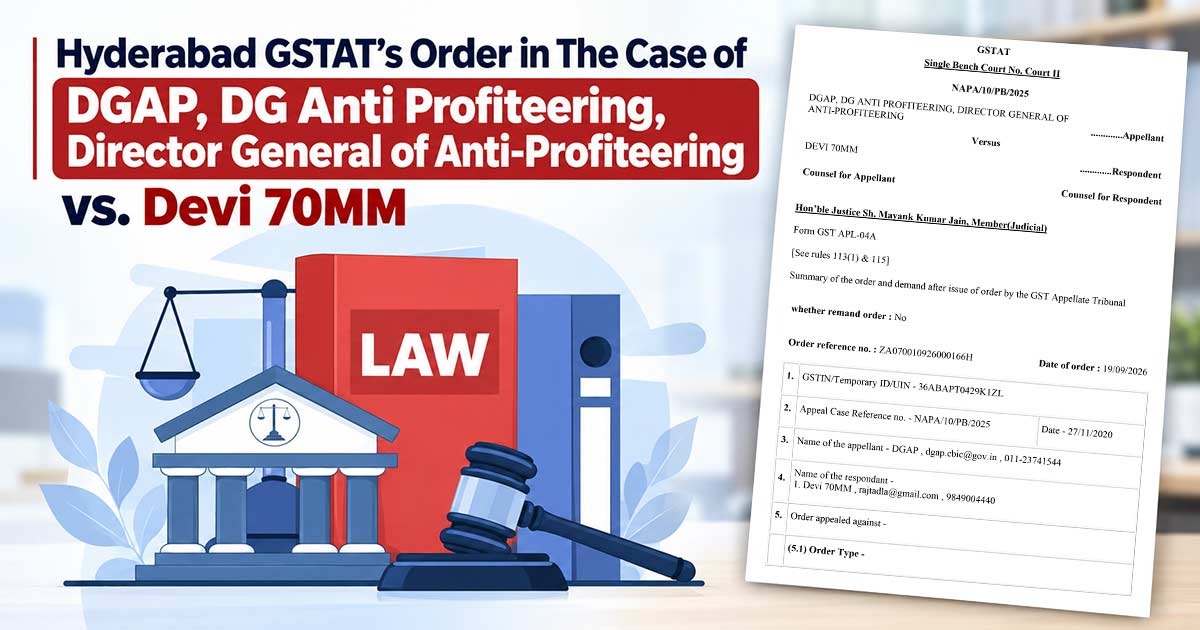
The Principal Bench of the GST Appellate Tribunal (GSTAT) directed Hyderabad-based cinema operator Devi 70MM to deposit ₹81,722 for profiteering after failing to pass on the benefit of the GST rate reduction on cinema admission tickets priced at ₹100 or below.
The GST rate on such tickets was reduced from 18% to 12% with effect from 1 January 2019.
A Single Member Bench, Judicial Member Justice Mayank Kumar Jain, stated that a cinema operator should pass on the advantage of the GST rate reduction to viewers by lessening ticket costs.
The Directorate General of Anti-Profiteering (DGAP) discovered that although Devi 70MM maintained ticket prices at ₹80 for First Class and ₹50 for Second Class, it increased the base prices following a reduction in the GST rate.
For the period from January 1 to March 10, 2019, it made an undue profit (profiteering) of ₹25,453.78 on First Class tickets and ₹56,268.62 on Second Class tickets, amounting to a total of ₹81,722 (inclusive of GST).
The tribunal found that the theatre failed to produce any evidence to prove that it had passed on the benefit of the tax reduction to customers starting from January 1, 2019.
The tribunal also rejected the argument that maintaining existing ticket prices was justified due to factors such as the nature of film screenings, weekends, holidays, and demand.
Therefore, the GST Appellate Tribunal (GSTAT) accepted the report of DGAP and asked Devi 70MM to deposit Rs. 81,722 along with 18% interest.
Half of the amount, including interest, is to be deposited in the Central Consumer Welfare Fund and the remaining half in the Telangana State Consumer Welfare Fund.
No penalty was levied.
| Case Title | DGAP, DG Anti Profiteering, Director General of Anti-Profiteering vs. Devi 70MM |
| Case No. | NAPA/10/PB/2025 |
| GSTIN | 36ABAPT0429K1ZL |
| GSTAT Hyderabad | Read Order |