

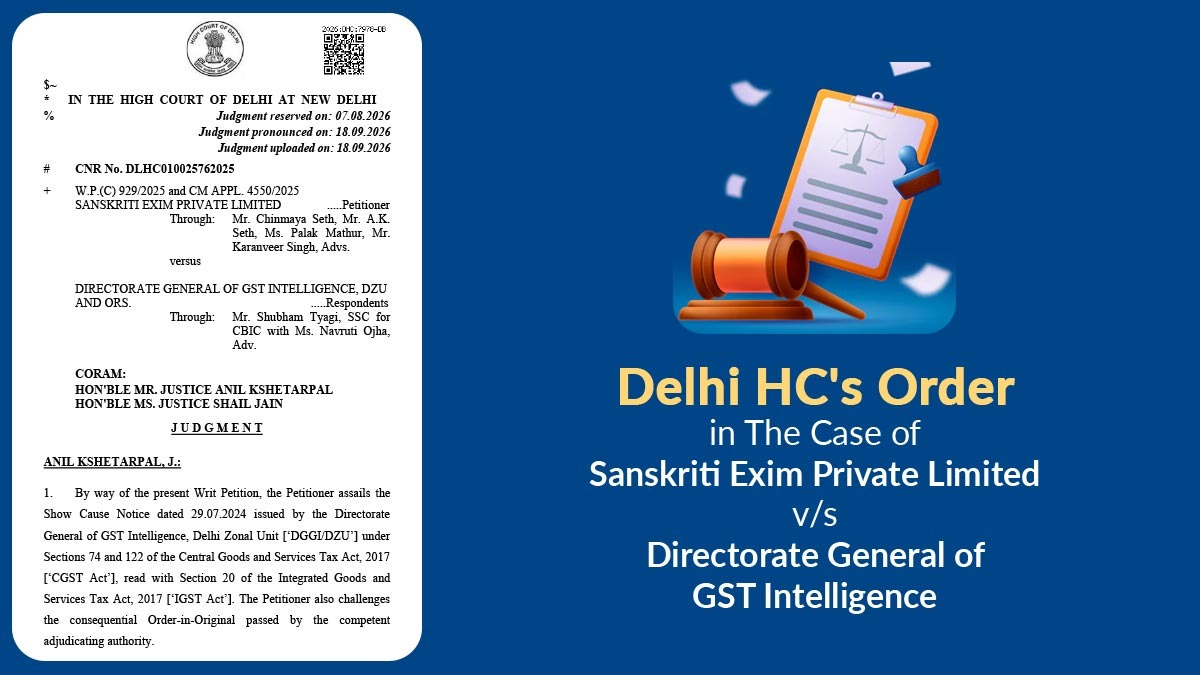
The Delhi High Court said that proceedings initiated by the DGGI are not automatically stayed due to prior State GST proceedings, even if both relate to input tax credit or pertain to the same financial period.
The applicant, Sanskriti Exim Private Limited, exported readymade garments and was investigated for alleged fake ITC taken on invoices issued via non-existent or fictitious entities.
The allegation was that such ITC was utilised for the payment of IGST on exports and the subsequent claiming of IGST refunds. A search was conducted in 2019.
State GST authorities initially issued show-cause notices under Section 73 for FY 2017–18 and FY 2018–19 regarding alleged ineligible Input Tax Credit (ITC).
Subsequently, in July 2024, the Directorate General of GST Intelligence (DGGI) issued a comprehensive notice under Section 74 proposing the recovery of ITC amounting to ₹7,81,78,980, along with applicable interest and statutory penalties.
The order-in-original confirmed the demand and imposed penalties for the alleged fake ITC and IGST refunds.
Counsel for the petitioner submitted that State GST authorities had already initiated proceedings on the alleged wrongful Input Tax Credit (ITC) for substantially the same period, rendering the subsequent DGGI action barred under Section 6(2)(b) of the CGST Act.
The petitioner further relied on inter-departmental coordination guidelines and challenged the maintainability of a consolidated Show Cause Notice (SCN) issued across multiple financial years.
Counsel for the respondent argued that the State proceedings related to specific irregularities concerning Input Tax Credit (ITC), whereas the DGGI proceedings stemmed from an independent investigation into ITC fraudulently obtained from 20 non-existent supplier companies and its utilisation against IGST liabilities and for claiming refunds. He contended that a mere similarity in facts does not render the matters identical.
The Division Bench, Justice Anil Kshetrapal and Justice Shail Jain, said that “The expression ‘same subject matter’ is, therefore, of central significance. The mere fact that two proceedings arise out of the affairs of the same assessee, concern the same general period, or involve ITC cannot, by itself, establish that the two proceedings concern the same subject matter.”
The Court observed that the facts underlying the State proceedings and the DGGI proceedings were distinct, and that mere similarities in transactions did not imply that the liabilities or the nature of the rule violations were identical.
The Court further held that a notice issued under Section 74, covering multiple financial years, could not be deemed to be without jurisdiction solely on that ground. The writ petition was dismissed.
| Case Title | Sanskriti Exim Private Limited vs. Directorate General of GST Intelligence |
| Case No. | W.P.(C) 929/2025 and CM APPL. 4550/2025 |
| Counsel for Appellant | Mr Chinmaya Seth, Mr A.K. Seth, Ms Palak Mathur, Mr. Karanveer Singh |
| Counsel For Respondent | Mr Shubham Tyagi, Ms Navruti Ojha |
| Delhi High Court | Read Order |