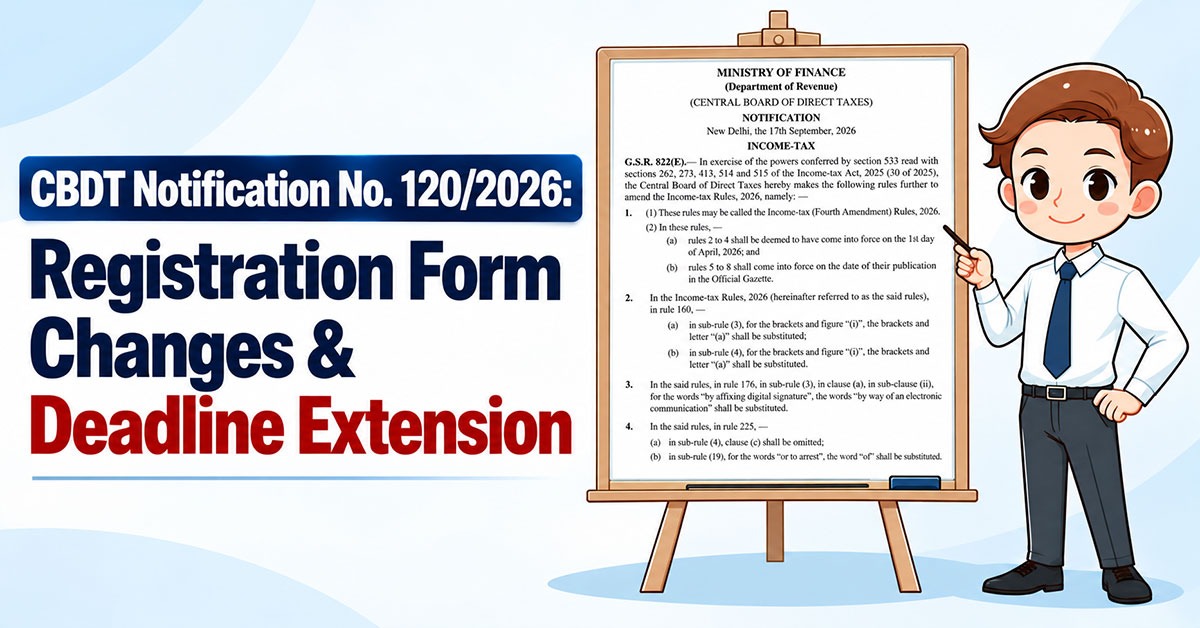


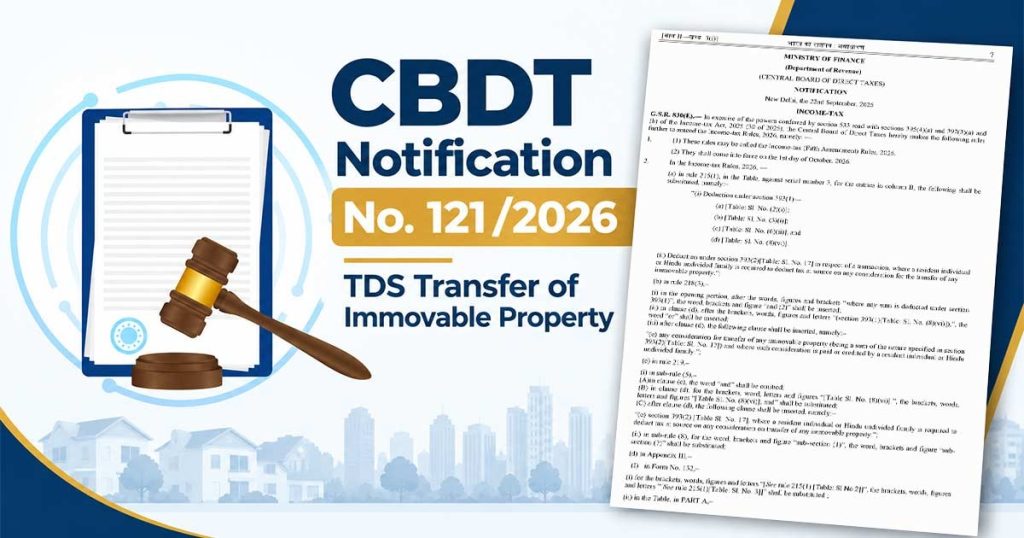
The Central Board of Direct Taxes (CBDT) has notified the Income-tax (Fifth Amendment) Rules, 2026. Under this, amendments have been made to the Income-tax Rules, 2026, particularly regarding matters related to Tax Deducted at Source (TDS) on immovable property transactions.
The Ministry of Finance, Department of Revenue, issued the notification on September 22, 2026, and the amended rules will come into effect from October 1, 2026.
The revisions are crucial for taxpayers, property buyers, sellers, and tax professionals managing TDS compliance for property transfers.
TDS Rules for Immovable Property Transactions Updated
In the revised norms, Section 393(2) of the Income-tax Act, 2025 has been incorporated into pertinent TDS compliance provisions.
The notification is concerned with TDS in transactions that involve the transfer of immovable property where a resident individual or Hindu Undivided Family (HUF) is required to deduct tax on the consideration paid or credited for the property.
The revision has been shown in the mentioned forms used for reporting TDS.
Updated Form 141
One of the revisions is the amendment to Form No. 141, which is used for providing challan-cum-statements concerning TDS.
Now the heading of Form 141 has been expanded to include deductions under both Section 393(1) and Section 393(2).
Read Also: Easy Explanation on TDS for Property Sale by NRI
More importantly, a new Schedule E has been added to Form 141 for reporting TDS related to the amount paid for the transfer of immovable property covered under Section 393(2).
What Details Will Schedule E Capture?
Detailed information regarding property transactions must be provided under the recently introduced Schedule E.
Among other things, taxpayers will be required to provide the following information:
- Address of the immovable property
- Type of property, such as land or building
- Details of all buyers
- PAN and names of buyers
- Proportion of sale consideration payable by each buyer
- Details of all sellers or deductees
- Seller’s PAN, where available
- Seller’s residential status
- Contact details and email ID
- Overseas address in case of a non-resident seller
- Tax Residency Certificate details, where applicable
- Tax Identification Number of the non-resident seller
- Agreement and registration dates
- Stamp duty value of the property
- Total sale consideration
- Details of whether payment is made in lump sum or instalments
Recommended: Easy Process to Pay TDS on Property Purchases > 50 Lakh
The form needs transaction-level information along with the amount on which TDS is applicable, the TDS rate, amount deducted, and date of deduction.
Additional Compliance for Non-Resident Sellers
The notification mentions additional information requirements where the seller or deductee is a non-resident.
The contact number, email ID, and address in the country or specified territory where the deductee is resident should be provided, irrespective of whether the non-resident has a PAN.
Where a PAN is not available, it is mandatory to provide specific identification details under Rule 217 to ensure that tax is not deducted at a higher rate.
This form also includes a provision to provide information regarding the seller’s tax residency certificate and tax identification number, where applicable.
Form 132 Also Updated
The CBDT has changed Form 132 to include transactions involving the transfer of immovable property by a non-resident to a resident individual or HUF.
The updated form has a corresponding entry for these property transfers, and specific fields have been changed to show the updated reporting structure.
TDS Amount Will Include Surcharge and Cess Where Applicable
The notification specifies that the TDS amount declared in the related form will include surcharge and cess, wherever applicable.
Additionally, where there is more than one deductor, a separate form must be filled out for each. The notification also states that, to the extent possible, some information in the form will be pre-filled.
Implementation Date
The Income-tax (Fifth Amendment) Rules, 2026 will come into effect from October 1, 2026.
Therefore, for property buyers and sellers as well as tax professionals, the updated Form 141 and the new Schedule E will become significant for transactions falling under the revised TDS rules applicable from this date.
Key Insights
A recent CBDT notification expands the scope of TDS reporting for specific immovable property transactions and introduces necessary amendments to Forms 132 and 141.
The inclusion of Schedule E in Form 141 means that, for the purpose of reporting TDS related to a property, more detailed information must be provided regarding the property, buyers, sellers, consideration (value), instalments, and the tax deducted.
W.e.f. October 1, 2026, taxpayers and professionals managing property transactions must analyse the updated reporting requirements and ensure that the crucial transaction and taxpayer information are available for compliance.
Read Official Notification