

The Delhi High Court has dismissed the Income Tax Department’s appeal against a decision made by the Income Tax Appellate Tribunal (ITAT). This decision concerned a search assessment for the assessment year 2006-07, which was set aside due to limitations.
The court referenced its earlier ruling in the case of Principal Commissioner of Income Tax, Central-1, Delhi v. Sanjay Jain. In that ruling, the court stated that the time limit for completing search assessments cannot be extended solely by referring to a foreign tax authority if the information requested is not permitted under the applicable tax treaty.
Before the Division Bench of Justices Dinesh Mehta and Rajneesh Kumar Gupta, the matter is relevant to an assessment specified against the respondent after an investigation at her residential premises in August 2011.
It was purported by the Income Tax Department that she maintained a bank account with HSBC, Geneva, Switzerland, and made an addition of ₹1.59 crore to her income on the basis of information related to the account.
The respondent had contested the assessment as being barred by limitation before the ITAT.
The Revenue argued that the limitation period had been extended by one year under Explanation (ix) to Section 153B of the Income Tax Act, as a reference had been sent to Swiss tax authorities seeking information under the India-Switzerland Double Taxation Avoidance Agreement (DTAA).
ITAT had discovered that the reference of the department was inappropriate insofar as it asked for information for the duration April 1, 1995 to March 31, 2012.
It was stated that under the 2011 protocol, the amended Article 26 of the India-Switzerland DTAA permitted the exchange of information only for financial years commencing on or after April 1, 2011. However, the information sought by the Department pertained to a much longer period, starting from April 1, 1995.
The tribunal observed that by the time it heard about the appeal in 2023, the revenue had not obtained the information from the Swiss authorities related to the transactions predating April 1, 2011. It said that the revenue could not rely on the invalid reference to assert an extension of the limitation period.
The Income Tax Department contests the order of the ITAT and approached the HC u/s 260A of the Income Tax Act.
The counsel for Narang in the hearing has said that the appeal of the revenue should be dismissed in light of the High Court’s subsequent judgment in Sanjay Jain.
The counsel for the revenue failed to argue this position.
Consequently, the HC dismissed the appeal.
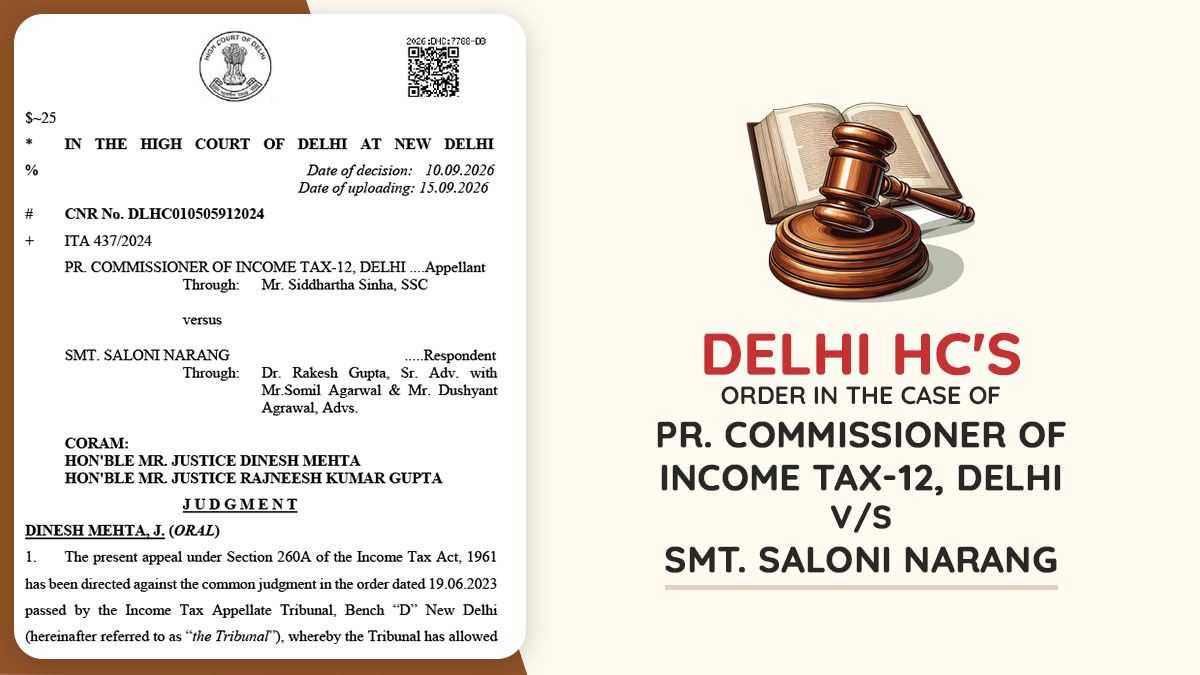
| Case Title | Pr. Commissioner of Income Tax-12, Delhi vs. Smt. Saloni Narang |
| Case No. | CNR No. DLHC010505912024 |
| For Petitioner | Mr. Siddhartha Sinha, SSC |
| For Respondent | Dr. Rakesh Gupta, Sr. Adv. with Mr.Somil Agarwal & Mr. Dushyant Agrawal, Advs |
| Delhi High Court | Read Order |