

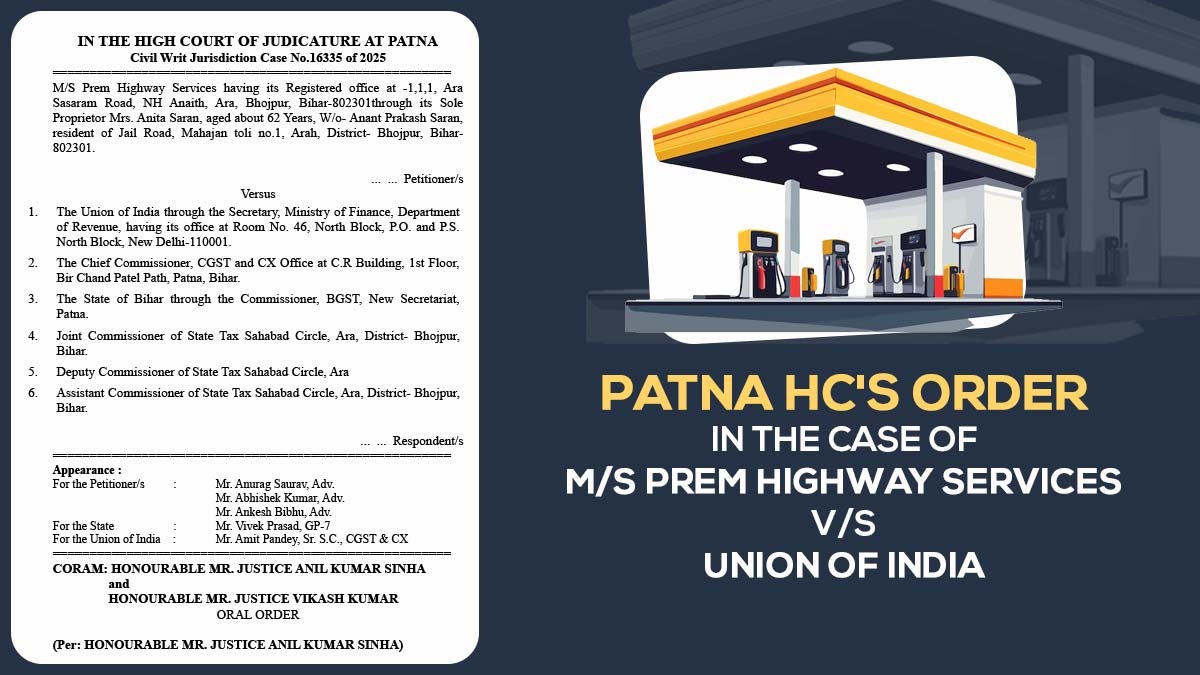
The Patna High Court has set aside the tax obligation of Rs 1,25,71,936 on M/s Prem Highway Services, noting that the adjudicating authority might have levied the GST liability on Motor Spirit and HSD, which do not fall under the purview of GST.
A division bench comprising Justices Anil Kumar Sinha and Vikas Kumar intervened in the assessment order issued on April 29, 2024. The bench held that the imposition of GST on non-GST goods was the core issue in the matter. The case was remanded to the concerned authority for fresh adjudication in accordance with the law.
The applicant, Prem Highway Services, a dealer in petroleum products, has asked for relief before the High Court from the assessment order concerning which a tax liability of Rs. 1.25 crore was charged upon it.
It was submitted that the applicant deals in the sale of motor spirit and HSD, which do not fall within the ambit of GST and are subject to tax under the VAT regime.
Recommended: GST Impact on Petroleum Products in India
It was claimed that although Section 9(2) of the CGST Act provides for the levy of tax on these petroleum products through the issuance of a notification, no such notification has been issued to date.
In addition to filing their return for the FY 2018-19, the applicant put an allegation that the assessing authority was acting beyond its jurisdiction by assessing tax on invoices related to motor spirit and HSD.
Opposing the writ petition, the State argued that the applicant neither responded to the ‘show-cause notice‘ issued by the assessing authority nor submitted any documents to prove that the invoices in question related solely to non-GST petroleum products. Thereafter, the State contended that the impugned assessment order clearly indicates that tax was also levied on certain GST-attracting items.
The Bench stated that the applicant had filed its Registration Certificate and tax invoices before the Court in support of its claim. The Court had gone through the record and said that Motor Spirit and HSD were non-GST items and GST had been charged on them.
The Court observed that taxing items not covered by GST would fundamentally undermine the issue at hand. As a result, there seemed to be a clear lack of authority to impose GST on such goods. Therefore, it was important for the Court to intervene regarding the assessment order, given the delay in addressing the matter.
Therefore, the assessment order was set aside, and the case was returned for fresh consideration. It was ordered that the applicant’s appearance is mandatory before the adjudicating authority within 20 days, along with all related documents and a reply to the Show Cause Notice (SCN).
Thus, the Bench stated that the authority must issue a notice and provide an opportunity for a personal hearing before issuing a fresh assessment order within two months of the applicant’s appearance.
| Case Title | M/S Prem Highway Services Vs Union of India |
| Case No. | Civil Writ Jurisdiction Case No.16335 of 2025 |
| For the Petitioner | Mr Anurag Saurav, Mr Abhishek Kumar, Mr Ankesh Bibhu |
| For the State | Mr Vivek Prasad |
| For the Union of India | Mr Amit Pandey |
| Patna High Court | Read Order |