

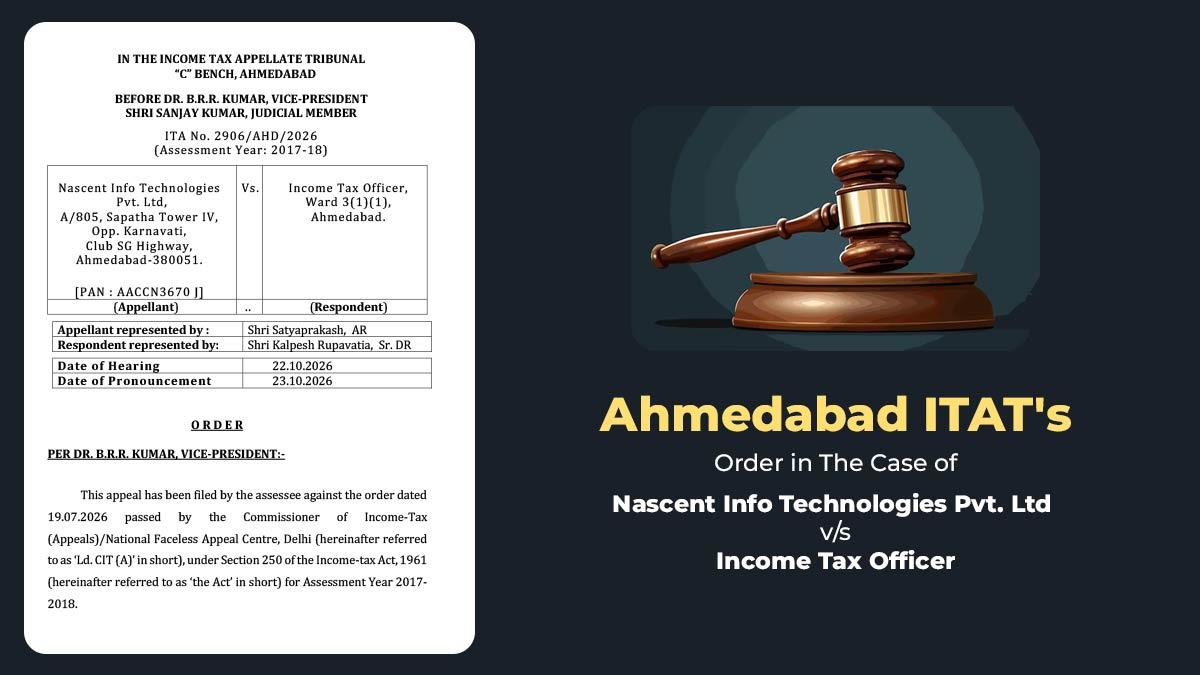
The Income Tax Appellate Tribunal (ITAT), Ahmedabad, has removed a ₹4.42 lakh penalty levied on Nascent Info Technologies Pvt. Ltd. for income misreporting.
It states that the mere disallowance of employees’ contributions to the Provident Fund (PF) and Employees’ State Insurance (ESI) does not, in itself, amount to misreporting of income.
The bench of Vice-President Dr. B.R.R. Kumar and Judicial Member Sanjay Kumar stated that the revenue should specify that the case comes under certain categories of misreporting u/s 270A(9) of the Income Tax Act, 1961.
This provision clarifies the circumstances under which the under-reporting of income with the intent of attracting a higher penalty is deemed as “misreporting of income.”
For AY 2017-18, the company had submitted its return reporting an income of Rs 6.14 crore. In the scrutiny assessment, the assessing officer did not allow the employees’ contributions to the Provident Fund (PF) and Employees’ State Insurance (ESI) of Rs 7,16,611, determining the total income at ₹6.21 crore.
Thereafter, the assessing officer levied a penalty of Rs 4,42,866 u/s 270A, considering the disallowance as income misreporting. The penalty was upheld by the Commissioner of Income Tax (Appeals), National Faceless Appeal Centre, Delhi.
The company before the tribunal contested the penalty levied on the disallowance.
The Tribunal placed reliance on its coordinate bench’s decision in the case of ‘Hero Mulchand Tanwani vs. ITO’. That decision held that the mere disallowance of a claim cannot, by itself, be construed as ‘misreporting’ u/s 270A. The Revenue Department must prove that the case falls within one of the categories specified u/s 270A(9).
Applying this principle, the Tribunal stated that the material on record does not establish that the company’s case falls under any of the specified categories of ‘misreporting’. The Tribunal held that the disallowance of employees’ PF/ESI contributions is, in itself, not sufficient to justify the imposition of a penalty.
“In the present case, the penalty has been levied on account of the disallowance of employees’ contribution towards PF and ESI. However, the material available on record does not establish that the assessee’s case falls within any of the categories of misreporting specified under Section 270A(9) of the Act. The mere disallowance of the claim, by itself, is not sufficient to justify the levy of penalty for misreporting”, the Court stated.
Therefore, the Tribunal quashed the CIT(A)’s order and removed the penalty of Rs 4,42,866.
It permitted the appeal of the company without separately adjudicating the remaining grounds, which had become academic.
| Case Title | Nascent Info Technologies Pvt. Ltd. vs. Income Tax Officer |
| Case No. | ITA No. 2906/AHD/2026 |
| For Petitioner | Shri Satyaprakash, AR |
| For Respondent | Shri Kalpesh Rupavatia, Sr. DR |
| ITAT Ahmedabad | Read Order |