

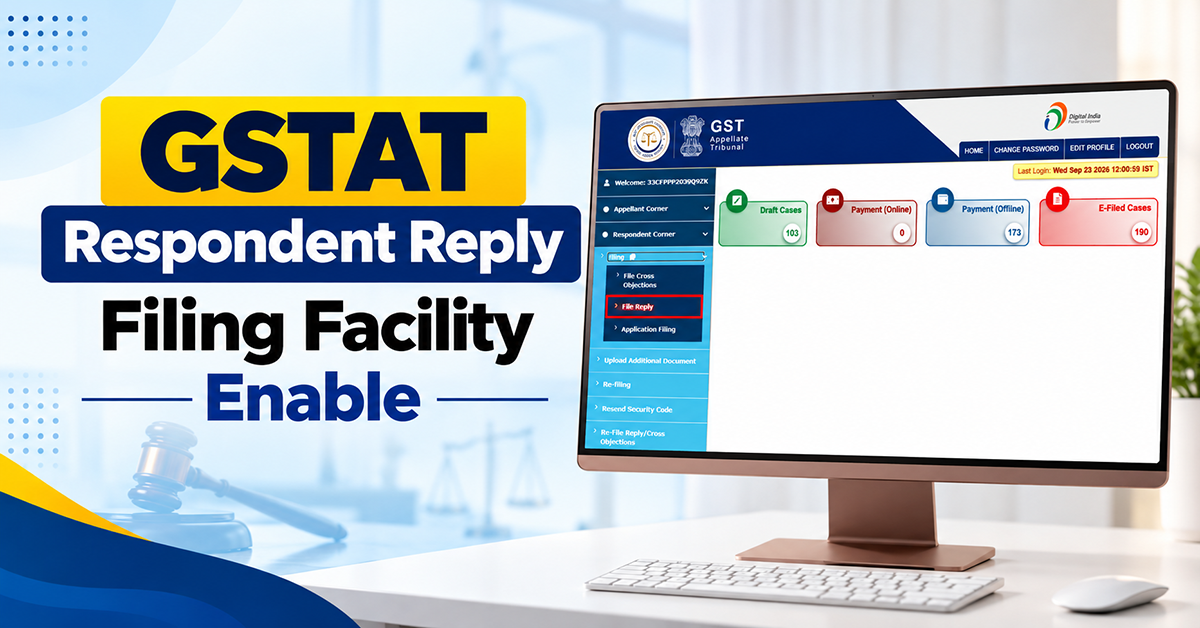
On September 29, 2026, a Standard Operating Procedure (SOP) for online filing of a Reply by a Respondent was made available on the GSTAT filing portal. It was introduced to ease the process for taxpayers and departmental respondents appearing before the GSTAT.
The facility helps respondents file their response to an appeal without filing cross-objections in Form GST APL-06. The SOP specifies that it mentions the method for respondents to submit a reply, when needed, to an appeal submitted against them.
This facility derives its legal basis from Rule 36 of the ‘Goods and Services Tax Appellate Tribunal (Procedure) Rules, 2025′. These rules were notified by the Department of Revenue, Ministry of Finance, via Notification No. G.S.R. 256(E) dated April 24, 2025, issued in exercise of the powers conferred u/s 111 of the ‘Central Goods and Services Tax Act, 2017’.
Under Rule 36(1), each respondent has the opportunity to file a reply to the petition or application, along with copies of relevant documents. This can be done either in person or through an authorised representative and must be submitted to the Registrar in the manner specified by the Tribunal within one month of receiving the petition or application.
Read Also: GSTAT Orders Hyderabad-based Cinema Operator to Deposit Rs. 81,722 for Not Passing On GST Rate Reduction Benefit
Additionally, the Rule requires that a copy of the reply and supporting documents be promptly served on the applicant.
Rule 36(2) states that upon receiving the respondent’s reply or documents, the applicant must specifically admit, deny, or refute the facts presented by the respondent. The applicant may also include any additional facts that they deem necessary.
The procedure is different from the statutory facility of filing cross-objections. Rule 35 of the GSTAT (Procedure) Rules, 2025 deals separately with registration and numbering of the mentioned forms of cross-objections, applications, and other proceedings.
Accordingly, the new portal workflow enables a respondent who merely wishes to oppose or respond to the grounds raised in the appeal to file their reply without having to resort to the ‘cross-objection’ process.
Why GSTAT Proceedings Matter
The introduction of this dedicated Reply-filing functionality offers clear procedures for respondents who do not intend to file cross-objections but still want to submit their defence, factual submissions, and supporting documents. This functionality implements the separate procedure outlined in Rule 36 of the GSTAT (Procedure) Rules, 2025, and allows for electronic filing directly through the Respondent Corner of the GSTAT Portal.
This development is important because a Reply under Rule 36 and a cross-objection are two distinct procedural remedies. Respondents are required to consider whether they simply want to respond to the appellant’s grounds with a Reply, or if they wish to seek independent relief through a cross-objection, in accordance with the relevant GST provisions and rules.
Read Official Notification