

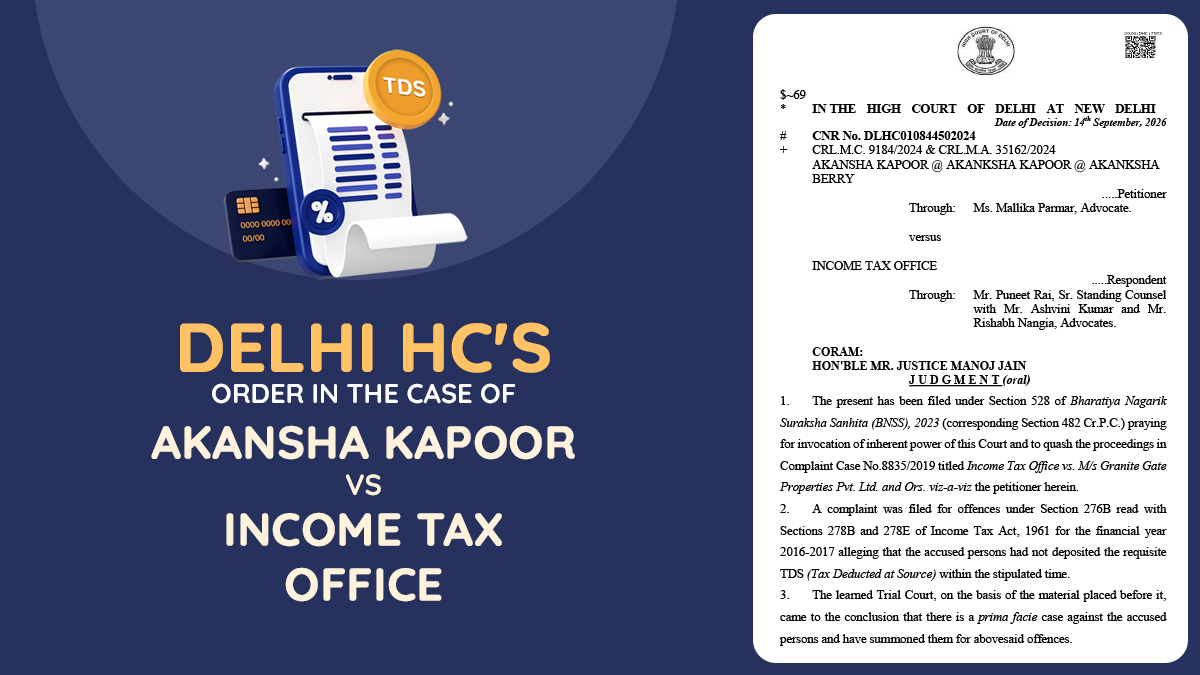
The Delhi High Court quashed criminal proceedings related to TDS. The Court found that the prosecution’s case was based on the erroneous assumption that the petitioner was a director and the principal officer of the accused company.
The Income Tax Department’s complaint against Akansha Kapoor (petitioner) alleged that she did not deposit the required Tax Deducted at Source within the stipulated period during FY 2016-17.
Based on the material placed before it, the trial court found a prima facie case and issued summons to the accused for the alleged offences.
U/S 279(1) of the Income Tax Act has been issued to the petitioner on the claim that she was a director of the accused company. Under Section 279(1), the sanction granted specified her as a director of the deductor company. The criminal complaint shows her as a director and as the principal officer.
U/s 528 of the Bharatiya Nagarik Suraksha Sanhita, 2023, corresponding to Section 482 CrPC, the applicant approached the Court and asked to set aside the criminal proceedings insofar as they relate to her.
The counsel for the revenue before the Court acknowledged that the applicant had never been a director of the accused company.
The Bench, Justice Manoj Jain said that, “Show Cause Notice, order passed under Section 2(35) of Income Tax Act, sanction order under Section 279(1) of Income Tax Act and complaint, all are based on the premise that the petitioner herein was Director in the accused company and, therefore, she has been projected as Principal Officer.”
The Court said that “Clearly, her prosecution, while being treating her as Director of the accused company, is fallacious and thus not sustainable.”
The petition was permitted, and the prosecution was set aside only to the extent concerning the petitioner.
| Case Title | Akansha Kapoor vs Income Tax Office |
| Case No. | CNR No. DLHC010844502024 |
| Counsel For Petitioner | Ms. Mallika Parmar |
| Counsel For Respondent | Mr Puneet Rai, Mr Ashvini Kumar and Mr Rishabh Nangia |
| Delhi High Court | Read Order |