

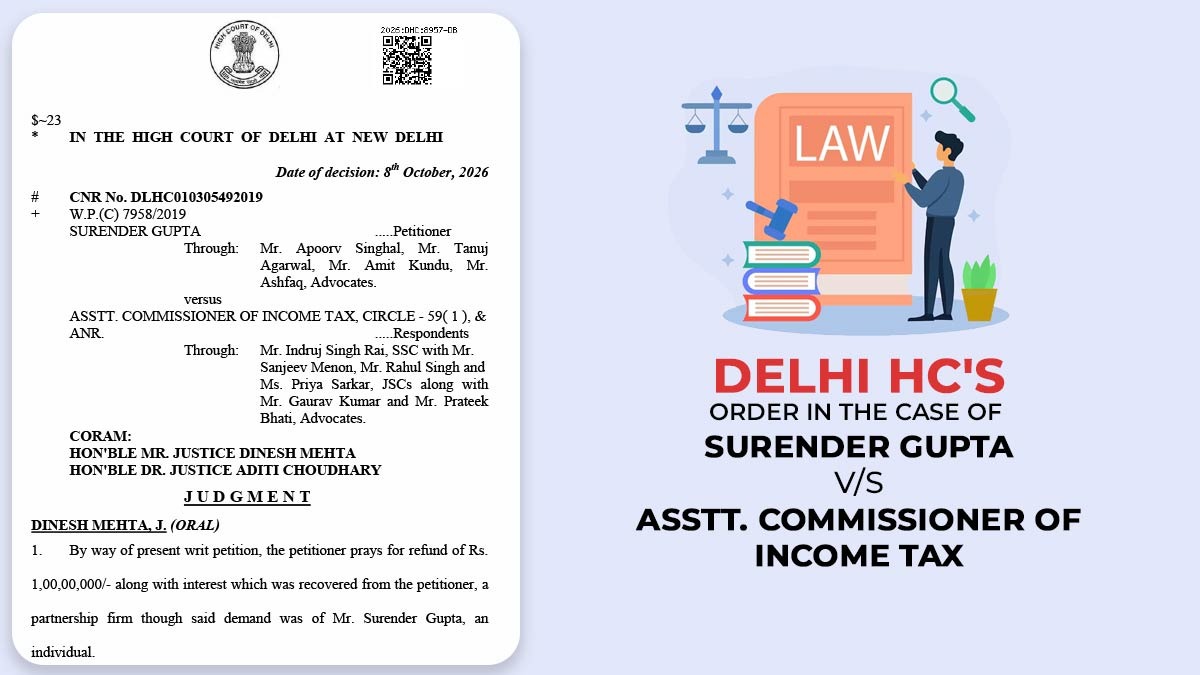
In the case of Surender Gupta V/s Assistant Commissioner of Income Tax (W.P.(C) 7958/2019), the Delhi High Court dismissed a partnership firm’s petition seeking a refund of ₹1 crore. The amount had been paid by the firm toward the outstanding individual income-tax dues of one of its partners.
The dispute involved a business initially operating as a sole proprietorship under the name M/s Surender Gupta, which later added partners through a partnership deed. During assessment proceedings, a tax liability arose against an individual partner. To meet this demand, the firm tendered payment amounting to ₹1 crore via Fixed Deposit Receipts (FDRs) and a cheque.
Later, the firm approached the High Court seeking a refund of the amount, alleging that the tax department had coercively recovered the money and arguing that a partnership firm should not be held liable for an individual partner’s personal tax obligations.
The court examined the circumstances of the payment and concluded that the tendering of FDRs and a cheque could not be characterised as a forceful recovery or coercion merely because bank accounts faced attachment pressures.
Also Read: Bombay HC Rules IT Department Need Not Wait for Certified Copy of Digitally Signed Order
The court noted that the firm failed to establish that the official communication regarding the change in its business constitution (from proprietorship to partnership) had been properly notified to the tax authorities before the payment was made.
Crucially, the bench observed that when a firm pays an amount connected with a partner’s individual tax liability, any resulting grievance between the business entity and the partner is essentially an inter se (internal) dispute.
Ruling that a writ court under Article 226 is not the appropriate forum to resolve internal financial settlements or partnership disputes, the High Court found no illegality, error, or arbitrariness in the Revenue Department’s actions.
Finding the petition devoid of merit, the Delhi High Court dismissed the writ petition seeking the ₹1 crore refund with interest, leaving the partners to resolve their internal financial liabilities through appropriate civil remedies rather than tax writ proceedings.
| Case Title | Surender Gupta Vs Asstt. Commissioner of Income Tax |
| Case No. | W.P.(C) 7958/2019 |
| For Petitioner | Mr Apoorv Singhal, Mr Tanuj Agarwal, Mr Amit Kundu, Mr Ashfaq |
| For Respondent | N. Venkataraman, T.Niranjan, Y.N.Vivekananda, Anup Koushik Karavadi |
| Delhi High Court | Read Order |