

Rainbow Foundation Ltd. is engaged in real estate development and sale of apartments. After search and seizure operations conducted on 21 April 2016, the firm was subjected to assessment proceedings u/s 153C of the Income Tax Act, 1961 for AY 2012-13.
In the search, loose sheets and other documents were seized from the premises of R.V. Raajah, who allegedly acted as a broker in the sale of the Padmanabha Theatre property by Rainbow Foundation Ltd. to Rathnapuri Constructions Pvt. Ltd.
The statement was recorded u/s 132(4), in which Raajah said that the total consideration for the property was Rs 27 crore, of which Rs 13.53 crore was paid in cash, and the remaining amount was paid via cheque.
The AO has completed the assessment u/s 143(3) read with Section 153C on 31 December 2018, evaluating the total income at Rs 14,06,35,460 after adding Rs 13.53 crore as undisclosed on-money consideration. However, CIT(A) deleted the addition.
The Tribunal said that the CIT(A) had moved on a wrong factual assumption concerning the date and existence of the satisfaction note recorded by the AO of the searched person.
The Tribunal specified that once the AO of the person subjected to a search records their satisfaction that the seized material pertains to a third party, and such material, along with the satisfaction note, is handed over to the AO of that third party, jurisdiction under Section 153C can be considered validly established. In the notice issuance stage, conclusive proof of undisclosed income escaping assessment is not needed.
The Tribunal discovered that CIT(A) had not considered the evidentiary value of the statements recorded u/s 132(4) along with the seized documents showing receipt of the alleged on money consideration.
Accordingly, the Tribunal overturned the findings of the CIT(A), restored the assessment order, which included an addition of Rs 13.53 crore, and allowed the Revenue’s appeal.
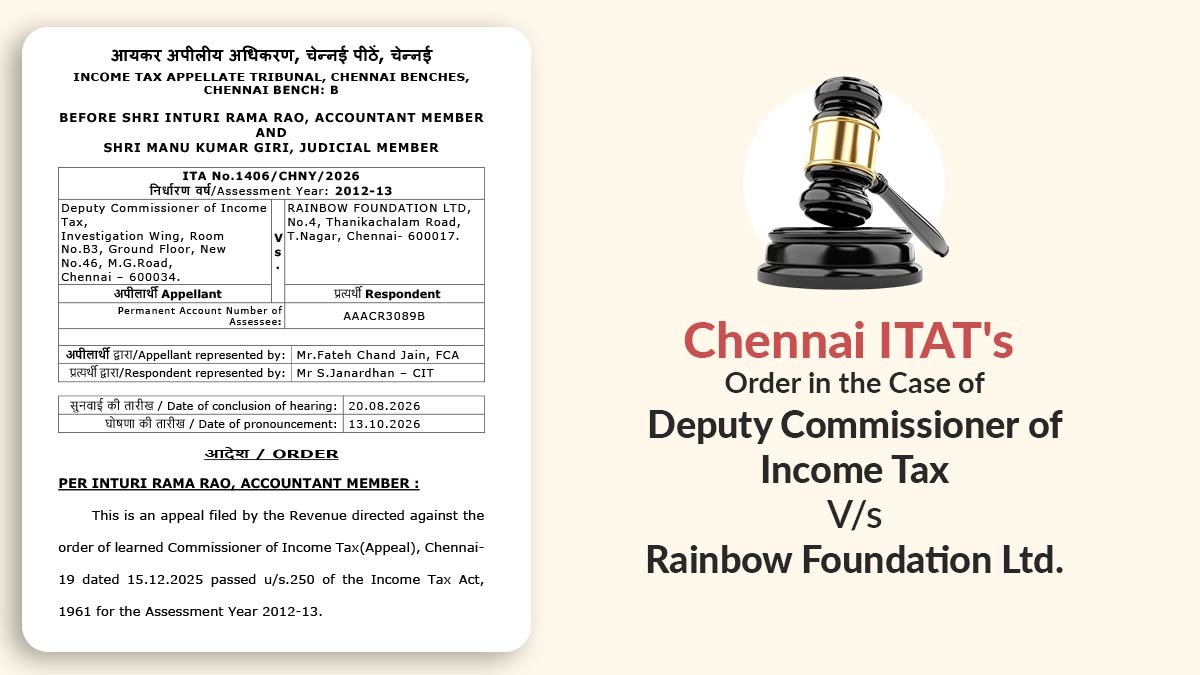
| Case Title | Deputy Commissioner of Income Tax vs Rainbow Foundation Ltd |
| Case No. | ITA No.1406/CHNY/2026 |
| For Petitioner | Mr.Fateh Chand Jain, FCA |
| For Respondent | Mr S.Janardhan – CIT |
| ITAT Chennai | Read Order |