

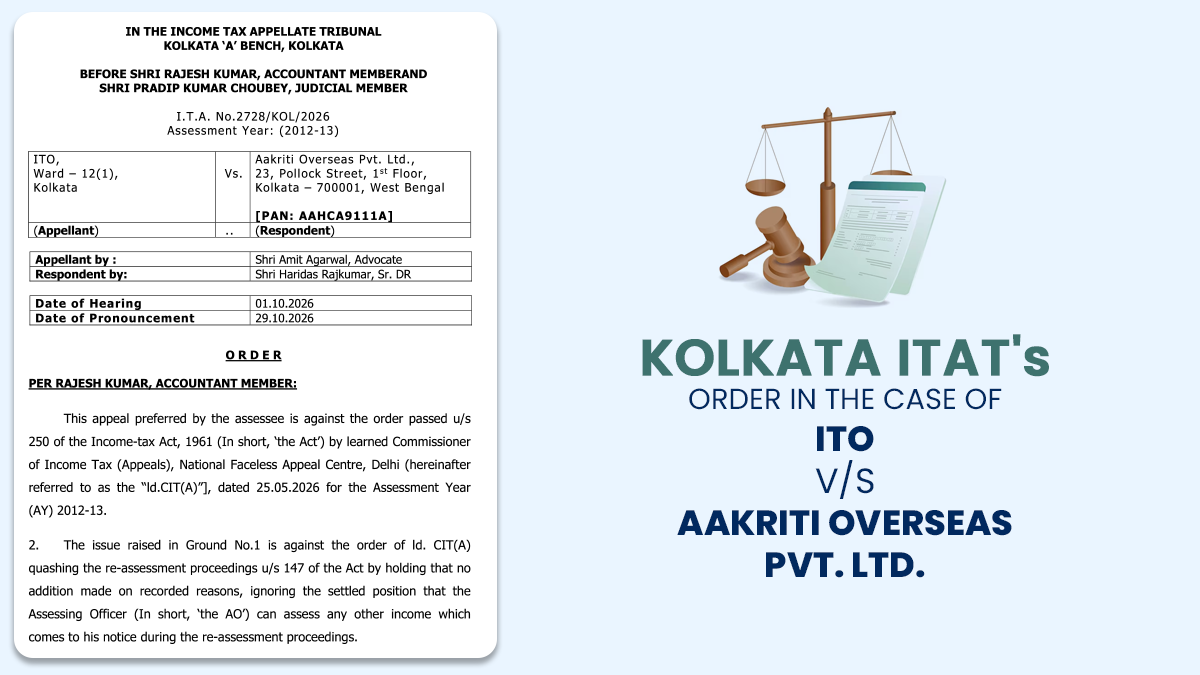
The Income Tax Appellate Tribunal (ITAT), Kolkata ‘A’ Bench, has dismissed the Revenue Department’s appeal in the case of ‘Aakriti Overseas Private Limited’ for the assessment year 2012-13.
The Tribunal held that an Assessing Officer (AO) cannot make an addition to income regarding an issue that was not part of the reasons recorded for reopening the assessment, especially when no addition has been made in relation to the original issue(s) for which the assessment was reopened.
The Revenue Department had challenged the order dated May 25, 2026, passed by the Commissioner of Income Tax (Appeals), National Faceless Appeal Centre (CIT(A)).
The case was reopened u/s 147 of the Income Tax Act, 1961, for which a notice was issued on March 29, 2019, u/s 148. The basis for reopening the case was information that ‘Akriti Overseas’ had received Rs 35 lakh from ‘Quest Infrastructure Private Limited’ and Rs 10 lakh from ‘Starlight Vintrade Private Limited’.
The taxpayer filed a return reporting ‘nil’ (zero) income and subsequently responded to the notices issued by the AO (Assessing Officer).
However, during the reassessment proceedings, the Assessing Officer (AO) did not make any additions in respect of the two transactions that had formed the basis for reopening the assessment.
Instead, the AO considered the sum of Rs 2,04,79,500 received as share premium as an ‘unexplained cash credit’ u/s 68 of the Act and added this amount to the taxpayer’s income.
CIT(A), on appeal, has removed the addition, noting that the AO failed to make any addition on the issue for which the assessment was originally reopened; he could not move to make an addition on a distinct issue.
Dissatisfied with this decision, the Revenue Department approached the ITAT. They claimed that during reassessment proceedings, the Assessing Officer (AO) has the authority to evaluate any other income that comes to their notice, even if it is unrelated to the original grounds for reopening the case.
After considering the arguments from both sides, the Tribunal concurred with the view of the CIT(A). It noted that the reassessment proceedings were initiated primarily to examine an alleged sum of ₹35 lakh received from ‘Quest Infrastructure Private Limited’ and ₹10 lakh received from ‘Starlight Vintrade Private Limited’.
Read Also: Calcutta HC Upholds ITAT Order Removing ₹4 Cr Addition in Reassessment Case
However, the Assessing Officer (AO) did not make any additions in relation to these specific transactions; instead, he added an amount of ₹2.04 crore under the head of ‘share premium’.
The tribunal placed reliance on the rulings of the Bombay High Court in CIT vs. Jet Airways (India) Ltd. (2011) 331 ITR 236 and the Delhi High Court in Ranbaxy Laboratories Ltd. vs. CIT (2011) 336 ITR 136.
It referred to the judgment of the Calcutta High Court in CIT vs. Infinity Infotech Parks Ltd., ITAT No. 60 of 2014, dated September 10, 2014.
After these judicial precedents, the Tribunal said that the Commissioner of Income Tax (Appeals) CIT(A) had correctly deleted the ‘addition’, and it found no reason to interfere with the appellate order.
Therefore, the ITAT dismissed the appeal of the revenue and upheld the CIT(A)’s order.
| Case Title | ITO vs. Aakriti Overseas Pvt. Ltd. |
| Case No. | I.T.A. No. 2728/KOL/2026 |
| Applicant by | Shri Amit Agarwal |
| Respondent by | Shri Haridas Rajkumar |
| Kolkata ITAT | Read Order |