

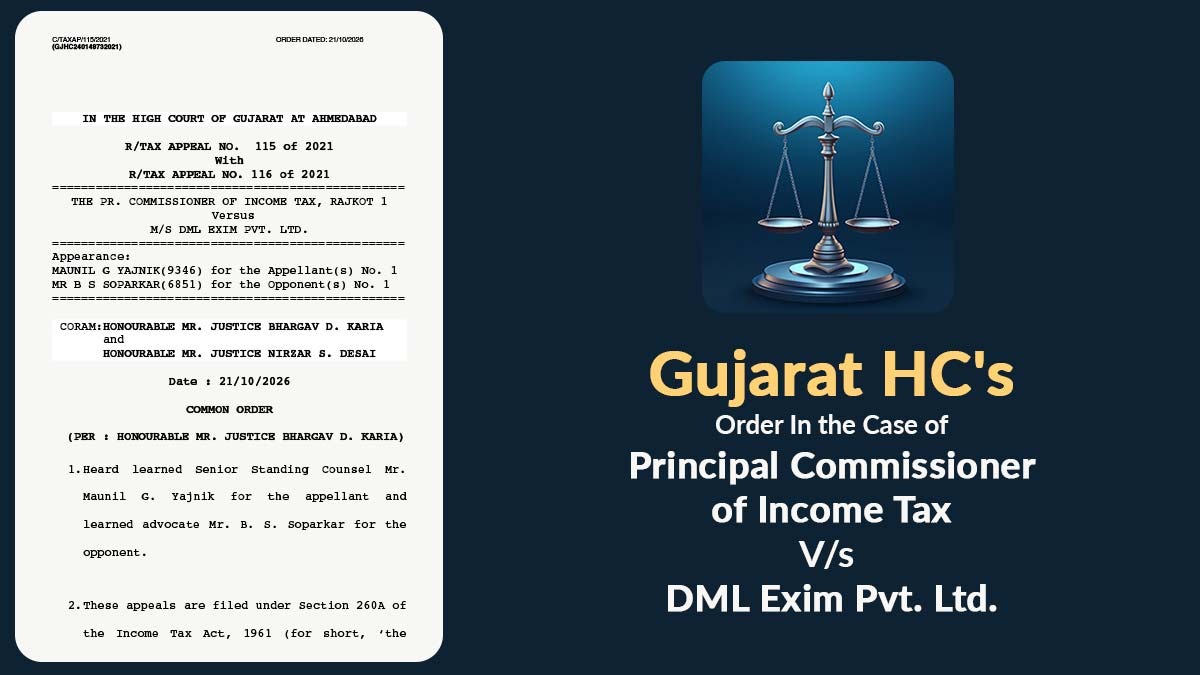
The Gujarat High Court had dismissed the revenue’s appeal against DML Exim Pvt. Ltd. (AY 2011–12 and 2012–13). The ruling came in the Revenue’s appeals against relief granted to DML Exim Pvt. Ltd., which is engaged in trading agricultural products, building construction, and power generation. The appeals are of Assessment Years 2011-12 and 2012-13.
The commission was paid to non-resident agents for services rendered outside India, which included soliciting customers for the company’s export business. The court agreed with the findings of both the Commissioner of Income Tax (Appeals) and the Income Tax Appellate Tribunal, concluding that the payments were not taxable in India due to the absence of a business connection. Therefore, there was no basis to uphold the disallowances.
The appeals also involved contract cancellation charges of ₹2.80 crore for the Assessment Year 2012-13 and ₹10.04 crore for the Assessment Year 2011-12. While the Assessing Officer classified the ₹2.80 crore as a speculative loss, the Revenue contested the legitimacy of the ₹10.04 crore in cancellation charges.
DML Exim said that it engaged in forward contracts with banks to protect itself against currency fluctuations while executing export contracts. The court acknowledged that the company was not a foreign exchange dealer and accepted the concurrent findings that these contracts were a part of its regular business operations. It concluded that the resulting loss was not considered speculative u/s 43(5) of the Act.
The Gujarat High Court upheld the removal of four major tax disallowances:
Commissions paid to non-resident agents located abroad in connection with an export business are classified as ‘business income’ rather than ‘fees for technical services.’ In the absence of any business connection within India, such payments are not subject to local taxation, nor is there any requirement to deduct tax at source (TDS).
The amounts paid to foreign buyers following a failure to fulfil export contracts were directly related to business dealings; these were neither losses from speculation nor the result of fictitious transactions.
Losses incurred from ‘advance forward contracts’ entered into for the purpose of hedging against currency fluctuations were treated as normal business expenses, rather than as speculative transactions under Section 43(5).
The decision to disallow interest expenditure was set aside because the Assessing Officer had failed to record the mandatory satisfaction before invoking Section 14A (read with Rule 8D).
| Applicant Name | Principal Commissioner of Income Tax Vs DML Exim Pvt. Ltd. |
| GSTIN of the applicant | R/TAX APPEAL NO. 115 of 2021 |
| Applicant | Maunil G Yajnik |
| Respondent | Mr B S Soparkar |
| Gujarat High Court | Read Order |