

The taxpayer is Mr Abdul Rahim, who was engaged in the business of trading Basmati rice through his proprietorship, M/s. Excellent Food Products. He also owned a restaurant named M/s. A.R. Rahaman Biryani.
On August 24, 2015, a search and seizure operation was conducted at Mr Rahim’s residence, along with a survey at his business premises, as part of the investigation into the SS Hyderabad Biryani Private Limited group. Following this, a notice u/s 153A of the Income Tax Act was issued. Mr Rahim subsequently filed his return, reporting a total income of Rs. 4,51,958.
AO, in the assessment proceedings, made an addition of Rs. 56,07,751 u/s 69C of the Act. The taxpayer contested the addition before the CIT(A), but the appeal was dismissed.
Afterwards, the taxpayer approached the ITAT Chennai in ITA Nos. 1062 to 1067/Chny/2024. By its order dated September 27, 2024, the Tribunal deleted the addition made under section 69C and asked the AO to evaluate the income by applying an estimated profit rate of 5% to the relevant figures.
From this order, the AO levied penalties u/s 271(1)(c) of the Act via an order dated 16 March 2025. The taxpayer contested the penalties before the CIT(A), which dismissed the appeal.
The Tribunal reviewed the assessment orders, the decisions made by the Commissioner of Income Tax (Appeals) [CIT(A)], and the submissions from both parties. It observed that the original addition u/s 69C had already been removed during the quantum proceedings, and the income was subsequently calculated using an estimated profit rate of 5%.
The Tribunal noted that the penalties imposed were based on this estimated income. The Tribunal said that the legal stance regarding the imposition of penalties on estimated additions was established in favour of the taxpayer.
Read Also: Delhi HC Cancels Tax Penalty U/S 271(1)(c) Due to Defective Notice
It found that the Revenue did not present any new facts to differentiate its position from the precedents cited by the taxpayer. As a result, the Tribunal concluded that the penalties imposed on the estimated income could not be upheld and accepted the taxpayer’s arguments.
It allowed all four appeals filed by Mr Abdul Rahim for the Assessment Years 2010-11, 2012-13, 2014-15, and 2015-16. The Tribunal ordered the removal of the penalties contested in these appeals, including those related to estimated income and income from house property for the relevant assessment years.
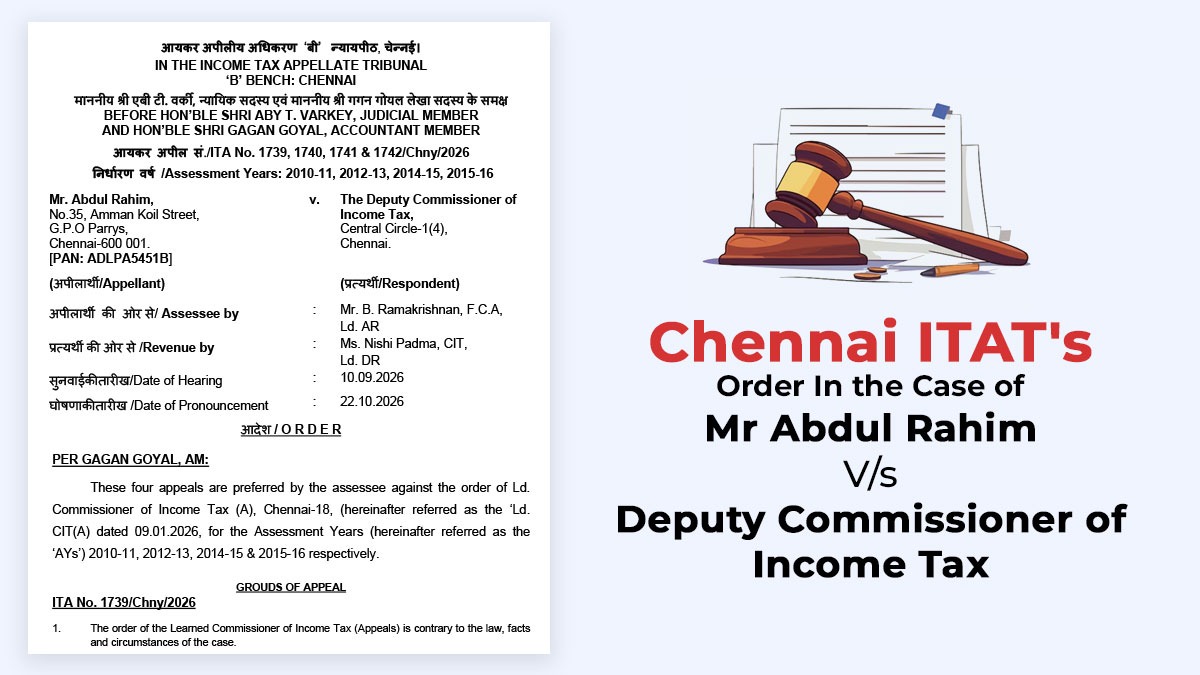
| Case Title | Mr Abdul Rahim Vs Deputy Commissioner of Income Tax |
| Case No. | ITA Nos. 1739, 1740, 1741 & 1742/Chny/2026 |
| Appellant by | Mr B. Ramakrishnan |
| Respondent by | Ms Nishi Padma |
| Chennai ITAT | Read Order |