

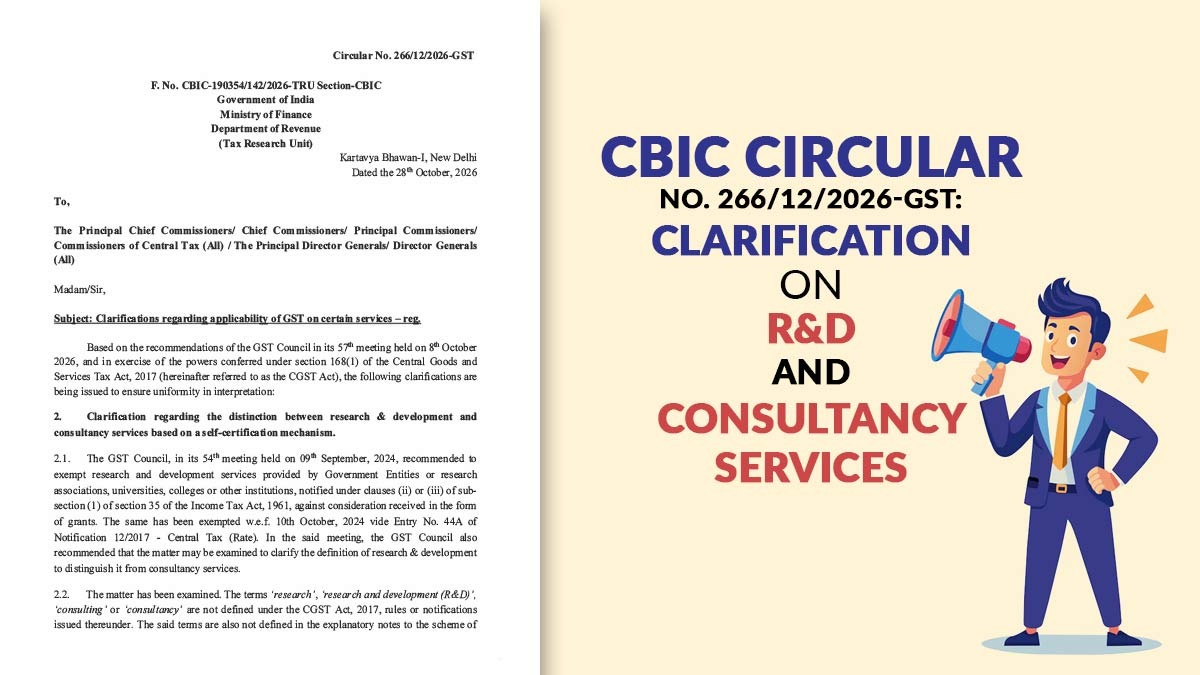
The Central Board of Indirect Taxes and Customs (CBIC) issued Circular No. 266/12/2026-GST dated October 28, 2026, clarifying the distinction between research and development (R&D) services and consultancy services under GST.
This clarification follows the recommendations made at the 57th GST Council meeting on October 8, 2026. The objective is to promote uniformity in the interpretation and application of the GST provisions.
GST Relief for Research and Development Services
The issue originates from the 54th GST Council meeting, which took place on September 9, 2024. During this meeting, the Council recommended an exemption for specific research and development services provided by eligible government entities, research associations, universities, colleges, and other institutions recognised under clauses (ii) or (iii) of Section 35(1) of the Income Tax Act, 1961. This exemption applies when the consideration is received in the form of grants.
This exemption was then rolled out w.e.f. October 10, 2024, via Entry No. 44A of Notification No. 12/2017-Central Tax (Rate).
The council suggested analysing the definition of research and development to specify how these services are to be differentiated from consultancy services.
Reason for required clarification
A key issue was that the CGST Act, 2017, the rules and notifications issued thereunder, and the explanatory notes to the scheme of classification of services did not provide clear definitions for terms such as ‘research’, ‘research and development’, ‘consultancy’, and ‘consultancy service’.
Also Read: CBIC Expands GST E-Invoicing to RCM Supplies and Import of Services from January 1, 2027
The distinction is crucial when deciding whether a specific service comes under the extent of the exemption available for eligible R&D services furnished against grants.
The updated circular addresses the issue as part of the government’s measures to ensure a consistent interpretation of GST norms.
Key Details of CBIC New Circular No. 266/12/2026-GST
- Circular Number: 266/12/2026-GST
- Issued Date: October 28, 2026
- Authority that issued: CBIC, Ministry of Finance, Department of Revenue
- Main Subject: Clarifications regarding the applicability of GST on certain services
- Law Origin: Section 168(1) of the Central Goods and Services Tax Act, 2017
- Appropriate GST Council Meeting: 57th meeting held on October 8, 2026
- Issues: Distinguishing research and development services from consultancy services through a self-certification mechanism.
What do assessee and institutions ought to follow?
Eligible institutions and professionals associated with research grants should analyse this circular in the context of the existing exemption available under entry 44A of Notification No. 12/2017-Central Tax (Rate).
When assessing the GST provisions applicable to services provided under research-related agreements, the distinction between R&D and consultancy services becomes particularly significant. The determination of the appropriate procedure should be based on the relevant notification and the clarifications issued by the CBIC.
The provided extract concludes in paragraph 2.2. It does not contain the detailed self-certification procedure or the full set of criteria for distinguishing between R&D and consultancy services. Before reaching any final decision regarding GST classification or exemptions, these details should be verified against the complete circular.
Closure: The Circular No. 266/12/2026-GST clarifies an important interpretive issue regarding GST on Research and Development (R&D) and consultancy services. CBIC has proceeded to take forward the recommendations of the GST Council; the CBIC aims to bring greater clarity and uniformity regarding specific R&D services, especially those provided by eligible institutions in exchange for grants.
Taxpayers and institutions must refer to the circular and the applicable GST exemption notification before determining the taxability of a transaction.
Read Circular No. 266/12/2026-GST