

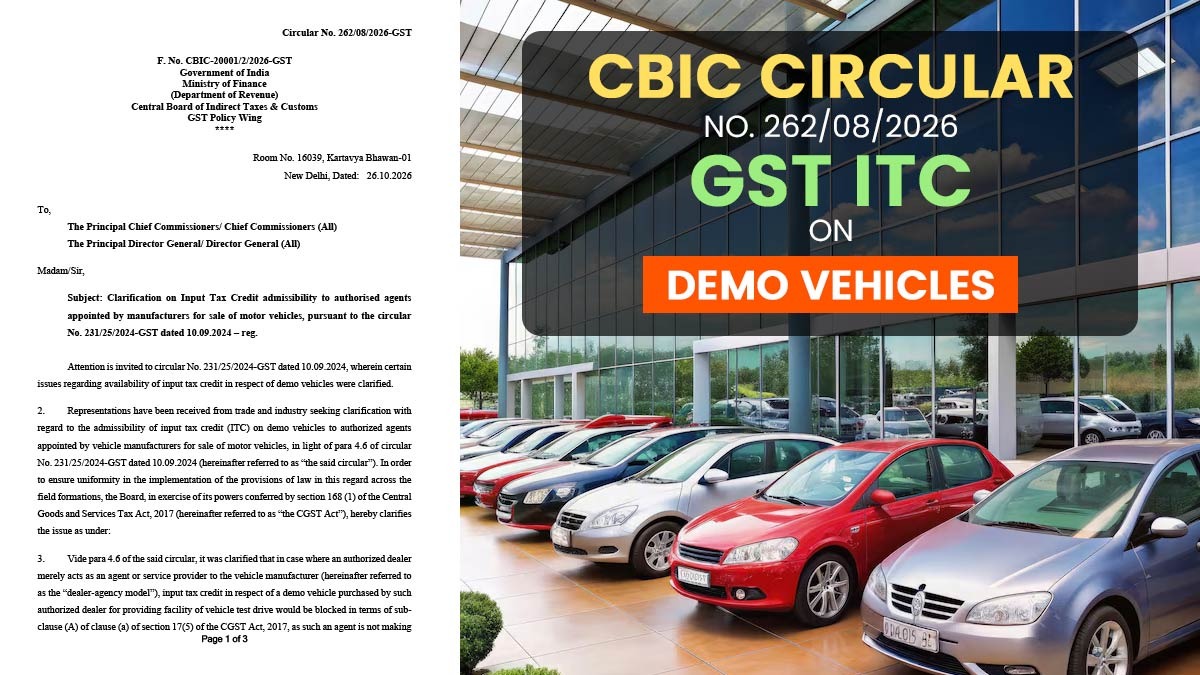
The Central Board of Indirect Taxes and Customs (CBIC), under the Ministry of Finance (Department of Revenue), has issued a circular (No. 262/08/2026-GST) dated October 26, 2026, in exercise of the powers conferred by Section 168(1) of the Central Goods and Services Tax (CGST) Act, 2017.
This circular, with reference to the earlier circular dated September 10, 2024 (No. 231/25/2024-GST), provides clarification regarding the GST ITC available to authorised agents appointed by manufacturers for the sale of motor vehicles.
In the recent circular, the CBIC referenced Circular No. 231/25/2024-GST, which clarified specific issues related to the availability of ITC for demo vehicles.
The CBIC has stated that, with reference to Circular No. 231/25/2024-GST dated September 10, 2024, this clarification has been issued following several representations received from the trade and industry.
These representations pertain to the eligibility for Input Tax Credit (ITC) on ‘demo vehicles’ held by authorised agents appointed by vehicle manufacturers for the sale of motor vehicles.
The tax authorities in paragraph 4.6 of the said circular had expressed that when an authorised dealer is only an agent or service provider to the vehicle manufacturer, then the ITC will be blocked under subclause (A) of clause (a) of Section 17(5) of the CGST Act, 2017, concerning a demo vehicle purchased by such authorised dealer for providing the facility of vehicle test drive.
According to the paragraph, the reason for this is that, in such circumstances, the supply of motor vehicles is not made by the authorised dealer; rather, only marketing or facilitation services are provided to the vehicle manufacturer.
However, the present Circular No. 262/08/2026-GST, dated October 26, 2026, states that the CBIC has officially withdrawn the above-mentioned paragraph 4.6 of the Circular No. 231/25/2024-GST dated September 10, 2024.
Also Read: GST Impact on Buying and Selling Used Cars
Also, the circular mentions that “the input tax credit on the demo vehicles is not blocked under clause (a) of section 17(5) of the CGST Act, to the dealer in the dealer-agency model.”
Read CBIC Circular No. 262/08/2026-GST