

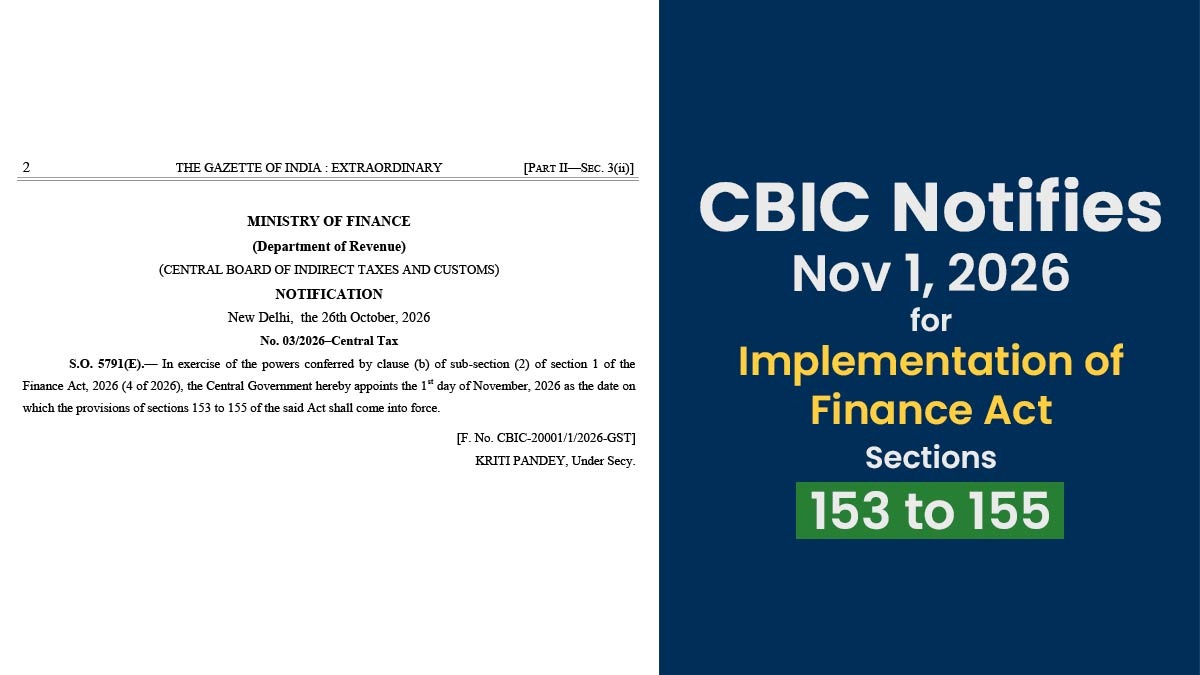
The Central Board of Indirect Taxes and Customs (CBIC), under the Ministry of Finance (Department of Revenue), has officially set the date for the implementation of the provisions contained in Sections 153 to 155 of the Finance Act, 2026.
The above disclosure has been made through Notification No. 03/2026–Central Tax, issued by the Central Government on October 26, 2026, in exercise of the powers conferred by clause (b) of sub-section (2) of Section 1 of the said Act.
As per the notification, the effective date for Sections 153 to 155 of the Finance Act, 2026, is November 1, 2026.
Key takeaways of Sections 153 to 155 of the Finance Act 2026:
- Section 15(3)(b) of the CGST Act has been amended to provide that post-supply discounts may not be included in the value of supply where-
- A credit note has been issued by the supplier and
- The recipient, in accordance with Section 34, reverses the input tax credit of such an exemption.
- Section 34(1) has been revised to allow the issuance of a credit note where a discount referred to in Section 15(3)(b) is granted after the supply has been effected.
- Section 54(6) has been amended to extend the provision for ‘provisional refund’ to cases involving the refund of unused input tax credit. This will apply in instances where a refund is permitted under clause (ii) of the first proviso to Section 54(3).
- Section 54(14) has been amended to create an exception for refund claims related to goods exported from India upon payment of tax.
- These amendments provide a clear legal framework under the GST regime for ‘post-supply discounts’. Under this, the availability of valuation-related benefits is linked to the issuance of ‘credit notes’ and the reversal of the corresponding input tax credit (ITC) by the recipients.
- The amendments widen the scope of provisional refunds and furnish clarifications for the refund claims, including unused ITC and exports.
Read the Official Notification