

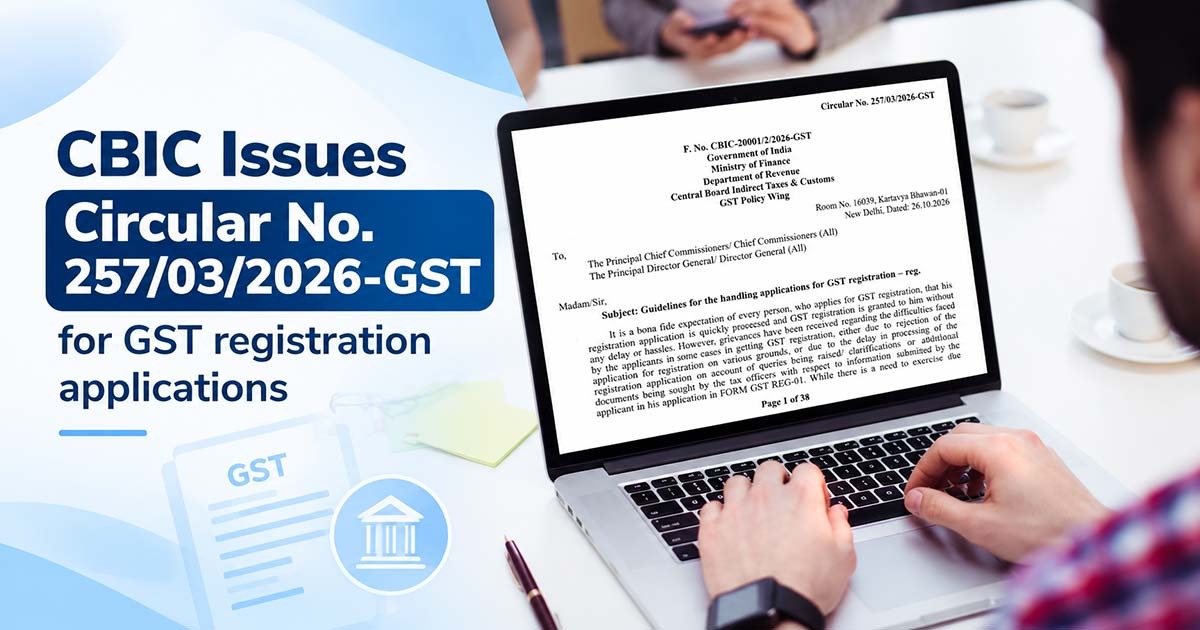
The Central Board of Indirect Taxes and Customs (CBIC), in exercise of its powers granted u/s 168(1) of the Central Goods and Services Tax (CGST) Act, 2017, has issued guidelines for managing the applications for GST registration, vide Circular No. 257/03/2026-GST dated October 26, 2026, under the Ministry of Finance (Department of Revenue).
The purpose of the guidelines is to promote uniformity in the GST registration process and streamline the process for genuine applicants.
The board noted that it had received several representations expressing concerns about the challenges faced by applicants in obtaining their GST registration.
These challenges arise either from the rejection of registration applications for various reasons or from delays in processing due to queries, requested clarifications, or additional documents sought by tax officers regarding the information provided in FORM GST REG-01.
The circular specifies that applicants frequently encounter delays or rejection of their GST registration applications because of a lack of information, wrong or inconsistent data, incomplete documents, or unclear document uploads.
Common issues relate to the applicant’s identification details, proof of the principal place of business, the nature of the business, and the identification details of the authorised signatory.
CBIC said that, when receiving GST registration, genuine applicants must not encounter any issues. Meanwhile, proper verification is required to prevent the issuance of bogus registrations using the identities of other persons.
These bogus registrations are used to pass ineligible ITC without any actual supply of goods or services, which leads to a loss of revenue to the government and affects honest taxpayers.
The Board stated that, despite the issuance of Instruction No. 03/2025-GST on April 17, 2025, further guidance is needed for applicants to ensure that their applications are correct and include all necessary supporting documents.
Read CBIC Circular No. 257/03/2026-GST