

On 26 February 2022, the adjudicating authority, Deputy Commissioner, State Tax, passed an order against the taxpayer. Ordinarily, the first appeal u/s 107 of the CGST or UPGST Acts had to be filed within 3 months of the order’s communication.
The taxpayer filed the first appeal on 31 January 2024, relying on the amnesty scheme notified vide Notification No. 53/2023 dated 2 November 2023, which allowed eligible taxpayers to file certain time-barred appeals subject to prescribed conditions.
As per the scheme, the taxpayer must deposit 12.5% of the remaining disputed tax, with at least 20% of that pre-deposit being paid via the electronic cash ledger.
The taxpayer claimed that technical issues on the GST portal prevented the requisite allocation via the electronic cash ledger, and therefore the entire pre-deposit was debited via the electronic credit ledger. The first appellate authority set aside the appeal on the taxpayer’s failure to appear on the scheduled hearing date.
The Tribunal noted that under the amnesty scheme, eligible taxpayers were permitted to have their time-barred appeals accepted, subject to the condition of paying a specified pre-deposit amount.
In this case, the taxpayer had carried that it had made a bona fide attempt to comply with the scheme but failed to make the required cash-ledger payment due to technical problems.
Read Also: GSTN Releases Guidelines for Taxpayers Seeking Relief Under GST Amnesty Scheme
The Tribunal held that a shortfall or incorrect allocation of pre-deposit components is an error that can be rectified.
The First Appellate Authority made a mistake by summarily dismissing the appeal without providing the taxpayer a reasonable chance to pay the differential cash amount or to rebalance the ledger debit.
The Tribunal ruled that rejecting the appeal only because the pre-deposit was deducted via the electronic credit ledger was not legally justifiable.
It emphasised that technical issues on the GST portal should not hinder a taxpayer’s right to appeal. Consequently, the GSTAT allowed the appeal and overturned the order dated September 25, 2024, which dismissed the taxpayer’s initial appeal as being filed too late.
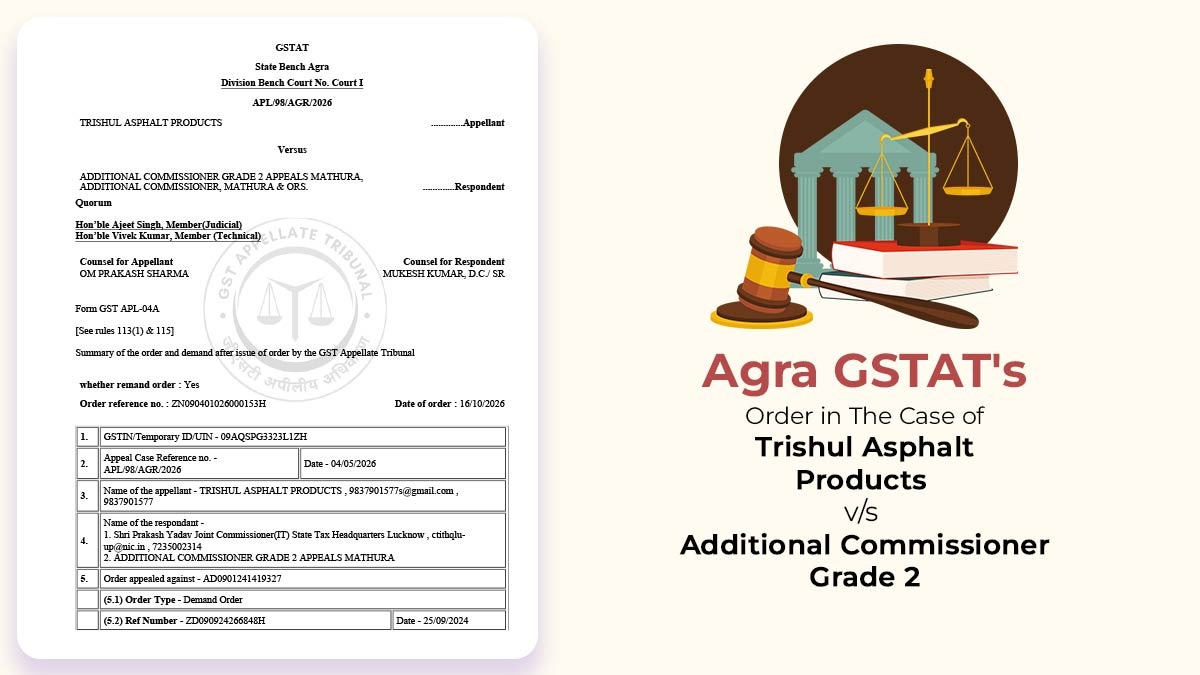
| Case Title | Trishul Asphalt Products vs. Additional Commissioner Grade 2 |
| GSTIN/Temporary ID/UIN | 09AQSPG3323L1ZH |
| Counsel for Appellant | Om Prakash Sharma |
| Counsel for Respondent | Mukesh Kumar |
| Agra GSTAT | Read Order |