

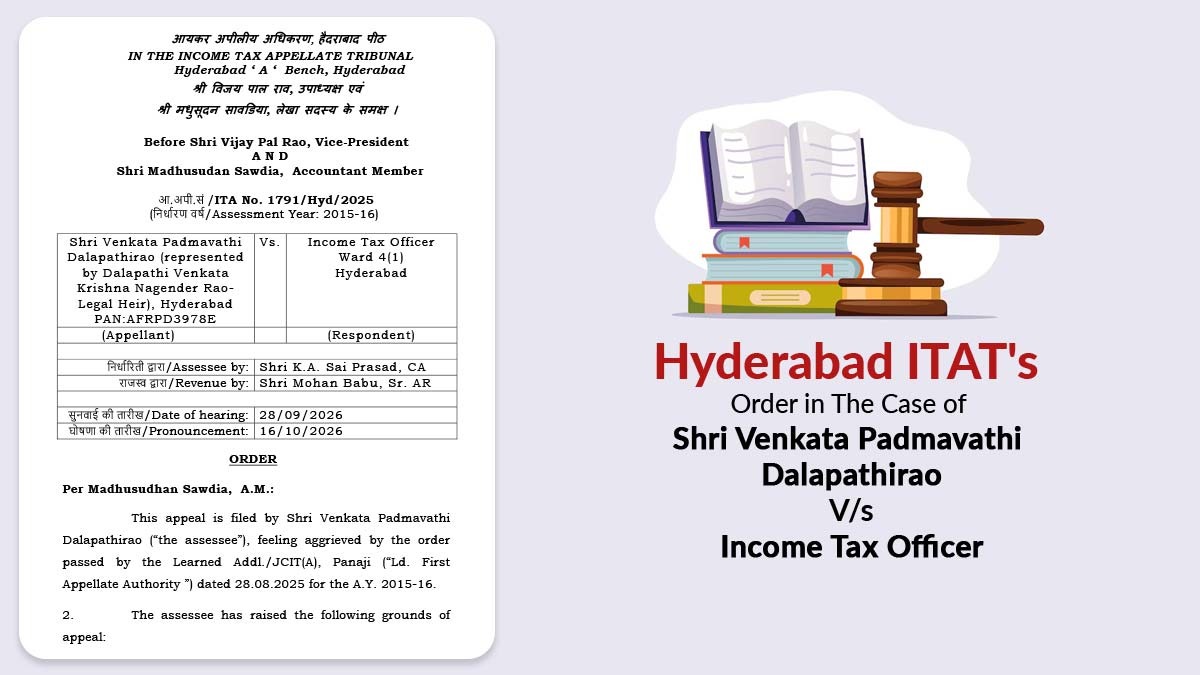
The ITAT Hyderabad Bench did not validate the entire reassessment proceedings for AY 2015-16 after noting that the section 148 notice was not signed digitally or manually by the assessing officer.
The Assessing Officer (AO) reopened the case of Shri Venkat Padmavati Dalapatirao (the taxpayer). Subsequently, in an assessment order issued on December 27, 2018, passed under section 143(3) read with section 147 of the Act, an amount of Rs 63.29 lakh was added under the head of Long-Term Capital Gains (LTCG) arising from the sale of immovable property.
The taxpayer was not satisfied with the order of the AO and contested the same before the Commissioner of Income Tax (Appeals) [CIT(A)]; however, the impugned addition was upheld. Following this, the taxpayer approached the Income Tax Appellate Tribunal (ITAT).
The taxpayer before the ITAT contested the validity of the reassessment proceedings, claiming that the notice issued u/s 148 did not have a manual or digital signature of the assessing officer.
The taxpayer placed reliance on the decision of the Bombay High Court in Prakash Krishnavtar Bhardwaj v. ITO, which stated that an unsigned notice u/s 148 was not valid and could not grant jurisdiction for reassessment.
The Tribunal had analysed the notice and heard both parties, and it determined that the notice in the case was not signed. After the ruling of the Bombay High Court, it said that “the unsigned notice issued under section 148 of the Act is invalid. Consequently, the assessment order dated 27.12.2018, passed under section 143(3) read with section 147 of the Act pursuant to such notice, is without jurisdiction and is hereby quashed.”
Subsequently, the Tribunal stated that the entire reassessment proceedings is not valid under the law, and therefore it set aside the assessment order dated December 27, 2018, because of no jurisdiction.
Read Also: Calcutta HC Suspends IT Reassessment Section 148 Over Ignored Reply to Notice U/S 133(6)
Since the reassessment was invalidated on this legal ground, the Tribunal did not examine the remaining grounds of appeal. The taxpayer’s appeal was permitted.
| Case Title | Shri Venkata Padmavathi Dalapathirao vs. Income Tax Officer |
| Case No. | ITA No. 1791/Hyd/2025 |
| Assessee by | Shri K.A. Sai Prasad |
| Revenue by | Shri Mohan Babu |
| Hyderabad ITAT | Read Order |