

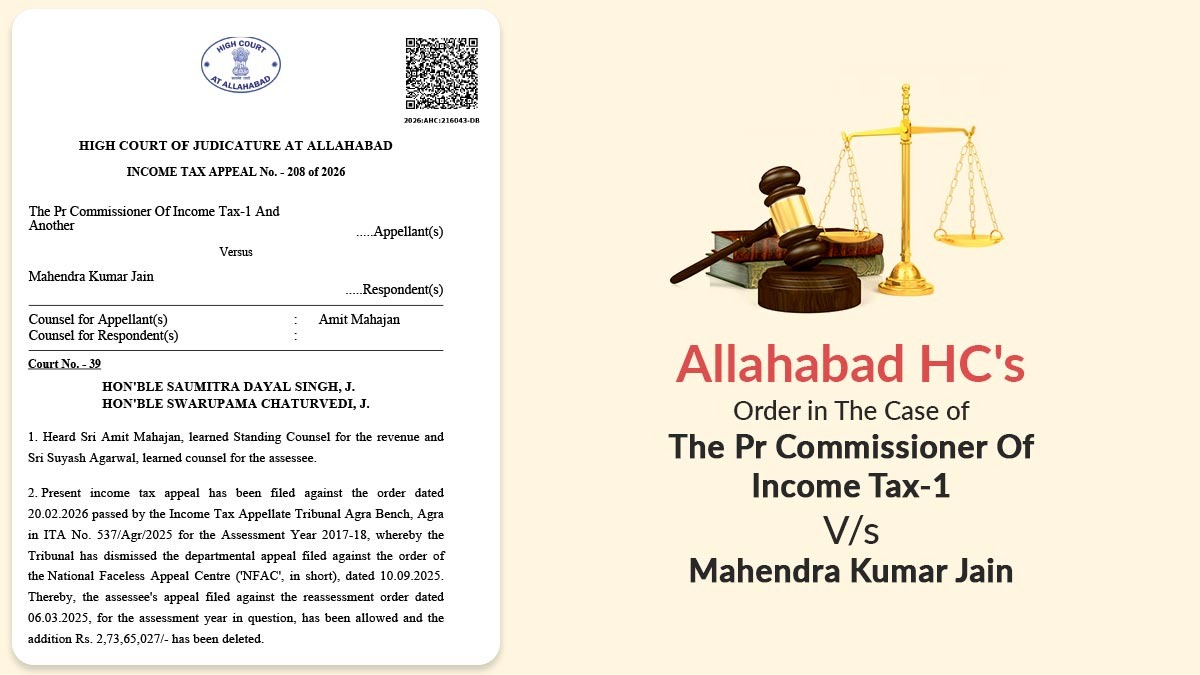
The Allahabad High Court has maintained the removal of a Rs 2.73 crore addition made u/s 68 of the Income Tax Act, 1961, holding that the revenue should specify escaped income with reference to the material on record and cannot sustain reassessment only by questioning the adequacy of proof provided in the original assessment.
The bench comprising Justice Soumitra Dayal Singh and Justice Swarupama Chaturvedi found no evidence to prove that any information had been concealed or that the department had provided any incorrect information.
Therefore, the disputed ‘addition’ (the amount added) cannot be sustained based on the alleged deficiencies in the evidence.
The taxpayer runs a sole proprietorship engaged in the jewellery trade. He said that he also inherited an ancestral business carried on under the name M/s Devi Abhushan Bhandar during the relevant previous year.
Following the merger of the two businesses, the proprietor’s capital in the inherited undertaking was incorporated into their total capital. The decision records an increase of ₹2,78,82,287 in the proprietor’s capital.
In the original scrutiny assessment u/s 143(3), the assessing authority had questioned this surge. However, no additional amount was added on this basis, and the assessment was completed based on the declared income of ₹18,30,550.
Subsequently, reassessment proceedings were initiated after an audit objection. The assessing authority considered the disputed capital amount as undisclosed income and made an addition of ₹2,73,65,027.
In doing so, the authority noted that the taxpayer had not filed a revised return, and further, there was no documentary evidence to show that the capital increase had resulted from the merger of two businesses.
The National Faceless Appeal Centre permitted the taxpayer’s appeal on September 10, 2025, removing the addition made via the reassessment order dated March 6, 2025.
Afterwards, the Income Tax Appellate Tribunal, Agra Bench, dismissed the departmental appeal on February 20, 2026.
The revenue before the High Court had asked whether the decision of the Tribunal was unreasonable because it had considered the rise in the capital as a book entry arising from the merger of personal and inherited business accounts.
The department claimed that the taxpayer had not discharged his accountability to specify the genuineness, source and actual inception of the capital via authentic corroborative proof.
The High Court denied the challenge and determined that the revenue did not have any positive evidence or material on record to establish that the disputed amount did not constitute capital already available in the ancestral business.
The Bench observed that the department did not analyse the books of M/s Devi Abhushan Bhandar or consider its returns to determine whether the capital was available in that regard. Revenue did not object to the merger of the two pre-existing businesses.
The court held that the disputed amount cannot be re-evaluated unless the assessing authority possesses prima facie evidence suggesting that the capital in question did not exist in the ancestral business, or evidence that provides a basis for disbelieving the explanation offered by the taxpayer regarding the merger.
No grounds had been established as per the facts.
The Bench distinguished reassessment proceedings and revision u/s 263 of the Act.
The Assessing Authority could not uphold reassessment by citing that the taxpayer did not provide adequate proof in the original assessment.
The court stated that such an argument might be relevant in proceedings initiated u/s 263, but it cannot, by itself, justify the addition of any further amount during a reassessment.
For any addition to income during a reassessment to be sustained, the Revenue Department had to demonstrate, based on the material available to it, that such income had escaped assessment due to a failure to disclose it or an incorrect disclosure.
Read Also: Allahabad ITAT Deletes Rs. 80.60 Lakh Addition Over One-Digit Error in ITR Sales Entry
The High Court concluded that the Tribunal’s findings were based on the facts and did not warrant any interference in the appeal. The Court dismissed the Revenue Department’s appeal, deeming it groundless, and made no order as to costs.
| Case Title | Pr Commissioner Of Income Tax-1 vs. Mahendra Kumar Jain |
| Case No. | 208 of 2026 |
| Counsel for Appellant | Amit Mahajan |
| Allahabad High Court | Read Order |